


To become a fractional CFO, you need roughly a decade of progressive finance experience that includes leading planning, reporting and capital decisions, a credential that buyers recognize (most often the CPA, with the CMA and CFA as alternatives), and a small business of your own that can price, sell and deliver part-time CFO work to several companies at once. Most practitioners find the selling and setup harder than the finance work.
This guide is written for finance professionals planning how to become a fractional CFO in 2026: controllers, FP&A leaders, public accounting managers and full-time CFOs. It covers the experience paths that work, what each credential requires, how to set up the entity and taxes, how to price, and a worked income example built on federal wage data. If you are a business owner looking to hire one instead, our guide to questions to ask a fractional CFO before you hire one is the better starting point.
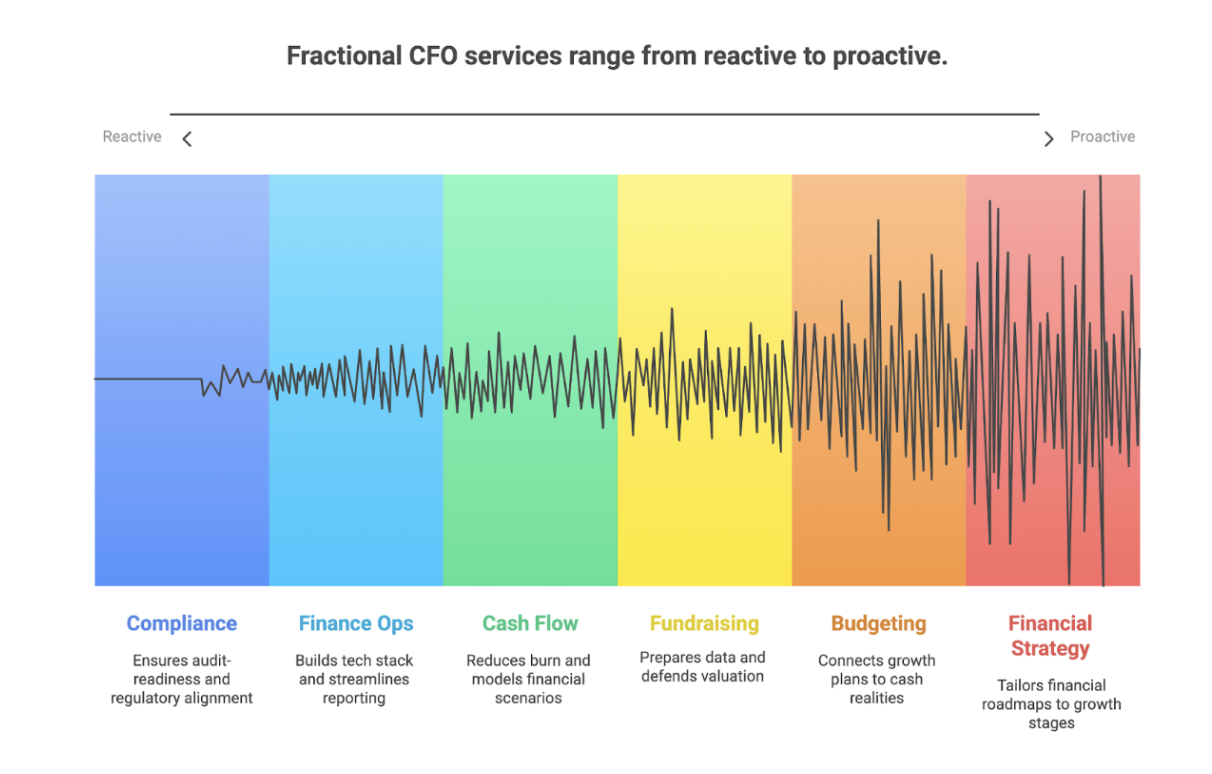
A fractional CFO carries a full-time CFO's responsibilities, compressed into a set number of hours each month per client: cash forecasting, budgets, board and lender reporting, margin analysis and fundraising support. Our summary of what CFOs do lists the full scope from the client's side.
The difference is the operating rhythm. You will juggle several clients, each with its own systems, bookkeeper and priorities. Clients often confuse the CFO and controller roles, and the comparison of controller vs fractional CFO responsibilities helps with scoping. Some buyers search for a virtual CFO when they mean the same remote, part-time model, so use both terms in your own marketing.
Several of these steps can run in parallel while you are still employed.
There is no license called "fractional CFO," so clients judge you on what you have already done. The Bureau of Labor Statistics reports that financial managers typically need a bachelor's degree and 5 years or more of experience. Most people who build a fractional practice have spent well beyond that minimum in senior roles.
Three routes are common:
Whichever route you take, aim to have led at least one of the events clients pay a premium for: a debt raise, an equity round, an acquisition or sale, a system migration, or a turnaround.
A credential is optional for most fractional CFO work. BLS notes that although professional certification is not required, it "indicates competence" for financial managers who hold it. The three credentials below are the ones buyers recognize most often. Requirements change, so confirm them with each body before you enroll.
| Credential | Issued by | Education | Experience | Exam |
|---|---|---|---|---|
| CPA | State boards of accountancy | Bachelor's with an accounting concentration plus 30 more credits (or a master's), or bachelor's alone in states that adopted the newer pathway | 1 year supervised, or 2 years under the bachelor's-only pathway | Uniform CPA Examination |
| CMA | Institute of Management Accountants (IMA) | Bachelor's from an accredited institution or a related professional certification | 2 continuous years in management accounting or financial management | Parts 1 and 2, within 3 years |
| CFA | CFA Institute | Bachelor's degree, a student near graduation, or a mix of work and education hours (check CFA Institute registration rules) | At least 4,000 hours over a minimum of 36 months | Three levels plus Practical Skills Modules |
CPA. The AICPA's licensure guidance says you can now become a CPA with a bachelor's degree with an accounting concentration, two years of supervised experience and a passing CPA Exam score, but each state must enact legislation or update its rules first, and not all have. The traditional routes (a master's, or a bachelor's plus 30 credits, each with one year of supervised experience) remain available. The CPA matters most if you also want to sign tax returns or offer attest services, which states regulate.
CMA. The IMA requires active IMA membership, a bachelor's degree or related professional certification, and two continuous years of professional experience in management accounting or financial management. Candidates have three years to pass both exam parts.
CFA. The CFA Institute requires that all three exam levels be completed, plus the Practical Skills Modules, and at least 4,000 hours of work experience over a minimum of 36 months. It is most useful if your niche is fundraising, investor relations, treasury or companies with investment portfolios.
The setup decisions below affect your liability and your taxes.
Most new fractional CFOs start as a single-member LLC. By default, the IRS disregards a single-member LLC for income tax, so profit flows onto your Schedule C and the LLC mainly provides a liability boundary and a business identity. Our single-member LLC taxation guide covers the filing mechanics.
As profit grows, many practitioners elect S corporation status so that only a salary bears payroll taxes and the remaining profit is paid as distributions. That election is made on Form 2553, explained in our guide to making an S corp election. Read the rules on reasonable compensation for S corp owners before you assume the election saves money.
As a sole proprietor or single-member LLC owner, you pay both halves of Social Security and Medicare. The IRS sets the self-employment tax at 12.4% for Social Security and 2.9% for Medicare, applied generally to 92.35% of net earnings from self-employment, and you can deduct one-half of it when figuring adjusted gross income. The Social Security part stops at the annual wage base, and for earnings in 2026, this base limit is $184,500. The Medicare part has no cap.
No employer withholds for you, so you will make quarterly estimated payments. Our 2026 quarterly estimated tax guide has the due dates and safe harbors.
Consulting, accounting and financial services are among the fields listed in the statute as specified service trades or businesses for the qualified business income deduction. That means the deduction phases out once taxable income passes a threshold. Rev. Proc. 2025-32 sets the 2026 threshold at $201,750 for single and head of household filers and $403,500 for joint filers, with the phase-out complete at $276,750 and $553,500. The 2025 tax law known as the One Big Beautiful Bill Act removed the deduction's scheduled end date and widened the phase-in range. The Section 199A deduction guide walks through the calculation.
As a matter of practitioner guidance, three protections are worth arranging before the first engagement:
Most fractional CFOs work as independent contractors, and both you and your clients have an interest in the relationship being classified correctly. The IRS looks at the facts under three categories: behavioral control, financial control and the type of relationship.
You strengthen contractor status by running your own business visibly. Serve several clients, invoice through your entity, use your own equipment and software where practical, set your own working methods, and avoid employee benefits from any client. Clients will report your fees on Form 1099-NEC when payments pass the reporting threshold, which changed for 2026 as described in our article on the 2026 1099 reporting threshold.
Most practices mix the four models below. Market rates by sector are summarized in our fractional CFO rates by industry guide, which shows what buyers expect to pay.
| Model | How it works | Best for | Watch out for |
|---|---|---|---|
| Hourly | Bill tracked time at a set rate | Short diagnostics, ad hoc questions | Caps income at hours worked; clients watch the meter |
| Monthly retainer | Fixed fee for a defined scope and cadence | Ongoing CFO support, board and lender reporting | Scope creep unless the letter lists what is included |
| Project fee | Fixed price for a deliverable | Fundraising models, budgets, system selection, diligence prep | Underestimating hours on a first project |
| Value-based | Fee tied to the value of the outcome to the client | Experienced practitioners in a clear niche | Needs strong discovery and a confident pricing conversation |
A sensible approach for a new practice is a monthly retainer as the base, with project fees for one-off work and a minimum monthly fee that protects your calendar.
The figures below are illustrative. The salary benchmark comes from BLS; the fees, hours and expenses are assumptions to show the arithmetic.
Step 1: The rate you need to match a salaried job. BLS reports the median annual wage for financial managers was $166,570 in May 2025. An employer paying that salary would also pay 7.65% in Social Security and Medicare, or $12,742.61, which you now pay yourself. Add an assumed $20,000 a year for insurance, software, continuing education, dues and marketing.
That rate only matches the salary. It does not replace employer health insurance, retirement matching or paid leave.
Step 2: A sample client portfolio. Assume three retainer clients at $5,000 a month, each needing about 20 hours a month, plus one $20,000 project that takes 80 hours.
Step 3: Self-employment tax on that profit.
In this sample, the practice clears the Step 1 target on 800 billable hours instead of 1,000. Federal and state income tax come on top and depend on your filing status and other income.
Your first clients usually come from people who already know your work: former employers, bankers, investors, attorneys and tax CPAs. Tell each of them which kind of company you help and which problem you solve. A niche statement such as "cash forecasting and lender reporting for construction firms with $10 million to $50 million in revenue" is easier to refer than "fractional CFO services."
Other channels that work for many practitioners:
Owners usually ask about industry experience, availability and what the first 90 days will produce, so keep a written 90-day plan template ready.
On the client side, expect to work in QuickBooks Online, Xero or NetSuite. Insist on your own user login for each system so access can be removed cleanly when an engagement ends.
For your own practice, you will need:
Do you need to be a CPA to become a fractional CFO? No credential is legally required to provide CFO advisory services. A CPA license matters if you also plan to sign tax returns or provide attest services, and many buyers prefer it.
How many years of experience do you need to become a fractional CFO? There is no fixed rule. BLS data shows financial managers typically need five or more years of experience, and most clients expect fractional CFOs to have well beyond that, including senior roles and at least one capital event.
How much can a fractional CFO earn? In the illustrative example above, three retainers and one project produce $200,000 of revenue on 800 billable hours. The BLS median for financial managers, $166,570, is a useful benchmark when setting your target.
Should a fractional CFO form an LLC or an S corp? Most start with a single-member LLC for simplicity and liability separation, then consider an S corp election once profit is high enough that payroll tax savings exceed the cost of running payroll and paying a reasonable salary.
How many clients can one fractional CFO handle? Practitioners commonly carry a handful of clients at once. The workable number depends on the hours each retainer requires.
Madras Accountancy supports US businesses and CPA firms with bookkeeping, tax preparation, payroll and CFO and advisory work. To discuss how we can support your clients' books and reporting, contact our team.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



