

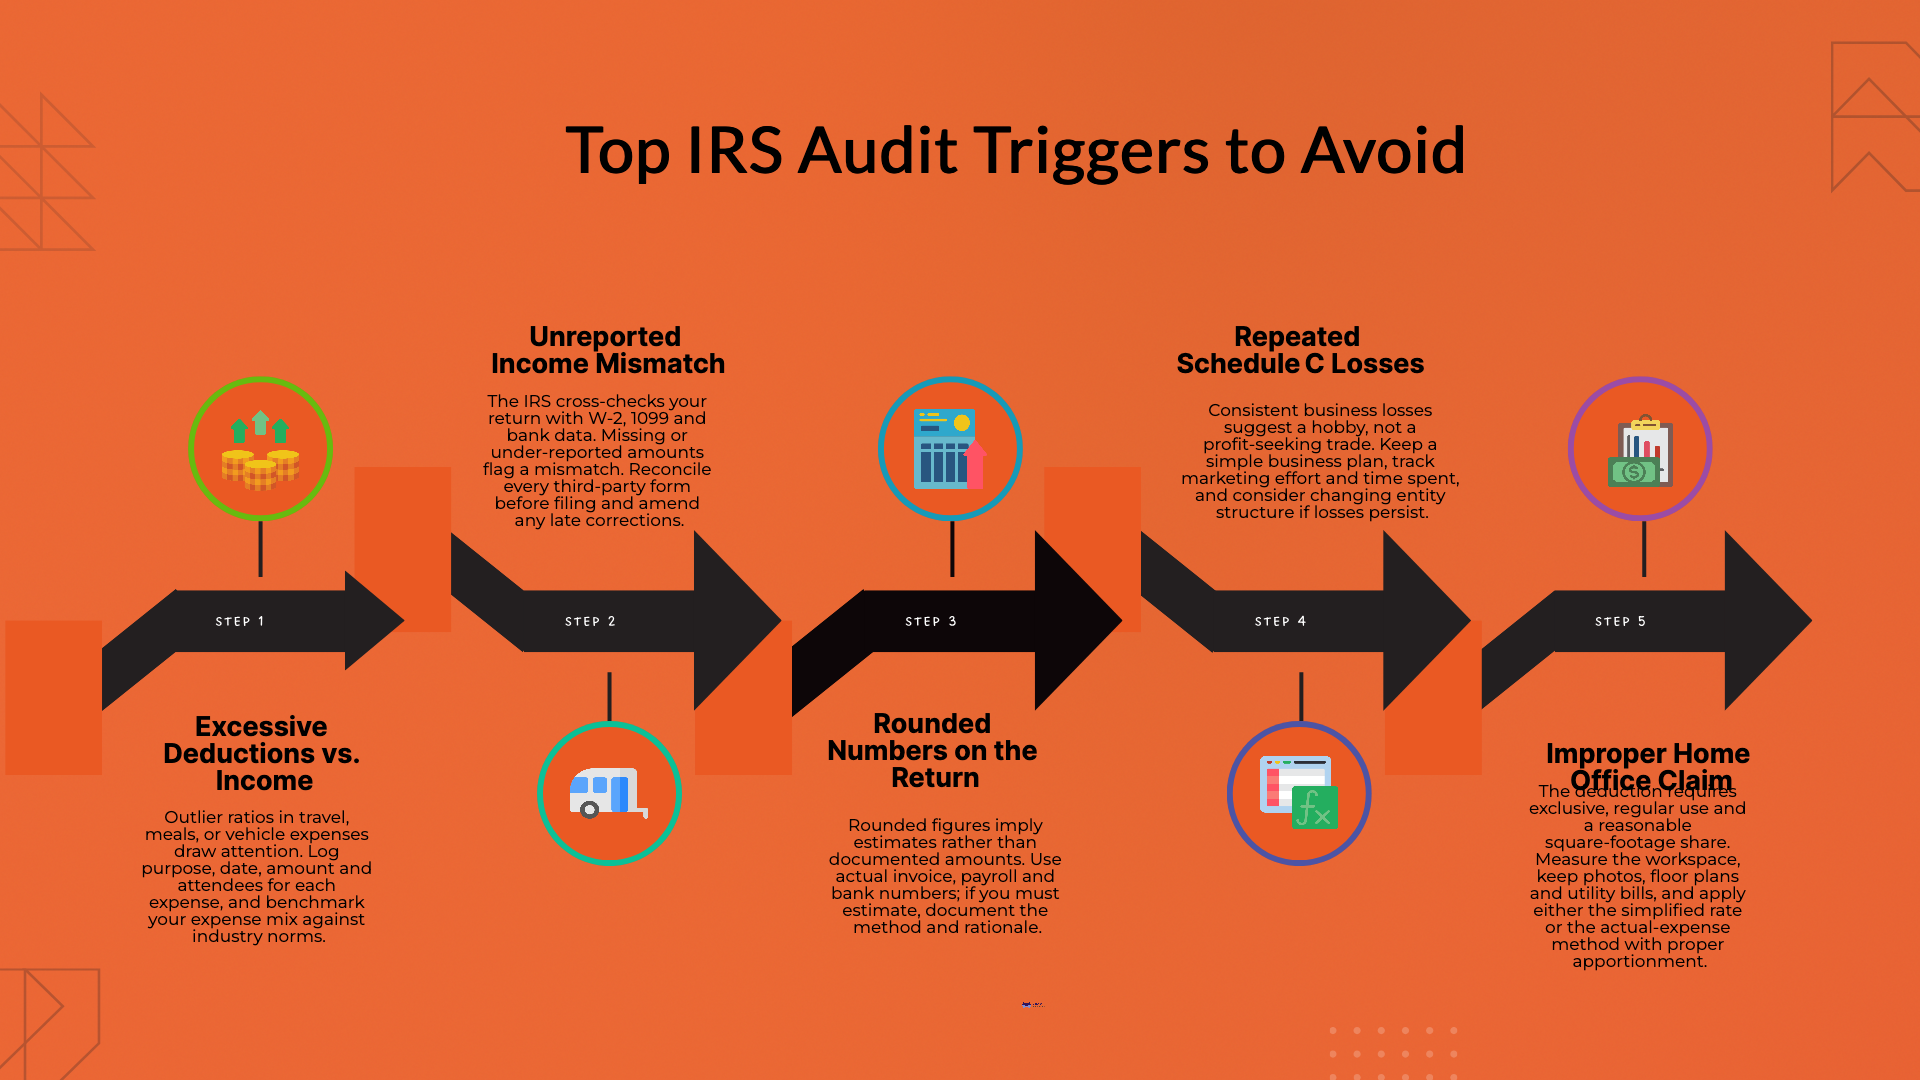

The most common IRS audit triggers are income that does not match the W-2s and 1099s third parties send the IRS, deductions that look large next to your income, repeated business losses, and items that are hard to verify, such as cash receipts, home offices, vehicles and crypto. Most of these flags are avoided by reconciling to information returns and keeping records made at the time of the expense.
This guide explains each of the 10 IRS audit triggers, what the IRS Data Book says about who actually gets examined, and the records that make a return look ordinary. All figures are as of October 2026.
The IRS describes two of its selection methods on its IRS audits page. Some returns are chosen by computer screening, where the agency says "We compare your tax return against 'norms' for similar returns." Others are picked because they involve transactions with another taxpayer who is already under review, such as a business partner or an investor. The same page notes that "Selection for an audit does not always suggest there's a problem" and that the IRS will notify you by mail and will not start an audit by telephone.
Separately, a large share of IRS contact never becomes a formal audit. The Automated Underreporter (AUR) program matches what you report against Forms W-2, 1099 and similar returns. According to the IRS Data Book information reporting table, the IRS received about 4.47 billion information returns in fiscal year 2025, and AUR closed 987,460 cases with about $5.9 billion in additional assessments. Because of that volume, a mismatch is one of the most predictable triggers.
Audit odds for most households are low, and they rise sharply at the very top and bottom of the income scale. The table below uses Tax Year 2019 returns from IRS Data Book Table 3-1, because that year is outside the normal three-year assessment window and its coverage figure is close to final. Coverage counts closed and open exams as of September 30, 2025.
| Total positive income (individual returns) | Share of TY 2019 returns examined |
|---|---|
| No total positive income | 5.6% |
| $1 under $25,000 | 0.4% |
| $25,000 under $200,000 (each band) | 0.2% |
| $200,000 under $500,000 | 0.3% |
| $500,000 under $1,000,000 | 0.8% |
| $1,000,000 under $5,000,000 | 1.8% |
| $5,000,000 under $10,000,000 | 3.4% |
| $10,000,000 or more | 11.5% |
| Returns claiming the earned income tax credit | 0.8% |
| All individual returns | 0.3% |
Recent tax years show lower percentages because exams are still being opened. For Tax Year 2023, the same table shows about 159,000 individual returns closed or in process out of 160.9 million filed, roughly 0.1%. Staffing also matters. The Treasury Inspector General for Tax Administration reported in its FY 2027 management challenges report that "the IRS started 30 percent fewer taxpayer examinations in FY 2025 compared to FY 2024."
This is one of the most common reasons for an IRS letter. If a payer files a 1099-NEC, 1099-K, 1099-INT, 1099-DIV, 1099-B or W-2 and the amount is missing or lower on your return, AUR flags it automatically. The usual result is a CP2000 notice proposing a change. The IRS sends it when third-party income or payment information does not match your return, and it states that the notice is not a bill. Our guide to reading and responding to a CP2000 notice covers the reply process.
How to lower the risk: collect every payer form before filing, reconcile 1099 totals to bank deposits and your ledger, and report income even when no form arrives. Payment app income needs extra care because Form 1099-K thresholds changed again under the One Big Beautiful Bill Act. The IRS now describes reporting by payment apps when payments exceed $20,000 in more than 200 transactions. Our page on 2026 1099 reporting thresholds sets out the current figures for each form.
A sole proprietor who reports losses year after year, especially while holding a well-paid W-2 job, invites the question of whether the activity is a business at all. Internal Revenue Code section 183 gives a presumption of profit motive when gross income exceeds deductions in 3 or more of 5 consecutive years (2 of 7 for horse activities). Losses outside that pattern are allowed, but you need evidence that you run the activity like a business.
How to lower the risk: keep a written business plan, a separate bank account, pricing records and a log of time spent. Change course when an approach keeps losing money and record why. Our article on hobby loss rules under section 183 explains the nine factors the IRS weighs.
Entries like $5,000 for supplies, $3,000 for travel and $2,000 for phone suggest estimates. A single rounded figure is harmless, but a return full of them looks like it was built without records, and estimates are hard to defend in an exam.
How to lower the risk: post actual amounts from invoices, statements and payroll reports. If a minor item truly has to be estimated, write down the method you used and keep it with the return.
Restaurants, salons, car washes, contractors and other trades that take cash have income with no matching 1099. Without third-party forms to match, the main test of reported income is how it compares with bank deposits and the owner's spending, so large gaps stand out.
How to lower the risk: deposit all receipts intact and reconcile daily point-of-sale totals to bank deposits each month. A business that receives more than $10,000 in cash in one transaction or in related transactions must file Form 8300 within 15 days. Our guide to Form 8300 and reporting cash payments over $10,000 covers what counts as cash and how to file.
A donation total far above the norm for your income band draws attention, as do noncash gifts of clothing, vehicles, art or property. The Form 8283 instructions state that you must file Form 8283 "if the amount of your deduction for each noncash contribution is more than $500," and that "A separate, qualified appraisal is required for any gift of property valued in excess of $5,000."
How to lower the risk: get a written acknowledgment for every gift of $250 or more, keep bank records for all cash gifts, and use a qualified appraiser where required. The rules also changed for 2026, including a new deduction of up to $1,000 ($2,000 for joint filers) for cash gifts by people who take the standard deduction. Our page on charitable giving in 2026 explains who qualifies.
The home office deduction requires that part of your home be used regularly and exclusively for business, and it is generally available only to self-employed people, since employees cannot deduct unreimbursed work expenses. A guest room that doubles as an office, or a large share of the home claimed as business space, fails the exclusive use test.
How to lower the risk: measure the space, keep photos and a floor plan, and keep utility and rent or mortgage records for the actual-expense method. The simplified method uses $5 per square foot up to 300 square feet, so the largest simplified deduction is 300 x $5 = $1,500.
Claiming that a car is used only for business is hard to support when the household has no other vehicle, and vehicle expenses carry strict written substantiation rules.
How to lower the risk: keep a mileage log made at the time of each trip, with date, destination, purpose and miles. The 2026 business standard mileage rate is 72.5 cents per mile from January 1 to June 30 and 76 cents per mile from July 1 to December 31. Our guide to IRS Publication 463 travel and car expense rules covers the logging requirements.
Worked example: a consultant drives 6,000 business miles in the first half of 2026 and 5,000 in the second half.
| Period | Business miles | Rate | Deduction |
|---|---|---|---|
| Jan 1 to Jun 30, 2026 | 6,000 | $0.725 | $4,350 |
| Jul 1 to Dec 31, 2026 | 5,000 | $0.76 | $3,800 |
| Total | 11,000 | $8,150 |
A log that shows the dates of each trip lets the consultant support the split between the two rates.
Digital asset activity is now matched like stock sales. The IRS digital assets page says reporting "is required to be made on Form 1099-DA beginning with transactions on or after Jan. 1, 2025," and "Brokers must report basis on certain transactions effected on or after Jan. 1, 2026." Every Form 1040 also asks whether you received, sold, exchanged or otherwise disposed of a digital asset during the year. A "No" answer next to a 1099-DA on file is an easy mismatch.
How to lower the risk: answer the digital asset question accurately, reconcile each 1099-DA to your own transaction history, and keep cost basis records for coins bought before 2026, since brokers may report proceeds without basis for those. Our article on Form 1099-DA and crypto tax reporting walks through the form box by box.
The Data Book table above shows that returns with $10 million or more of total positive income were examined at 11.5% for Tax Year 2019, and returns with no total positive income at 5.6%, against 0.3% for all individual returns. Refundable credit claims such as the earned income tax credit also see higher coverage than middle-income returns.
How to lower the risk: income level itself cannot be changed, so the focus is on documentation. High earners should expect questions on partnership items, large capital transactions and foreign holdings, and should keep the supporting schedules ready.
Foreign accounts carry separate reporting. A U.S. person must file an FBAR with FinCEN when the aggregate value of foreign financial accounts exceeded $10,000 at any time during the year, and Form 8938 may also apply at higher thresholds. Foreign interest and dividends often reach the IRS through international information exchange, so omissions surface.
How to lower the risk: list every foreign account with its maximum balance, report the income on your return, and file the FBAR and Form 8938 when required.
Most letters ask for specific documents about one or two items. Read the notice, note the response date and gather the records for only the items listed. Our step-by-step guide on how to prepare for a tax audit covers audit types, Form 4564 document requests and representation. For the question of which years can still be opened, see our explainer on how far back the IRS can audit you.
A tax exam by the IRS is a different process from a financial statement audit performed by a CPA firm for lenders or investors. If your business is preparing for that second kind of audit, our list of common audit issues for small businesses covers cutoff, reconciliation and disclosure problems.
The steps below address several IRS audit triggers at once.
What is the most common IRS audit trigger? In practice, it is income that does not match the W-2s and 1099s filed by employers, banks, brokers and payment apps. The IRS matches these automatically through its Automated Underreporter program, which closed 987,460 cases in fiscal year 2025.
Does a CP2000 count as an audit? A CP2000 is a proposed adjustment from automated matching, and the IRS states that it is not a bill. A reply is still due by the date on the notice, and the CP2000 guide linked above covers how to respond.
What percentage of tax returns get audited? About 0.3% of individual returns filed for Tax Year 2019 had been examined as of September 30, 2025, according to IRS Data Book Table 3-1. Rates are much higher for returns with $10 million or more of income and for returns with no positive income.
Does claiming a home office trigger an audit? A home office claim draws questions mainly when the space is not used regularly and exclusively for business. Measurements, photos and expense records make the claim easy to support.
Can the IRS see my crypto transactions? Yes, for transactions through brokers. Brokers report gross proceeds on Form 1099-DA for transactions on or after January 1, 2025, and report basis on certain transactions from January 1, 2026.
Madras Accountancy provides bookkeeping, monthly reconciliation and tax preparation support for US businesses and CPA firms, which helps keep returns tied to information returns and supported by records. To discuss your books or an upcoming filing, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



