



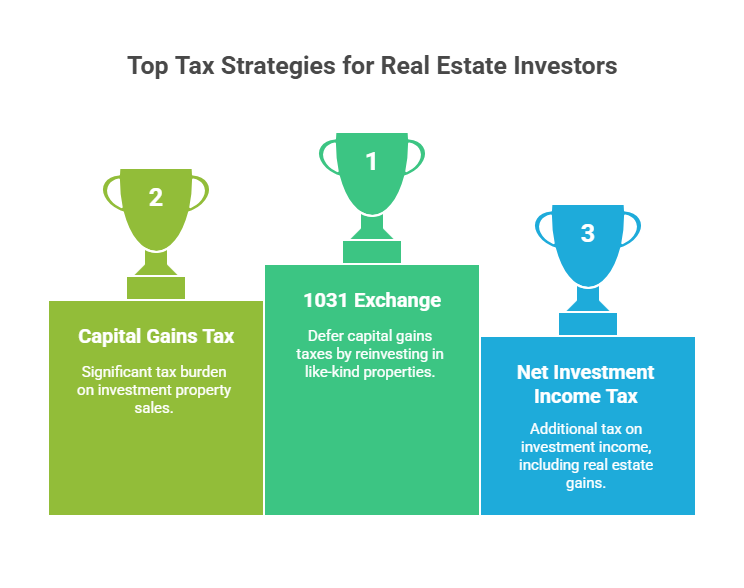
A 1031 exchange lets you defer capital gains tax when you sell investment or business real estate and reinvest in other real property. Since 2018 it applies to real property only. You must identify replacement property within 45 days of the sale and acquire it within 180 days (or by your return's due date, if earlier), using a qualified intermediary.
Selling an investment property at a profit can trigger federal capital gains tax of up to 20%, tax of up to 25% on gain from prior depreciation, the 3.8% net investment income tax for higher earners, and state tax. For many investors that is a large share of the gain.
A 1031 exchange, also called a like-kind exchange, defers that tax by rolling the proceeds into replacement real property. Named after Section 1031 of the Internal Revenue Code, it lets investors defer gain from one property to the next and keep more capital invested.
In this guide, you'll learn how a 1031 exchange works, the deadlines you must meet, common pitfalls and how to plan an exchange that complies with IRS rules.
A 1031 exchange is a tax-deferred transaction in which you dispose of real property held for investment or for use in a business and acquire replacement real property of like kind. The exchange must follow the timing and structure rules in Section 1031 and its regulations, and you report it on Form 8824.
Before 2018, Section 1031 applied to both real and personal property. Under the Tax Cuts and Jobs Act, Section 1031 now applies only to exchanges of real property. You can no longer exchange equipment, vehicles, artwork or other personal property under Section 1031. The One Big Beautiful Bill Act of 2025 did not change these rules.
The IRS says properties are like-kind if they are of the same nature or character, even if they differ in grade or quality. In practice, most U.S. real estate held for investment or business use is like-kind to other U.S. real estate held for those purposes, whether improved or unimproved.
Your primary residence does not qualify, and neither does property held primarily for sale, such as homes a developer or flipper builds or buys to resell.
A deferred 1031 exchange follows set steps and deadlines. Here's the process:
You cannot sell your property, take the cash and then buy another property. In a typical deferred exchange, a qualified intermediary (also called an exchange accommodator) holds the sale proceeds and uses them to acquire the replacement property for you.
This is critical: if you take actual or constructive receipt of the sale proceeds during the exchange, the deferral is lost and the gain becomes taxable.
Two deadlines run at the same time, both starting on the day you transfer the relinquished property:
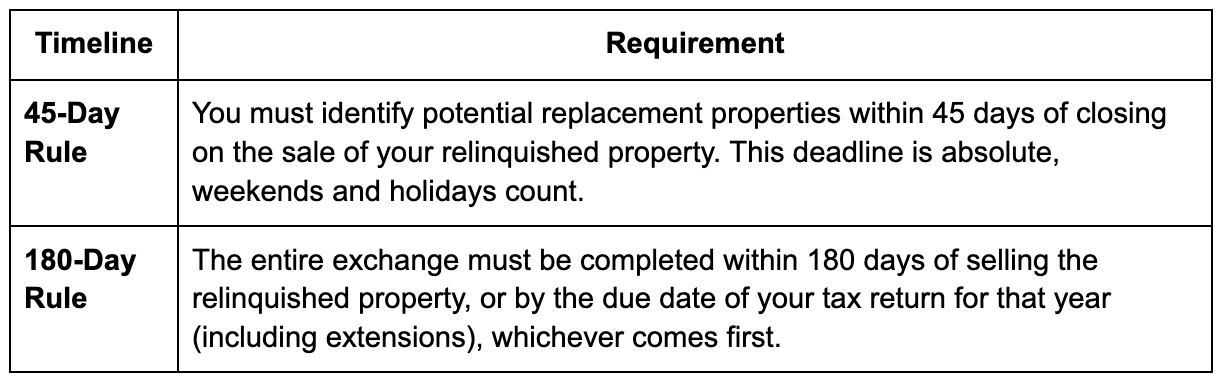
Identification Rules
There are three rules for identifying replacement properties within 45 days:
Three-property rule: identify up to three properties, regardless of their value.
200% rule: identify any number of properties as long as their combined fair market value doesn't exceed 200% of the relinquished property's value.
95% rule: identify any number of properties of any value, but you must acquire at least 95% of the total value identified.
A 1031 exchange offers several advantages for investors building and preserving wealth:
Deferring tax keeps more capital working for you. Example: you sell a property with a $500,000 gain. If all of it were taxed at the 20% top capital gains rate plus the 3.8% net investment income tax, you'd owe about $119,000 in federal tax, and more if part of the gain comes from depreciation taxed at up to 25%, or if your state taxes it. With a 1031 exchange, that money stays invested in your next property.
For 2026, the 20% rate applies to long-term gains above $545,500 of taxable income for single filers and $613,700 for married couples filing jointly, and the 3.8% net investment income tax applies above $200,000 of modified AGI for single filers and $250,000 for joint filers. Over multiple transactions, deferral compounds. See our tax planning strategies for small businesses.
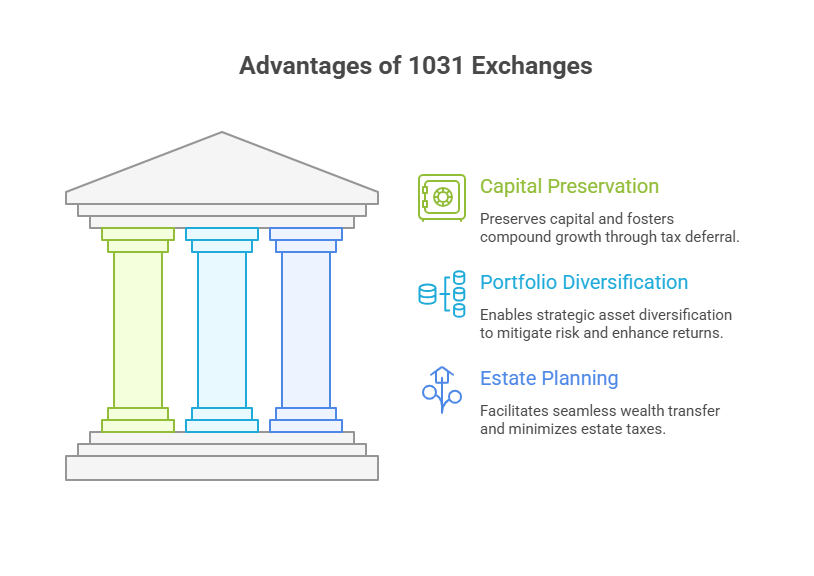
A 1031 exchange lets you reposition your real estate portfolio without current tax. You might consolidate several smaller properties into one larger one for easier management, or split one property into several across different markets.
Under current law, heirs generally receive a step-up in basis to fair market value at your death. That means gain you deferred through 1031 exchanges is generally never taxed if you hold the property until death. Combined with fractional CFO services for long-term planning, this can be a powerful wealth transfer strategy.
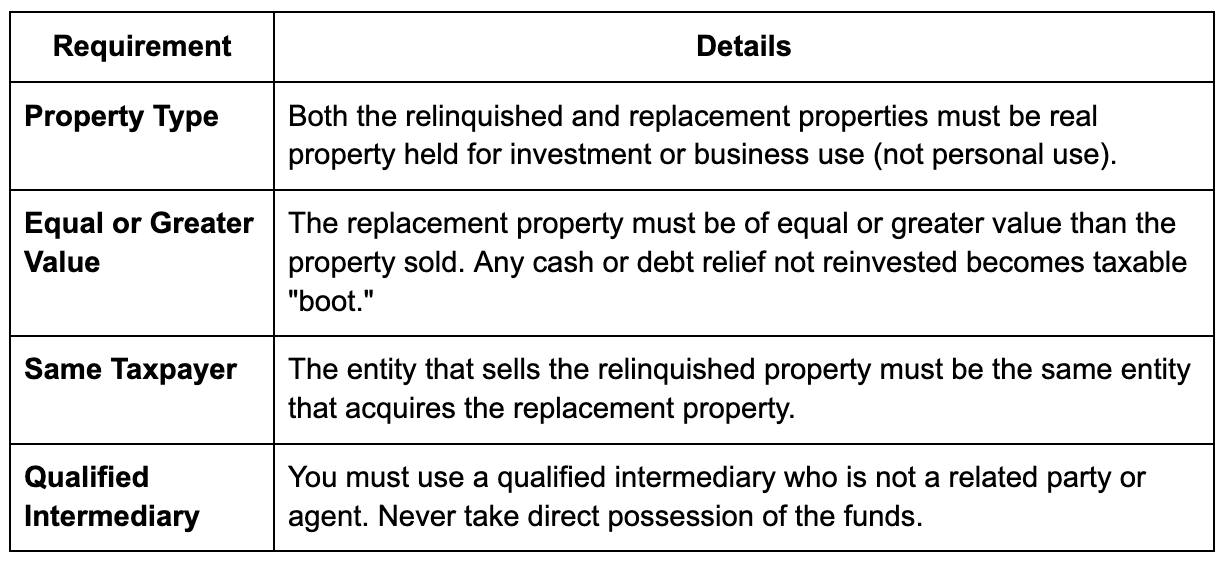
To qualify for a 1031 exchange, you must meet these requirements:
Even experienced investors make costly errors. Here are the most common pitfalls:
The 45-day and 180-day deadlines are calendar days and are not extended because the last day falls on a weekend or holiday. The only extensions come from IRS disaster relief for taxpayers in federally declared disaster areas. Start looking for replacement properties before you close the sale.
"Boot" is cash or other non-like-kind property you receive, including net debt relief. Gain is taxable up to the amount of boot. To defer all gain, buy replacement property of equal or greater value and reinvest all net proceeds. For example, if you sell for $1 million and buy for $900,000, about $100,000 of gain is generally taxable. If your new mortgage is smaller than the one paid off, you can offset that by adding cash.
If you buy replacement property intending to use it personally or convert it to your home soon after the exchange, the IRS may disallow the deferral. The replacement must be held for investment or business use. There is no fixed statutory holding period, but many advisors suggest holding for at least one to two years to show investment intent. Separate rules apply to vacation homes and to converting a replacement property into a residence later.
Your qualified intermediary cannot be a "disqualified person," such as someone who has acted as your agent within the past two years (for example, your real estate agent, attorney, accountant or investment banker, apart from routine services) or a related party. Choose an independent, experienced intermediary with proper bonding and insurance.
Exchanges with related parties are allowed, but if either party disposes of the exchanged property within two years, the deferral is generally lost.
When you exchange depreciable real property, the replacement property takes a carryover basis, so the depreciation you claimed carries over and recapture is deferred, not eliminated. If a cost segregation study identified personal property (such as appliances or equipment), that portion isn't real property and can trigger recapture in the exchange. See our guide to Section 179 and bonus depreciation.
No. A 1031 exchange is only available for property held for investment or business use. You may be able to use the Section 121 exclusion instead, which excludes up to $250,000 of gain ($500,000 for married couples filing jointly) on the sale of your main home if you owned and lived in it for at least two of the last five years.
The exchange fails and the sale is taxed as a regular sale. Apart from IRS disaster relief, there are no extensions. Plan ahead and work with an experienced qualified intermediary.
Yes. You can exchange one property for several replacement properties, or several for one. To defer all gain, the combined value of the replacement properties must be at least equal to what you sold, all net proceeds must be reinvested, and you must follow the identification rules.
For a typical deferred exchange, yes. You cannot take possession of the sale proceeds, and a qualified intermediary is the standard way to hold them and complete the exchange. Choose one with experience, proper insurance and a solid track record.
No. Real property in the United States is not like-kind to real property outside the United States. If you're considering international real estate, talk to a tax professional about other options.
Most U.S. real estate held for investment or business use is like-kind to other such real estate. You can exchange residential rentals for commercial buildings, raw land for apartment complexes, or office buildings for warehouses.
There's no limit. Many investors exchange repeatedly over their careers, deferring gain each time while growing their portfolio.
In a reverse exchange you acquire the replacement property before selling the relinquished property. An exchange accommodation titleholder (EAT) temporarily holds title to one of the properties while you complete the exchange, generally within the same 45- and 180-day framework. Reverse exchanges are more complex and expensive but useful in competitive markets.
A 1031 exchange is one of the most effective tax-deferral tools available to real estate investors. By reinvesting proceeds from one investment property into other like-kind real property, you can defer capital gains tax, keep more capital invested and build a larger portfolio over time.
The key is planning, strict adherence to the 45- and 180-day deadlines and working with experienced professionals. Start identifying replacement properties early, choose a reputable qualified intermediary, and buy replacement property of equal or greater value with all net proceeds to avoid taxable boot.
At Madras Accountancy, we've helped real estate investors with 1031 exchanges since 2015. Our team provides tax planning and Form 8824 preparation to keep your exchange compliant. Contact us to discuss how a 1031 exchange fits your investment strategy.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



