



For calendar-year C corporations, Form 1120 for tax year 2026 is due Thursday, April 15, 2027. Filing Form 7004 extends the deadline six months to Friday, October 15, 2027. Fiscal-year corporations file by the 15th day of the 4th month after year end. An extension to file is not an extension to pay.
Every year, corporations miss this deadline and pick up penalties and interest. The most common mistakes are assuming the date is the same for every corporation, and assuming an extension also delays payment.
This guide covers the 2027 filing season (tax year 2026 returns):
Form 1120, the U.S. Corporation Income Tax Return, is the annual federal income tax return for C corporations. It reports the corporation's income, deductions and credits and calculates its federal income tax.
Not every business files it, so it is worth confirming which return applies to you.
You generally must file Form 1120 if your business is:
This includes corporations in every industry, from tech startups to holding companies. Form 1120 is a tax return, not an information return: it calculates the tax the corporation owes.
Important: Corporations that have elected S corporation status file Form 1120-S. Partnerships and most multi-member LLCs file Form 1065. Sole proprietors report business income on Schedule C with Form 1040. Foreign corporations with U.S. income generally file Form 1120-F instead of Form 1120.
Form 1120 gives the IRS a full financial picture of the corporation for the tax year, including:
The form also asks for:
Why it matters: The IRS uses Form 1120 to check whether your corporation has reported its income correctly and paid the right tax. It is also the starting point in an audit.
Filing late or filing an incomplete return can lead to:
Check the current Form 1120 instructions for the exact penalty rates and minimum amounts. Even with no revenue, a C corporation must still file.
Deadlines matter for more than penalties. They drive cash flow planning, estimated payments and year-end reporting. Here is when Form 1120 is due for tax year 2026 returns, filed in 2027.
For C corporations whose tax year ends December 31, 2026:
If your corporation uses a fiscal year, Form 1120 is due on the 15th day of the 4th month after the end of its tax year.
June 30 year-ends: Corporations with a June 30 year end used to file by the 15th day of the 3rd month (September 15). That exception covers only tax years that began before January 1, 2026, so the year ended June 30, 2026 was still due September 15, 2026. From the tax year beginning July 1, 2026, June 30 year-ends follow the normal 4th-month rule.
Examples:
If a due date falls on a weekend or legal holiday, it moves to the next business day.
Need more time? File Form 7004 by the original due date to get an automatic extension of time to file. For tax years beginning in 2026, the automatic extension is six months.
Important: An extension to file is not an extension to pay. Any tax owed is still due by the original due date (April 15, 2027 for calendar-year corporations). Tax paid after that date is charged interest and may face a late-payment penalty. Corporations use Form 7004 for the extension; Form 4868 is for individuals and does not apply.
Pass-through entities file a month earlier than C corporations:
These dates apply to calendar-year returns for tax year 2026.
Filing Form 1120 is a legal obligation that affects your penalties, compliance record and audit risk. Here is how to prepare and file it accurately.
Close your books for the tax year before starting the return. You will need:
Tip: Even with no profit, the corporation must file. A tax professional can help make sure the return is complete and accurate.
Form 1120 and its instructions are on the IRS website. Make sure you use the version for tax year 2026. Many corporations use professional software or a preparer instead of filling in the PDF.
Common options include:
Software handles the calculations and e-filing, but you still need to understand your numbers.
The main parts of the return:
Page 1: Income, deductions and tax
Schedule C: Dividends, inclusions and special deductions
Schedule J: Tax computation and payments
Schedule K: Other information
Schedule L: Balance sheet
Schedule M-1: Book-to-tax income reconciliation
Schedule M-2: Retained earnings
Smaller corporations may be able to skip Schedules L, M-1 and M-2; check the Schedule K question on total receipts and total assets in the Form 1120 instructions.
Mistakes in these schedules can delay processing or prompt IRS questions.
Electronically (e-file): The fastest option and the one most software uses. Many corporations are required to e-file.
By mail: If paper filing is allowed for you, use the address in the IRS "Where to File" guidance for Form 1120.
Deadline: For calendar-year corporations, Form 1120 for tax year 2026 is due April 15, 2027 (October 15, 2027 with an extension).
Even with an extension to file, pay the tax by April 15, 2027 to avoid late-payment penalties and interest. Corporations that expect to owe tax generally also make quarterly estimated payments during the year.
Payment options include:
Corporations generally must deposit federal tax electronically. Check the IRS payment guidance for current options.
Tip: If cash is tight, ask about an IRS payment plan, but file on time and don't ignore the balance.
The IRS can review a Form 1120 for several years after it is filed, and longer if income is substantially understated or fraud is involved. Check the IRS recordkeeping guidance for how long to keep each type of record.
Keep:
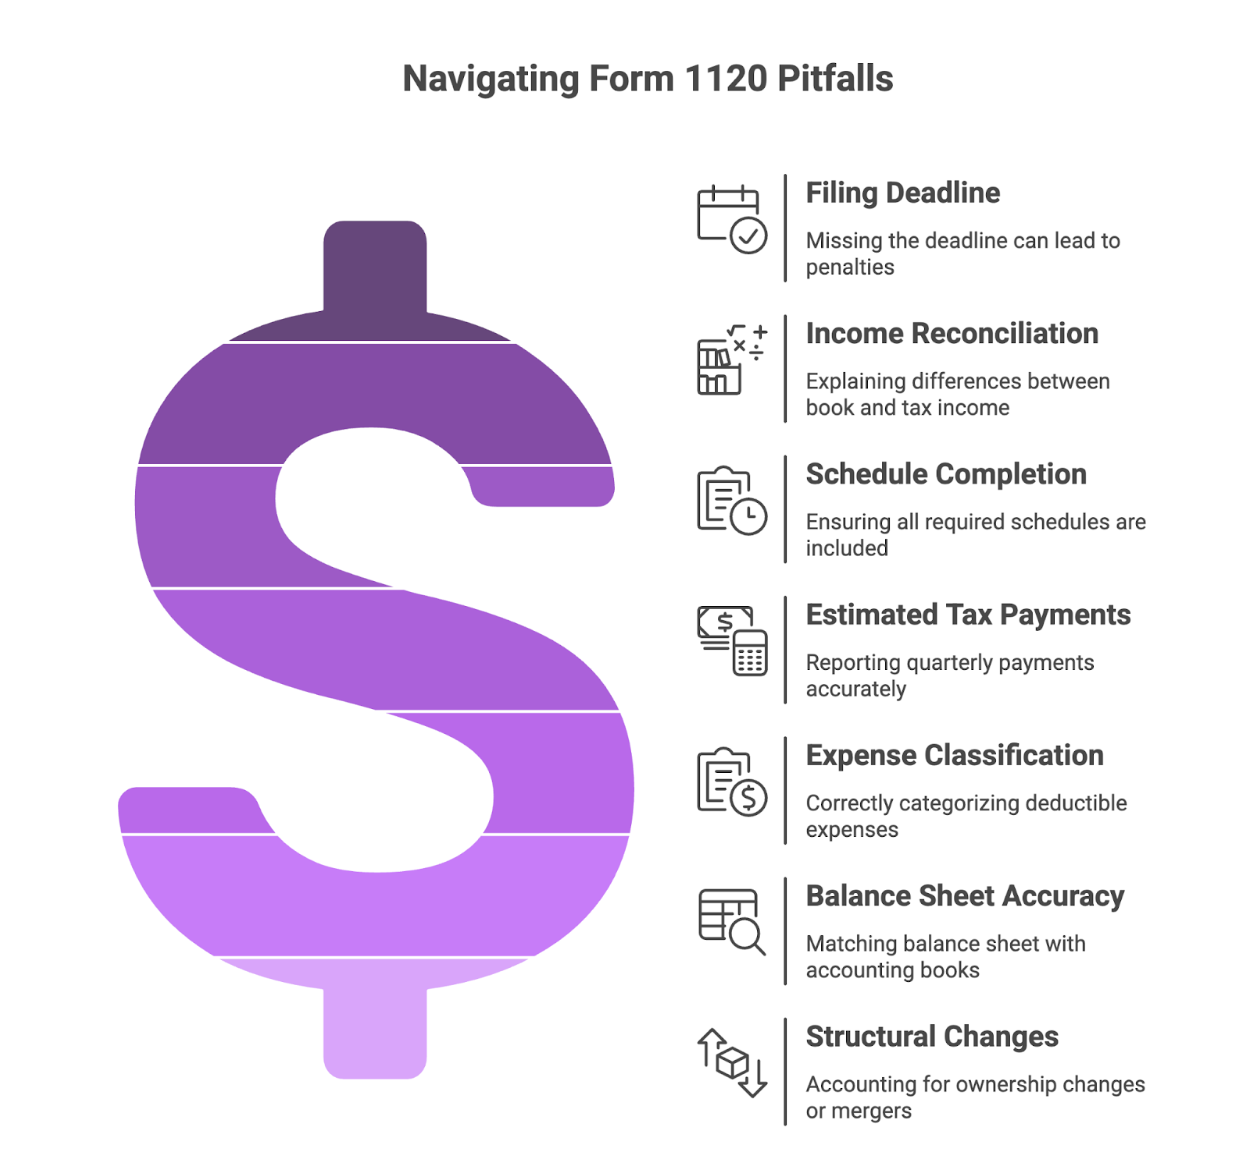
Form 1120 is where many corporations slip up. These are the most common mistakes and how to avoid them.
C corporations must file by the 15th day of the 4th month after year end (April 15, 2027 for calendar-year 2026 returns). Missing the deadline triggers a failure-to-file penalty on any unpaid tax.
Why it happens: Founders confuse the corporate deadline with the S corporation or partnership deadline, or assume an extension also gives more time to pay.
How to avoid it:
Your books and your tax return rarely match exactly. Schedule M-1 (or M-3) explains the differences.
Why it matters: Unexplained differences between book and tax income can lead to IRS questions.
Best practice:
Form 1120 is rarely filed alone. You may also need:
Mistake to avoid: Filing without required schedules or leaving key sections blank.
Tip: Use the current Form 1120 instructions as a checklist before you file.
If your corporation made estimated payments during the year, report them correctly on Schedule J.
Why it matters: If payments are missing, the IRS may bill you for tax you have already paid.
Best practice: Keep a log of each payment with its date and amount, and reconcile it with IRS records before filing.
Not every business expense is fully deductible.
Common problem areas:
Solution: Review expense categories with your tax professional against current IRS guidance so you claim what you are entitled to and nothing more.
If your corporation must complete Schedule L, the balance sheet has to match your books.
Watch out for:
Fix it by: Running a final trial balance and reviewing it with your preparer before filing.
If the corporation added shareholders, merged or shut down, you may need extra disclosures or forms, such as Form 966 for a dissolution.
Overlooking this can lead to:
Solution: Work with a tax professional who understands corporate transactions.
Form 1120 covers federal income tax only. Most states also require a corporate income or franchise tax return, and some states use different due dates or extension rules. Coordinate your federal and state filings so nothing is missed.
If your corporation had a short tax year because it was formed, dissolved or changed its accounting period, the due date is still based on the end of that short year. Form 7004 is used for extensions in these cases too.
Corporations also file other returns during the year:
These have their own deadlines, separate from Form 1120.
Corporations may also need to file information returns, such as:
For tax year 2026, calendar-year C corporations must file Form 1120 by April 15, 2027, or by October 15, 2027 with Form 7004. Fiscal-year corporations file by the 15th day of the 4th month after year end; for tax years beginning in 2026 this includes June 30 year-ends. In every case, the tax is due by the original date.
Knowing your deadline, extending on time and paying what you owe by the original due date will keep your corporation clear of avoidable penalties.
You don't have to do it alone. An experienced tax professional can make sure your return is filed correctly and on time.
Madras Accountancy helps U.S. businesses file accurately, stay compliant and plan ahead, with experience in corporate returns, tax planning and financial advisory.
Need help with your 1120 return or tax planning? Explore our services at MadrasAccountancy.com.
For CPA firms: Madras Accountancy supports U.S. CPA firms with tax preparation and planning, including seasonal capacity for busy season. See our tax preparation and planning services.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



