


AB5 (Assembly Bill 5) is the California law that presumes anyone you pay for services is an employee. To treat a worker as an independent contractor, the hiring business has to prove all three parts of the ABC test, or show the worker falls into one of the statutory exemptions. Get it wrong and the exposure runs through wage claims, Employment Development Department (EDD) payroll tax assessments and willful misclassification penalties.
The rules below reflect the law as it stands in October 2026, including the 2020 rewrite by AB 2257 that moved the exemptions into Labor Code sections 2775 to 2787. If you are still working from a 2020 summary of AB5, several of the details it gives you (the 35-submission cap for freelance writers, for example) are out of date.
In 2018 the California Supreme Court decided Dynamex Operations West v. Superior Court and adopted the ABC test for wage order claims. AB5 was signed in September 2019 and took effect January 1, 2020, extending that test to the Labor Code, the Unemployment Insurance Code and workers' compensation. According to the Department of Industrial Relations independent contractor FAQ, the ABC test applied to workers' compensation from July 1, 2020.
AB 2257, signed in September 2020, repealed the original exemption language and replaced it with the current Labor Code article. Most of what people call "AB5" today is really AB5 as amended by AB 2257.
AB5 is a state law. For federal payroll tax, the IRS still uses the common-law control test, so a worker can be an employee for California purposes and arguably a contractor for federal purposes. In practice, once California says employee, most businesses put the worker on a W-2 for both. Our article on classifying 1099 contractors versus W-2 employees compares the federal and state tests side by side.
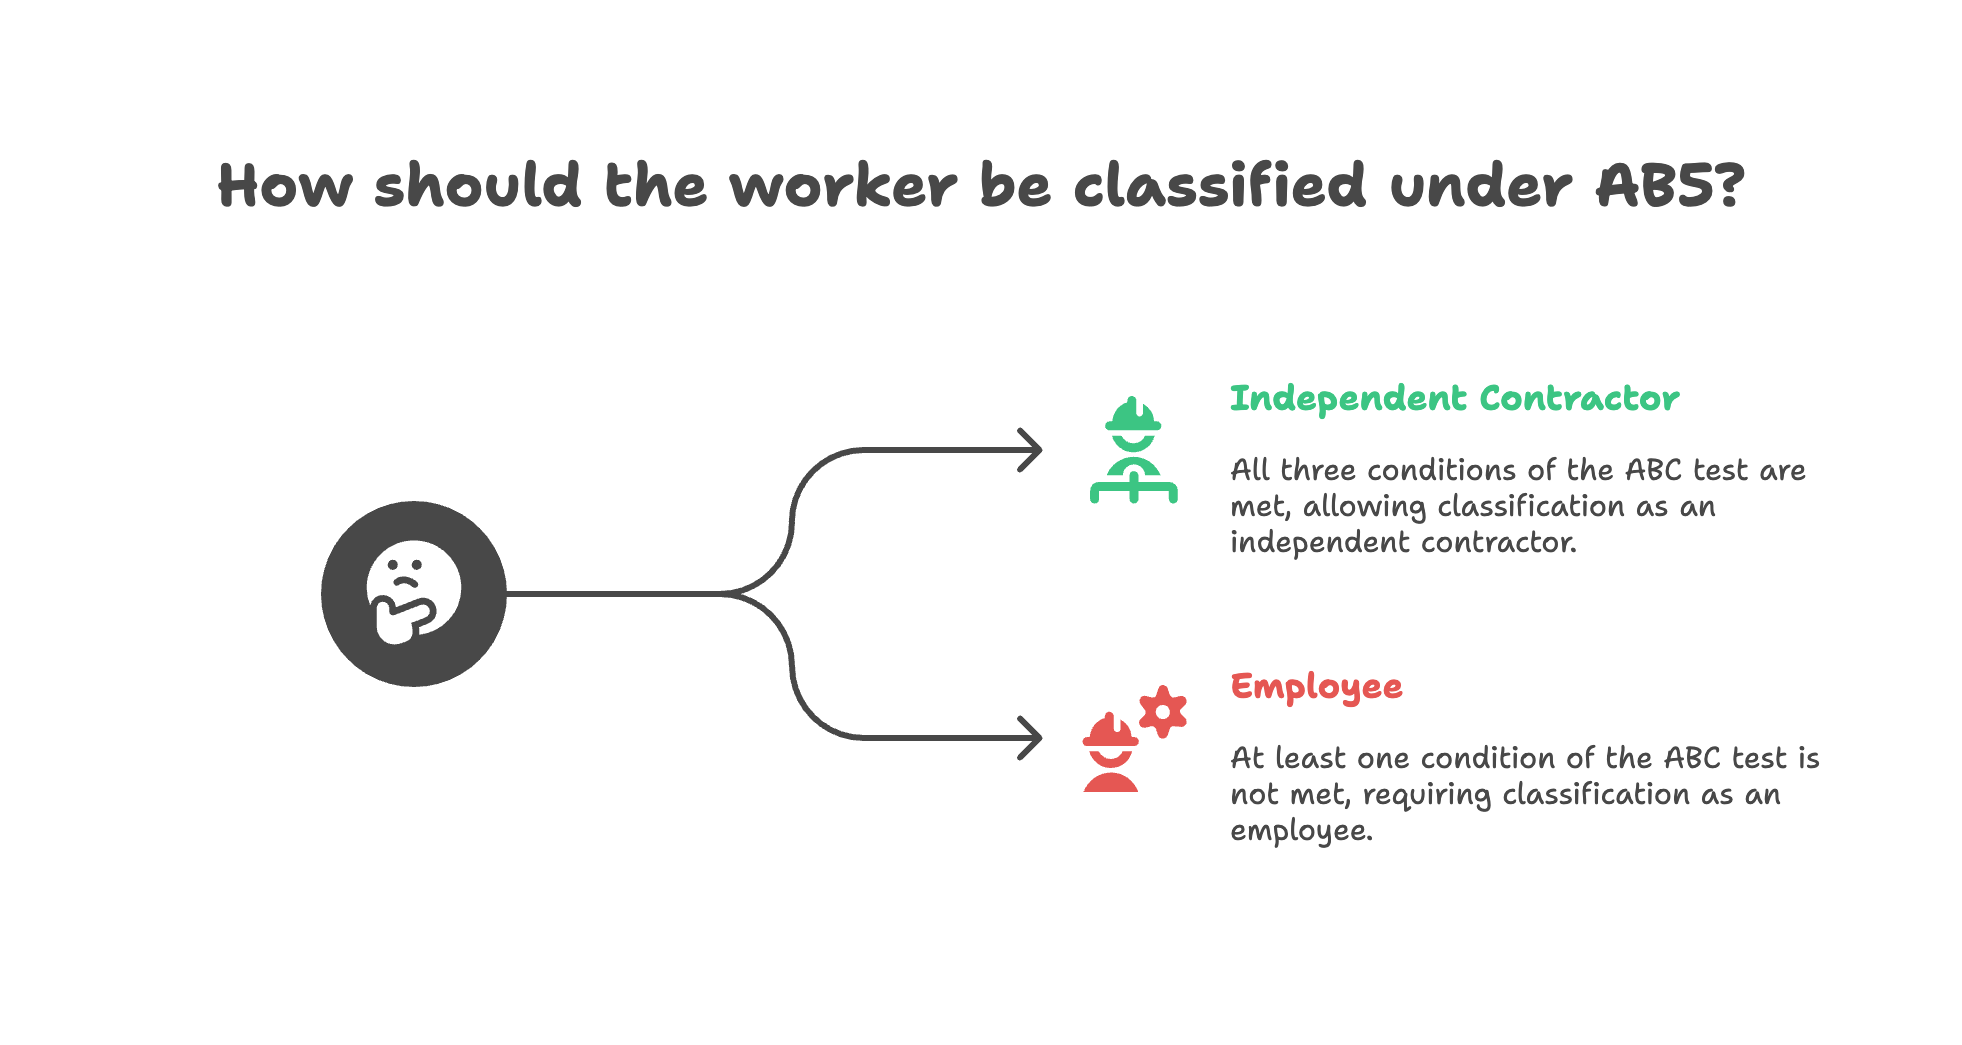
The California Labor and Workforce Development Agency's ABC test page states the rule plainly: a worker is an employee unless the hiring entity satisfies all three prongs. Failing one is enough.
| Prong | What the business must prove | Where it usually fails |
|---|---|---|
| A: Control | The worker is free from your control and direction, both under the contract and in fact | You set hours, require your tools or templates, or review the work step by step |
| B: Usual course of business | The work is outside the usual course of your business | A marketing agency paying a freelance copywriter to write client campaigns |
| C: Independent trade | The worker is customarily engaged in an independently established trade or business of the same nature | The person has one client (you), no business entity, no marketing of their own |
Prong B trips up the most businesses because no contract wording can fix it. A bakery paying an electrician to rewire the kitchen passes B. A bakery paying a "contract" cake decorator who works the same shifts as staff does not, and that decorator is an employee regardless of the 1099.
Prong C asks whether the worker has a real business: other clients, a business license or entity, their own insurance, a website or listing. A former employee who comes back the next Monday on a 1099 to do the same job almost always fails C as well as B.
Exempt relationships are not automatically contractor relationships. For most exemptions, the business falls back to the older Borello multifactor test, which weighs control alongside factors such as who supplies tools, how the worker is paid, and whether the work is a distinct occupation. The DIR FAQ groups the exemptions roughly as follows.
Licensed professions. Certain licensed physicians, surgeons, dentists, podiatrists, psychologists and veterinarians, plus licensed attorneys, architects, engineers, private investigators and accountants. Insurance agents and direct salespersons are also covered.
Professional services contracts. Marketing, human resources administration, travel agent services, graphic design, grant writing, fine artists, freelance writers, editors, photographers and similar roles. These require extra conditions first: the provider maintains a business location, negotiates its own rates, sets its own hours, holds any required license, and customarily works for other clients. AB 2257 removed the old cap of 35 submissions per year for writers and photographers.
Business-to-business (B2B). A sole proprietor or business entity contracting with your business can be tested under Borello if a long list of conditions is met, including a written contract specifying payment, a separate business location, the provider's ability to set its own hours, and the provider actually serving other clients. The DIR lists every condition, and missing one sends you back to the ABC test.
Referral agencies. Platforms that connect clients with providers such as tutors, dog walkers or handymen, if the agency does not control the work and the provider meets the business conditions.
Construction subcontractors. Certain subcontractors with a written contract, a contractor's license where required, and their own business location. Labor Code section 2750.5 also applies to licensing questions in construction.
App-based drivers. Proposition 22 (2020) created a separate rule for rideshare and delivery drivers. The California Supreme Court upheld it in Castellanos v. State of California on July 25, 2024.
Trucking is the notable non-exemption. After the U.S. Supreme Court declined to hear California Trucking Association v. Bonta in 2022, AB5 applies to owner-operators, and motor carriers generally have to rely on the B2B exemption.
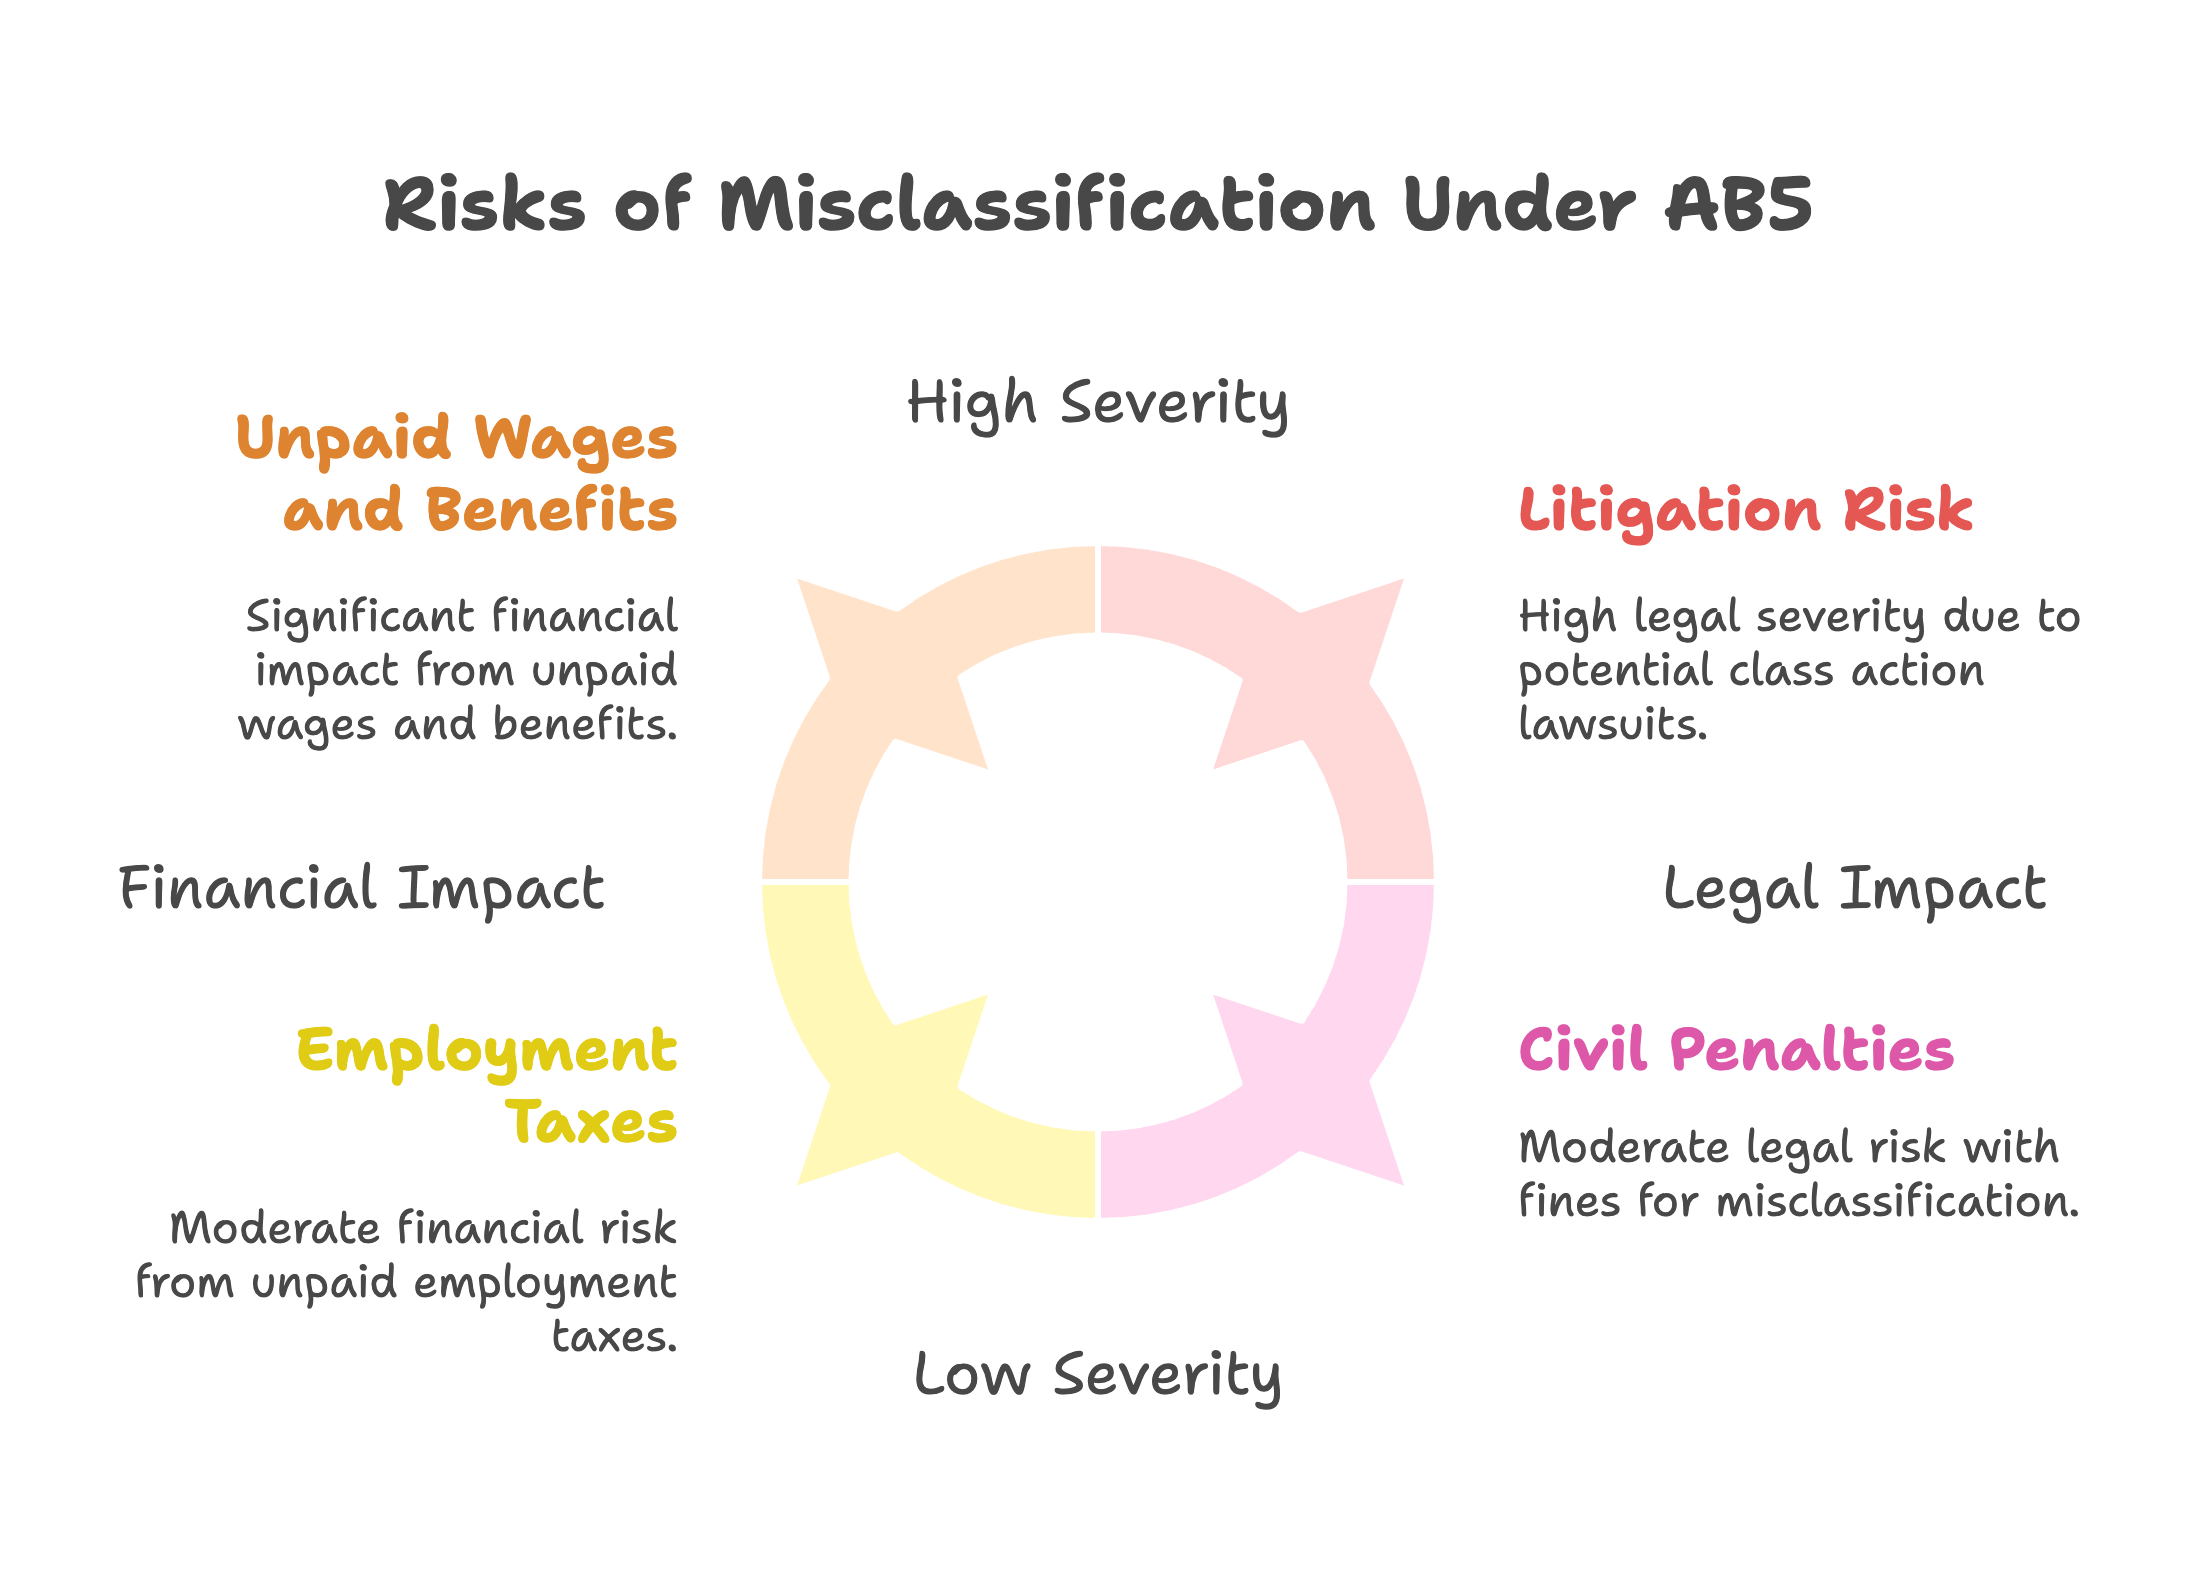
Exposure comes from several directions, and each agency works on its own timeline.
The penalties stack. A single misclassified worker can produce a wage claim, an EDD audit of the whole contractor list and, if the IRS follows, federal employment tax adjustments.
Reclassification moves real money onto the employer side of the ledger. Here is the arithmetic for one worker paid $60,000 a year in California, using 2026 rates. Workers' compensation is excluded because premiums depend on the class code and carrier.
| Item (2026) | Rate and base | Employer cost |
|---|---|---|
| Social Security (employer share) | 6.2% of $60,000 | $3,720 |
| Medicare (employer share) | 1.45% of $60,000 | $870 |
| FUTA (after full state credit) | 0.6% of first $7,000 | $42 |
| California UI (new employer rate) | 3.4% of first $7,000 | $238 |
| California ETT | 0.1% of first $7,000 | $7 |
| Total employer payroll tax | $4,877 |
The California figures come from the EDD's rates and withholding page: a $7,000 UI taxable wage limit, a 3.4 percent rate for new employers for two to three years, an ETT rate of 0.1 percent, and an SDI withholding rate of 1.3 percent for 2026 with no wage ceiling. SDI is withheld from the employee, so on $60,000 the worker's paycheck shows $780 of SDI. It is not an employer expense.
That $4,877 is roughly 8 percent on top of the contract rate, before workers' compensation and any benefits you choose to offer. If California is on the year's FUTA credit reduction list, the federal unemployment line rises; our explainer on the FUTA credit reduction shows how to recompute it.
Once the worker is on payroll, the filings follow: federal deposits and the quarterly Form 941, the annual Form 940 for federal unemployment tax, California's quarterly DE 9 and DE 9C, a DE 4 withholding certificate from the employee, a DE 34 new hire report within 20 days, and a W-2 at year end.
Workers who pass the ABC test (or an exemption) still create reporting duties. California requires a DE 542 within 20 calendar days if you pay an independent contractor $600 or more in a calendar year or sign a contract for $600 or more, per the EDD independent contractor reporting page.
The federal threshold moved. Under the One Big Beautiful Bill Act, the Form 1099-NEC and 1099-MISC reporting threshold rose to $2,000 for payments made after December 31, 2025. The two thresholds now differ, so a $1,500 California contractor needs a DE 542 but no 1099-NEC. See our breakdown of the new 2026 1099 reporting threshold and the 1099-NEC and 1099-MISC filing requirements for the federal side.
1. Build the contractor list from the general ledger. Pull every vendor paid for personal services in the last three years, not only the people HR thinks of as contractors. Recurring monthly payments to individuals are the first place to look.
2. Test each relationship and write it down. For each worker, record how they satisfy prongs A, B and C, or which exemption applies and how each condition is met. The file should describe the actual working relationship, since agencies look at practice over paper.
3. Fix contracts and evidence. For workers who pass, collect business licenses, certificates of insurance, entity documents and evidence of other clients. Remove contract language that sets hours or requires daily check-ins.
4. Reclassify the ones that fail. Pick a clean start date, usually the first day of a quarter. Register or update your EDD account, add the worker to workers' compensation and run them through onboarding like any new hire. For the federal side, the IRS Voluntary Classification Settlement Program lets eligible businesses pay 10 percent of one year's employment tax liability, computed at reduced section 3509 rates, with no interest or penalties. File Form 8952 at least 120 days before the start date. VCSP does not bind the EDD.
5. Put a gate on new engagements. Require finance sign-off before anyone is paid on a 1099, and repeat the review every year or when a contractor's role changes. Our payroll compliance checklist covers the recurring deadlines that follow.
If the work is core to your business, accept that it belongs on payroll and decide how to run it. Some businesses hire part-time W-2 staff with flexible schedules. Others use a staffing agency or professional employer organization; our comparison of PEO versus in-house payroll sets out the fee and control trade-offs. A PEO handles administration, but your business remains responsible for how the worker is managed.
Remote hires add another layer. A California company with employees in other states must register and withhold in each one; see our notes on multi-state payroll taxes. For a broader primer on contractor status for both workers and employers, read understanding 1099 employees.
For CPA firms, AB5 work is mostly data work: pulling vendor histories, calculating back-tax exposure by quarter, preparing amended DE 9 filings and modeling the ongoing cost of reclassification. Madras Accountancy supports US CPA firms with that execution layer, including outsourced payroll and 1099 processing, so partners can spend their time on the classification judgment calls and client conversations. Legal conclusions on classification should still come from employment counsel.
It applies to work performed in California. A New York company paying a California-resident designer who works from Los Angeles needs to apply the ABC test to that relationship. The location of the worker and the work matters more than where the company is headquartered.
No. The IRS uses a common-law test focused on behavioral control, financial control and the relationship of the parties. A worker can pass the IRS test and still fail California's prong B, which is why California businesses usually apply the stricter state rule to both.
An LLC helps with the B2B exemption and prong C, but it is one condition among many. If the LLC's owner works only for you, on your schedule, doing your core work, the entity does not change the result.
Reclassification stops future exposure but does not erase past periods. The worker can still claim unpaid wages and premiums for earlier periods within the statute of limitations, typically three years for most wage claims and four years under the Unfair Competition Law.
We found no 2025 or 2026 amendment that rewrote the ABC test. The structure set by AB 2257 still governs. The 2026 changes that matter in practice are payroll rates such as the 1.3 percent SDI rate and the federal 1099 threshold increase.
If your firm has California clients with contractor-heavy payrolls and needs help quantifying exposure or running reclassified payroll, talk to Madras Accountancy about dedicated support for your team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



