



Accounting firm M&A hit a record in 2025, with 194 transactions counted by Capstone Partners, and private equity buyers made up more than half. In 2026 the largest firms joined in: Crowe and Eide Bailly took PE investment and Grant Thornton agreed to buy CBIZ. Succession, talent and technology costs drive most deals.
Mergers and acquisitions have become a main route to growth, talent and new services for accounting firms of every size. This article covers the latest deal data, the forces behind it, and what buyers and sellers should focus on.
According to Capstone Partners data reported by CPA Practice Advisor, there were a record 194 accounting firm transactions in 2025, up 26% from 2024. Capstone counted 62 more deals in 2026 through its July report, up 14.8% year over year, and expects activity to keep growing.
Private equity is now the largest buyer group. Financial acquirers, mainly PE, accounted for 54.8% of accounting firm deals in Capstone's data, up from 38.9% a year earlier (CPA Practice Advisor). Recent examples reported in the trade press:
Big firms are also combining with each other. Baker Tilly and Moss Adams agreed to merge in April 2025, backed by additional investment from Hellman & Friedman and Valeas Capital Partners (Journal of Accountancy). In July 2026, PE-backed Grant Thornton Advisors agreed to acquire CBIZ for $55 per share in cash, a deal expected to close in the fourth quarter of 2026 and create one of the five largest US firms (Journal of Accountancy).
Many deals aim to expand beyond traditional accounting and audit. As technology automates routine work, firms buy capabilities in advisory areas such as cybersecurity, data analytics, wealth management and industry-specific consulting, so they can offer a wider range of services under one roof.
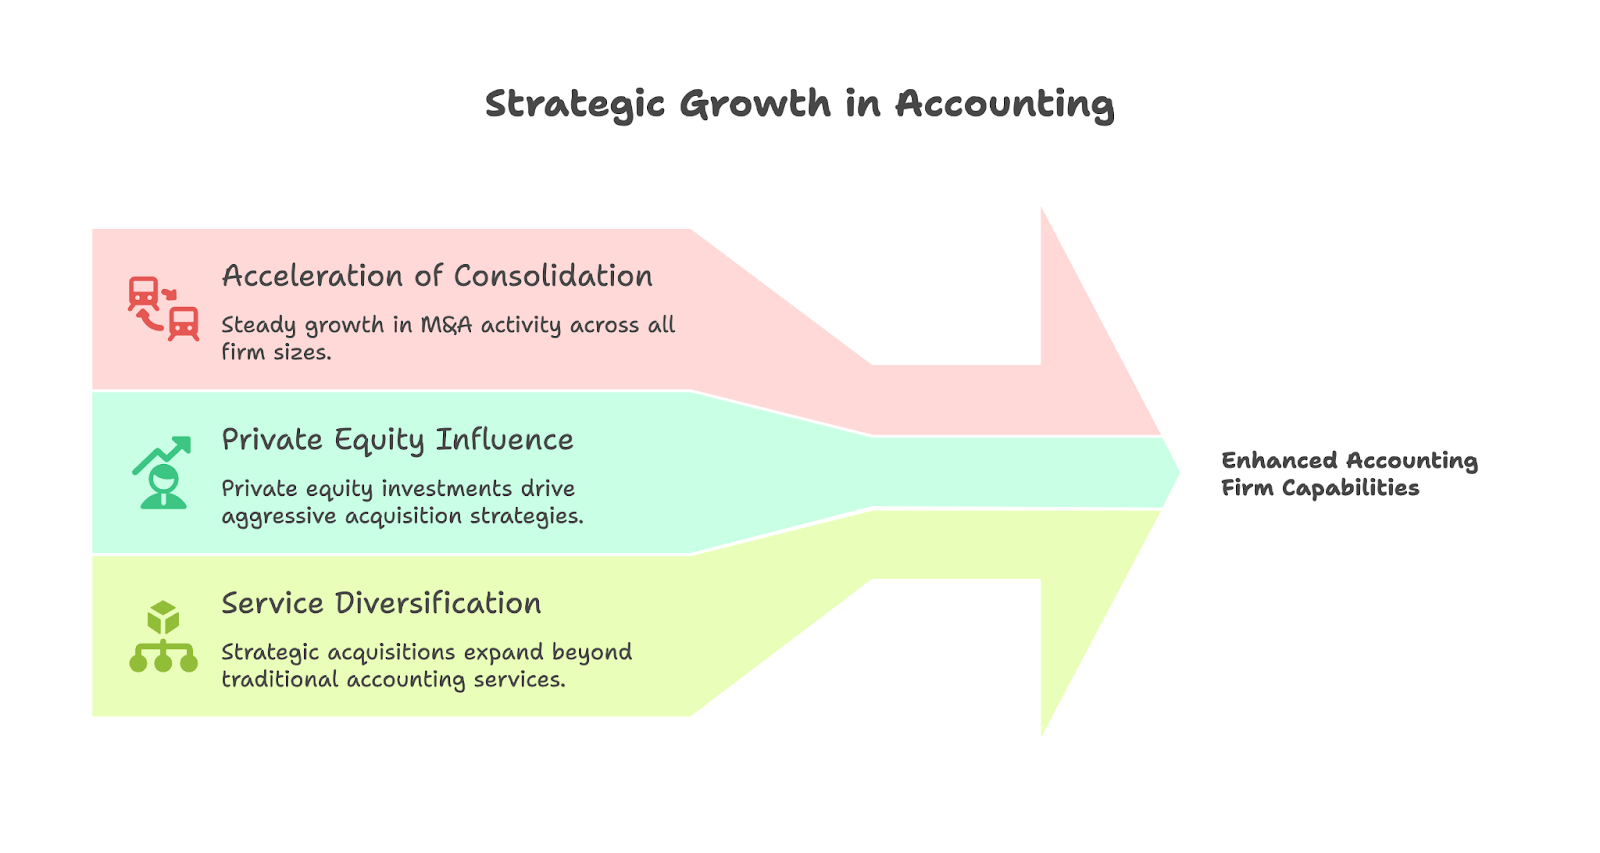
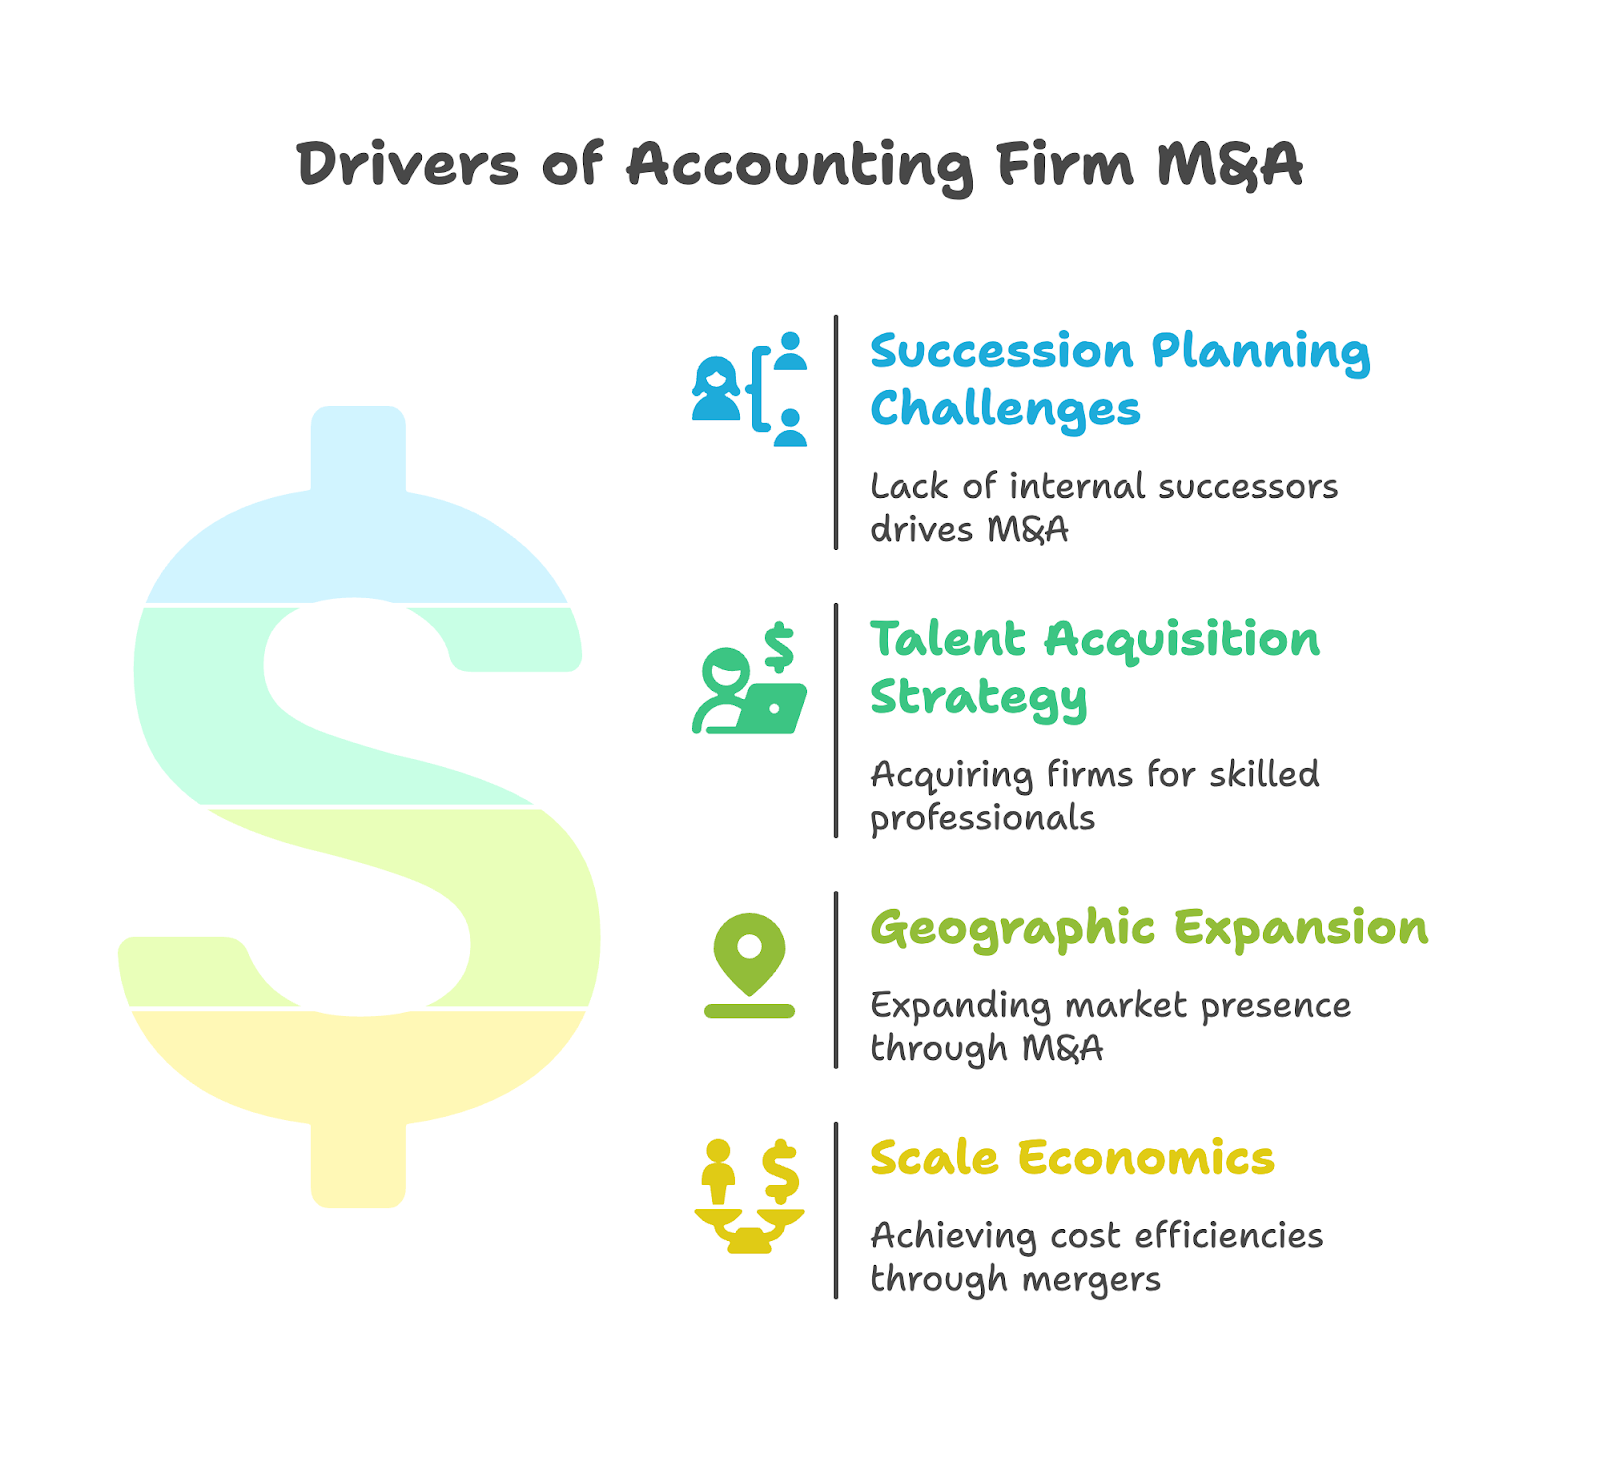
Many firm owners are nearing retirement without internal successors who have the capital and management skills to buy them out. Selling to or merging with a larger firm gives owners an exit and gives clients continuity.
With fewer accounting graduates and CPA candidates in recent years, buying a firm is often the fastest way to add experienced staff. Teams with specialist skills, such as data analytics or technology consulting, are especially sought after.
Acquiring an established local practice gives a firm immediate presence, staff and client relationships in a new market, which is faster than opening an office from scratch.
Larger firms can spread the cost of technology, cybersecurity, quality control and specialist staff across more revenue. Combining back offices and standardizing service delivery can improve profitability.
Capstone's research found that investors now give more weight to AI readiness, automation, organic growth and advisory capability when assessing firms (CPA Practice Advisor). Smaller firms that cannot fund these investments alone may look for a larger partner.
Mergers among large firms reshape the top of the profession. The 2022 combination of BKD and Dixon Hughes Goodman created Forvis, and the 2025 Baker Tilly-Moss Adams merger and the pending Grant Thornton-CBIZ deal continue that pattern.
Beyond headline deals, mid-sized regional firms combine to reach the size needed for specialist services and technology investment. These deals tend to focus on cultural fit and complementary services.
Once a PE investor backs a platform firm, that firm usually acquires smaller practices as "add-ons". Capstone expects sponsor-led platform and add-on deals to drive continued growth (CPA Practice Advisor). For sellers, PE-backed buyers widen the range of deal structures available.
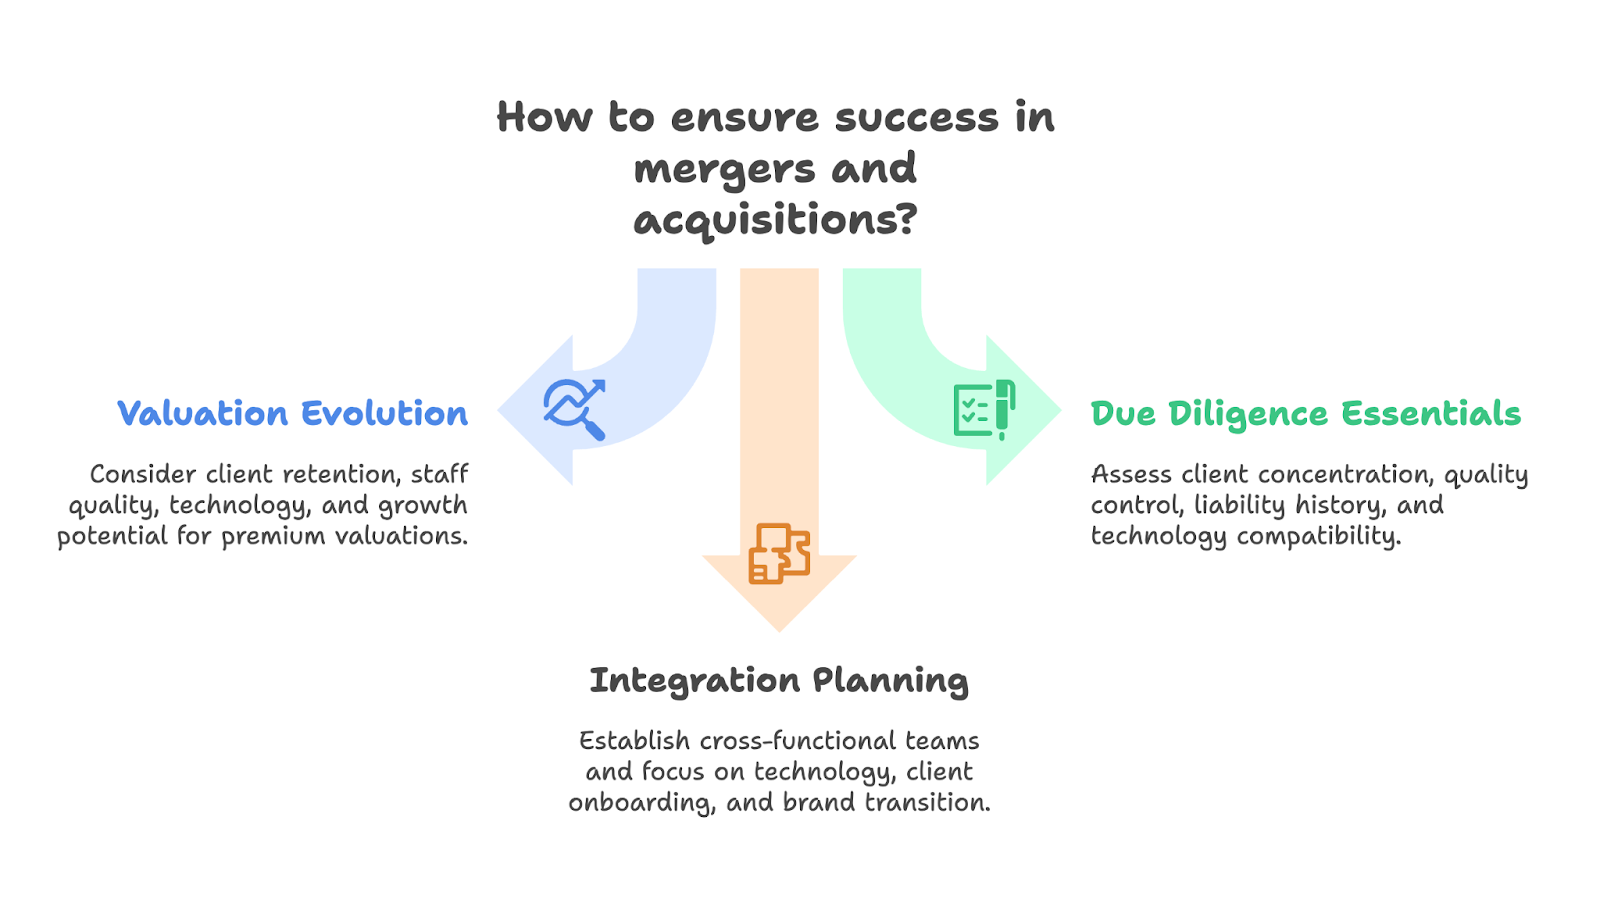
Valuations have moved beyond simple revenue multiples. Buyers look at client retention, staff quality, technology, and growth in higher-value services. In PE deals, EBITDA multiples are common: an Accounting Today analysis described around 5-7x as good, 7-8x as very good, and 9-10x (sometimes up to 11x) as outstanding. Firms with strong advisory practices and specialist expertise usually command higher values.
Profitability benchmarks help sellers see where they stand. The 2025 National MAP Survey (fiscal 2024 medians) reported net remaining per partner of $252,663 and net fees per professional of $208,128 across all firms.
Good due diligence covers both numbers and qualitative factors: client concentration, quality control systems, professional liability history, staff retention, technology and security practices, and cultural compatibility.
Successful deals start integration planning during due diligence, with cross-functional teams and clear accountability. Key workstreams include technology systems, client onboarding, staff training and brand transition, with careful communication to keep client relationships intact.
Technology is both a reason to merge and a source of risk. Firms with outdated systems may benefit from joining a better-equipped firm, while technology-forward firms want acquisitions that make better use of their investment. Integrating different systems takes planning and money and often determines whether a merger succeeds.
Technology due diligence now includes a detailed look at software, data security and automation, with integration plans focused on improving client service and efficiency.
Demographics, technology costs, talent shortages and available capital all point to continued consolidation. Capstone reports that fundraising for accounting-focused PE funds rose in 2026, which supports further deals (CPA Practice Advisor).
Not every firm wants a full merger or PE deal. Alliances, network memberships, partial sales, employee ownership and continuation vehicles offer other ways to gain scale or liquidity. Most PE deals use an alternative practice structure, in which a CPA-owned firm keeps the attest work and a separate advisory company, partly owned by the investor, provides tax and consulting services.
Firms with deep industry or service expertise attract higher valuations. Many firms now use M&A to add specialist capabilities rather than just scale.
Successful mergers have aligned leadership, clear goals and thorough integration planning. Operating as one integrated firm, rather than separate practices under a shared brand, tends to work better. Failures usually come from cultural mismatch, weak due diligence or unrealistic integration timelines.
Client retention during the transition is critical. Firms should plan communication carefully and involve client-facing professionals from both sides.
Accounting firm M&A reached record levels in 2025 and continued into 2026, driven by succession needs, talent shortages, technology costs and private equity capital. The largest firms are now part of the trend, and smaller firms face more offers and more competition.
For owners considering a deal, success depends on understanding these forces, preparing thoroughly, setting clear objectives and planning integration from the start.
Capstone Partners counted a record 194 accounting firm transactions in 2025, up 26% from 2024, with financial buyers, mainly private equity, accounting for 54.8% of deals.
Succession planning, talent shortages, geographic expansion, economies of scale, technology investment, and the move into higher-margin advisory services.
PE investors use alternative practice structures that separate attest work from advisory services, so they can invest while firms stay within licensing and independence rules. This has given owners new exit options and funded acquisition strategies at firms such as Citrin Cooperman, Grant Thornton, Crowe and Eide Bailly.
Client concentration, quality control, professional liability history, staff retention, technology and security, and cultural fit, along with the financial results.
Combining technology systems, aligning compensation, managing cultural differences, standardizing workflows, and keeping client relationships during the transition.
Buyers consider client retention, staff quality, technology, growth in advisory services and specialization. PE buyers usually price on EBITDA multiples, which Accounting Today describes as roughly 5-7x for a good firm and 9-10x or more for an outstanding one.
Your expertise deserves better support. Madras Accountancy works with CPA firms and fractional CFOs as an offshore accounting and tax support partner, so your team can spend more time on review and advisory work. Contact us to talk about your capacity needs.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



