


AP automation ROI is the net benefit of moving invoice capture, approvals and payments into software, divided by what the project costs in its first year. For most small and mid-sized businesses, the result depends on three measurable inputs: staff minutes per invoice, the cost of each payment method, and early payment discounts actually taken.
This guide shows how to calculate AP automation ROI with a worked example, which costs and benefits to leave out, and how to implement the system with stronger controls around vendor payments. It also covers the 2026 Form 1099 changes that an AP system should be configured for from day one.
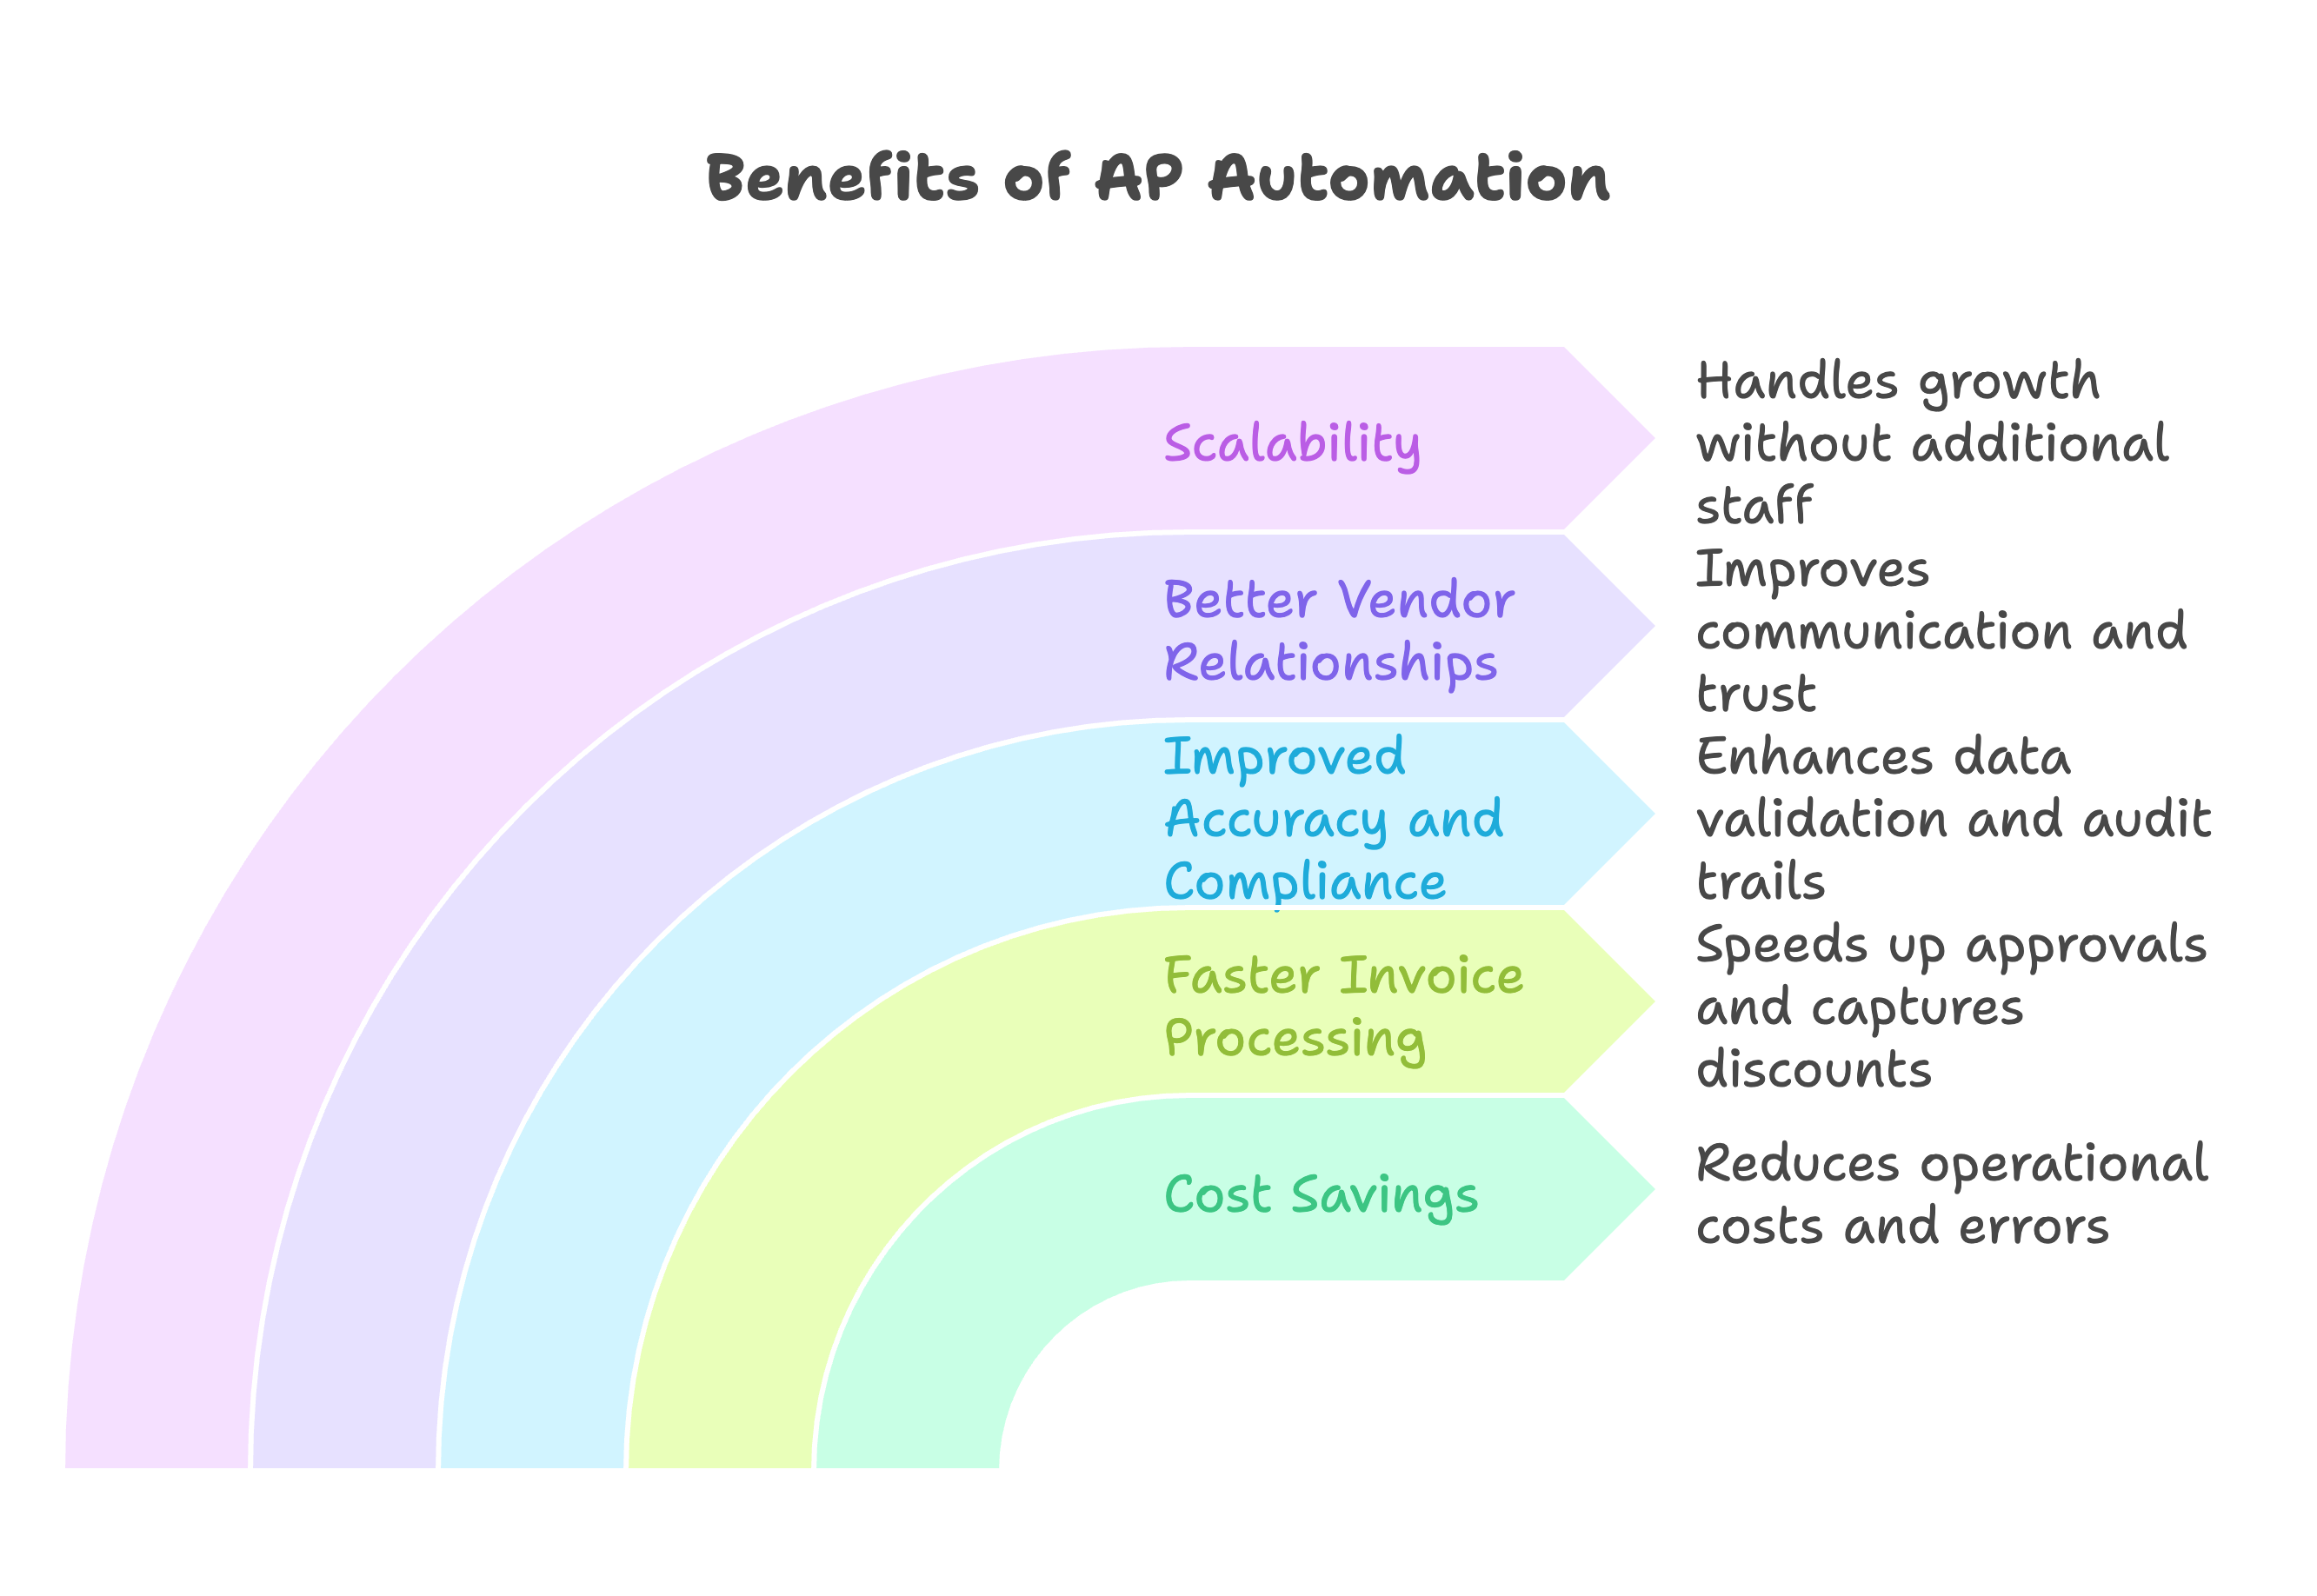
Accounts payable automation is software that handles the steps between receiving a vendor invoice and recording the payment in the ledger. A typical system does the following:
Most products connect to QuickBooks Online, Xero, NetSuite or Sage Intacct. How that connection works (native sync, middleware or a custom build) affects both cost and data quality, so it is worth reading our guide to API integration for accounting workflows before signing a contract.
Many AP tools now use machine learning for invoice capture and coding suggestions. This article treats those features as part of the AP tool. If the wider question is how to introduce AI across the finance team, our practical guide to implementing AI in your accounting department covers governance, data and staffing, and agentic AI in accounting explains what multi-step AI agents can and cannot do today.
A defensible AP automation ROI calculation uses the business's own numbers, measured before the project starts. Industry benchmarks for "cost per invoice" vary widely depending on what each survey counts, so they are a poor substitute for a two to four week time study of your own AP process.
Collect these figures for a normal month (avoid year-end or a month with a system outage):
| Input | How to measure it |
|---|---|
| Invoices per month | Count of bills entered in the ledger |
| Minutes per invoice | Time study of entry, coding, chasing approvals and filing |
| Loaded hourly cost | Wage plus payroll taxes and benefits for the people doing the work |
| Payments by method | Count of checks, ACH, wires and card payments |
| Cost per payment method | Check stock, postage, bank fees, staff time to print and mail |
| Discounts offered and taken | Vendor terms such as 2/10 net 30, and how often they were captured |
| Late fees and duplicate payments | From the last 12 months of vendor statements and recoveries |
Ask the vendor for a trial on your own invoices and time the same tasks. Use their published pricing for subscription and per-transaction fees, and get a written quote for implementation.
The figures below are illustrative assumptions for a fictional distributor, chosen to show the method. They are not benchmarks, and your inputs will differ. All arithmetic was checked in Python.
Assumptions
| Line | Before | After | Annual change |
|---|---|---|---|
| Invoice labor (9,600 invoices) | $67,200 | $22,400 | $44,800 saved |
| Payment costs (3,600 payments) | $14,400 | $5,580 | $8,820 saved |
| Extra early payment discounts | $9,600 gained | ||
| Annual gross benefit | $63,220 | ||
| Software subscription | ($12,000) | ||
| Annual net benefit | $51,220 | ||
| One-time implementation | ($11,400) |
Results
Sensitivity check. Labor savings only turn into cash when the freed hours avoid a hire, cut overtime or move to work the business would otherwise pay for. If only half of the $44,800 labor saving is realized, annual gross benefit falls to $40,820, first-year ROI falls to 74% and payback stretches to 4.7 months. Running this downside case before presenting the business case keeps expectations honest.
Why the discount line matters. Taking a 2% discount for paying 20 days early is equivalent to an annualized return of about 37% (2/98 multiplied by 365/20). An AP system that schedules those payments automatically often produces more value than the labor saving, provided the business has the cash to pay early. A short-term cash flow forecast helps decide how much discount capture the business can fund.
Automation moves money faster, and that includes fraudulent or duplicate payments. The control design matters as much as the ROI. Before go-live, document how each control will work and who owns it, then test it the way our guide to internal controls testing for small businesses describes.
Duplicate payments usually come from the same invoice arriving twice (email and paper, or a resent statement) with small differences in the invoice number. Configure the system to flag matches on vendor plus amount plus invoice date, as well as vendor plus normalized invoice number (stripped of spaces, dashes and leading zeros). Route flagged items to a reviewer, and review the override log monthly as part of the AP and reconciliation steps in your close checklist.
The vendor master file (names, addresses, tax IDs and bank details) is a common target for payment fraud. Good practice includes:
The FBI's Internet Crime Complaint Center (IC3) defines BEC as "a scam targeting businesses or individuals working with suppliers and/or businesses regularly performing wire transfer payments." Its 2025 annual report recorded 24,768 BEC complaints with reported losses of $3,046,598,558, up from $2,770,151,146 in 2024. The same report notes that in 2025 "businesses reported losses over $30 million to BEC scams involving AI," including emails and cloned voices impersonating executives.
For AP, the practical defense is that no email, however convincing, can change payment details or approve a payment on its own. The vendor change callback above, dual approval for payments over a set amount, and bank-side tools such as positive pay all apply. Our fraud prevention guide covers wider controls against embezzlement and external fraud.
AP automation is the right moment to clean up 1099 data, because every vendor record gets reviewed during migration anyway.
The 2026 threshold. The IRS states: "For payments made before 2026, the reporting threshold is $600." and "For payments made in 2026, the reporting threshold is $2,000." (IRS, Am I required to file a Form 1099). The Instructions for Forms 1099-MISC and 1099-NEC add that the threshold "may be adjusted for inflation beginning in calendar year 2027," so check the figure each year rather than hard-coding it. Some 1099-MISC boxes keep different amounts, such as $600 for gross proceeds paid to attorneys. Our article on the 2026 1099 reporting threshold sets out the full rules.
Payment method tracking. The same IRS instructions say payments made by credit card or payment card and third-party network transactions are reported on Form 1099-K by the payment settlement entity and "are not subject to reporting on Form 1099-MISC or Form 1099-NEC." Your AP system should record the payment method on every payment so 1099 totals exclude card payments automatically.
W-9 collection. Make a completed Form W-9 a required step in vendor onboarding. The IRS describes the form's purpose as follows: "Use Form W-9 to provide your correct Taxpayer Identification Number (TIN) to the person who is required to file an information return with the IRS" (About Form W-9). Store the form against the vendor record in the AP system.
TIN Matching. The IRS TIN Matching service "lets you validate TIN and name combinations before submitting an information return," and is available only to "payers and their authorized agents that submit information returns." Running new vendors through TIN Matching at onboarding catches name and number mismatches months before the January 1099 deadline.
Backup withholding. If a vendor fails to provide a correct TIN, the payer may be required to withhold at "the current rate of 24 percent" under the IRS backup withholding rules (IRS, Backup withholding). Configure the AP system to flag vendors without a valid TIN so payments can be held or withheld as required. For the year-end side of this work, see our 1099 checklist for accountants.
Some businesses decide that software alone does not fix the problem because nobody has time to run the exceptions queue. Our guides on outsourcing accounts payable and on what to automate versus what to outsource compare those options.
Low vendor adoption. Keep an email inbox option open alongside the portal during the transition and track which vendors still send paper.
Approval bottlenecks. If approvers ignore notifications, set escalation rules after a fixed number of days and review the approval aging report weekly.
Integration errors. Test that vendors, GL accounts, classes and payment statuses sync both ways before go-live. Reconcile the AP subledger to the GL at each month-end for the first quarter.
ROI that does not show up. Usually the freed hours were absorbed rather than redeployed. Decide in advance what work the AP team will take on, and measure it.
What is a good AP automation ROI? There is no standard figure. A project that pays back its one-time costs within the first year on the business's own measured baseline is generally easy to justify. Run a downside case with only half the expected labor savings before deciding.
How long does AP automation implementation take? It depends on invoice volume, number of entities and integration complexity. A single-entity business on a mainstream ledger can often pilot within a few weeks, while multi-entity or PO-heavy businesses need longer for configuration and parallel running.
Does AP automation handle Form 1099 reporting? Many systems track 1099 vendors and totals, but the output is only as good as the vendor data. Collect W-9s at onboarding, validate them through IRS TIN Matching, record payment methods so card payments are excluded, and apply the $2,000 threshold for payments made in 2026.
How does AP automation reduce fraud risk? It creates an audit trail and can enforce approval limits and duplicate checks. It does not stop business email compromise by itself, so bank detail changes still need callback verification on a known phone number and segregation between vendor edits and payment approvals.
Madras Accountancy supports US CPA firms and businesses with outsourced accounts payable, bookkeeping and month-end close work, including vendor master cleanup, 1099 preparation and day-to-day processing in the client's chosen AP and ledger software. To discuss your AP process, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



