

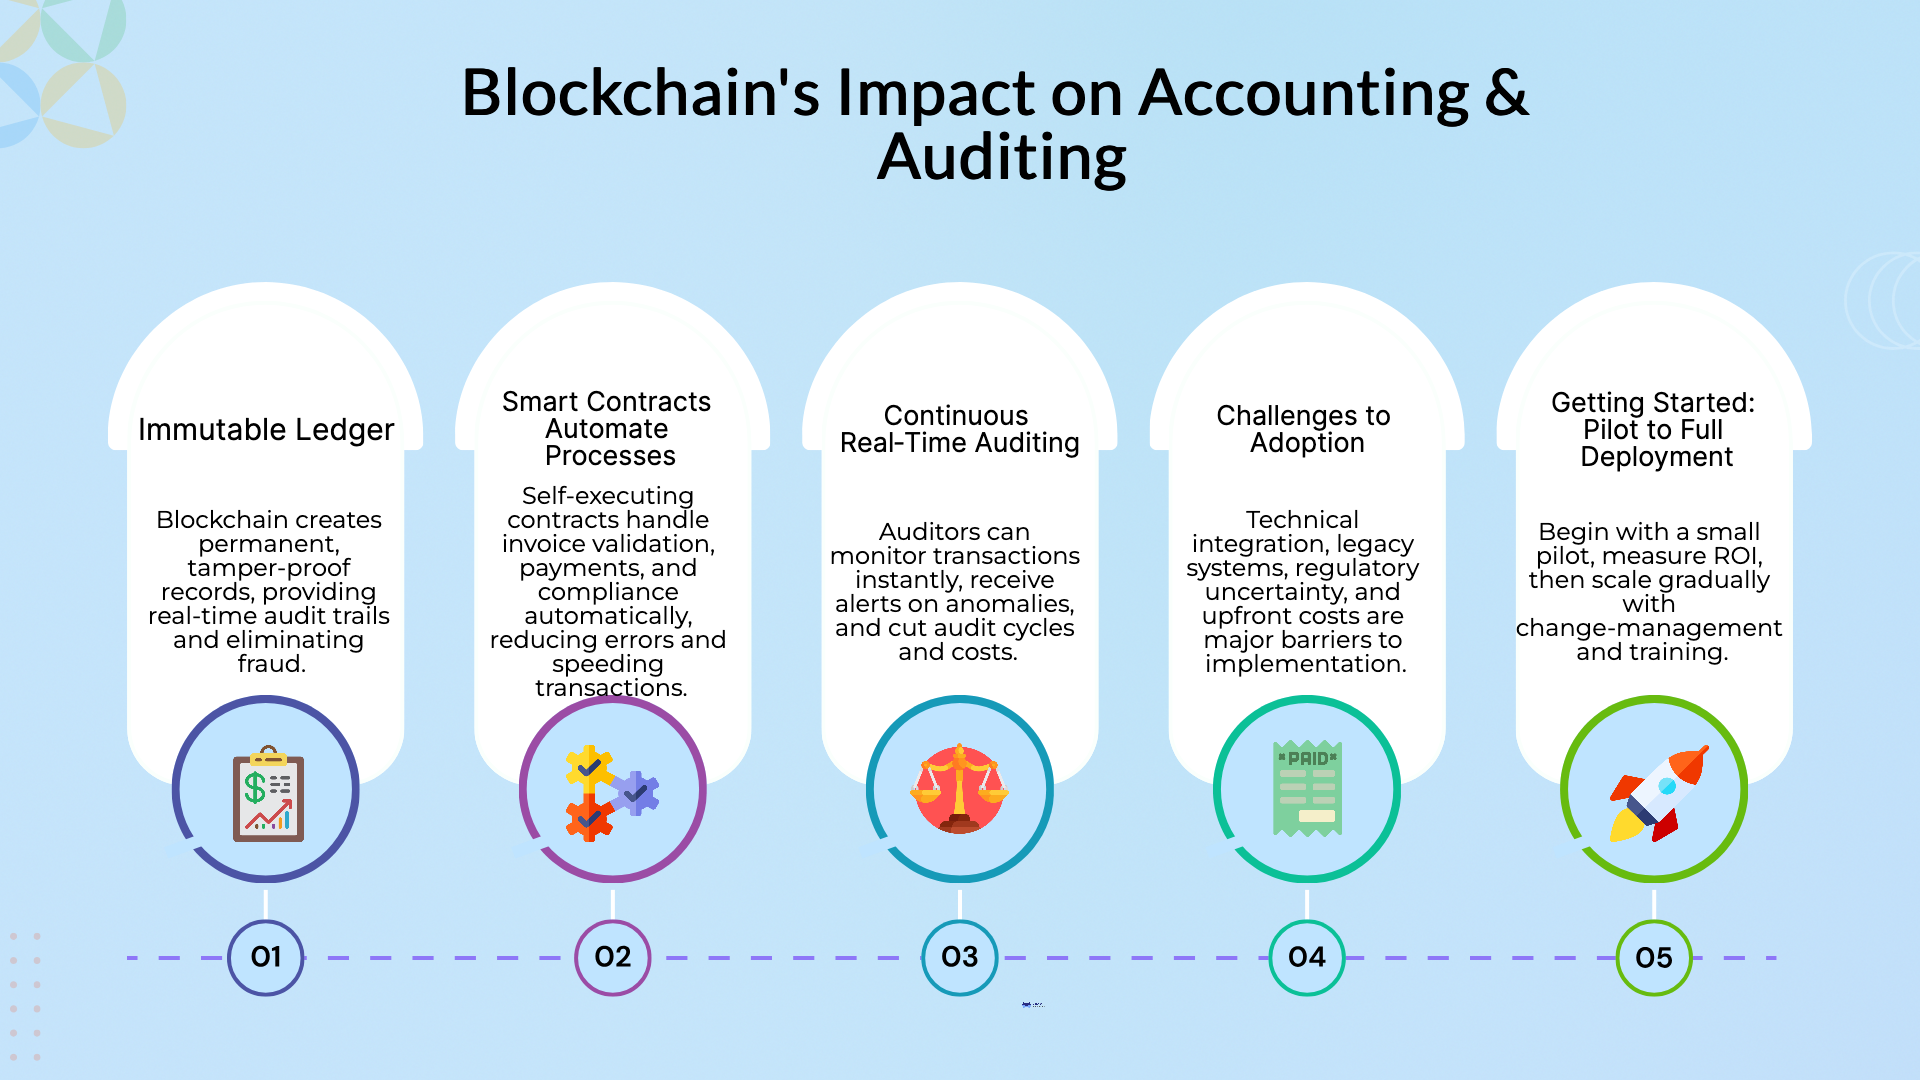

Blockchain in accounting is real in 2026, though narrower than early forecasts promised. Its proven uses are crypto asset accounting and audits, on-chain evidence for existence and ownership of digital assets, and shared ledgers for product tracing in some supply chains. Most general ledgers, payables and receivables still run on conventional databases.
That gap matters for finance teams and CPA firms deciding where to spend time. This guide covers what blockchain in accounting does today, what regulators and standard setters have said about it, how auditors test on-chain records, and the limits that keep it from replacing the audit. It is written for US businesses and firms that hold, account for or audit digital assets, or that are being pitched blockchain tools.
The National Institute of Standards and Technology describes blockchains as "tamper evident and tamper resistant digital ledgers implemented in a distributed fashion", usually without a central authority. NIST adds that "under normal operation of the blockchain network no transaction can be changed once published." The qualifier "under normal operation" is important. A ledger is only as reliable as the network, the consensus rules and the people holding the keys.
For accountants, three properties matter:
None of those properties says anything about whether a transaction was authorized, priced correctly or classified correctly in the financial statements. That limitation runs through every section below.
The early wave of articles on how blockchain could transform accounting and auditing predicted triple entry bookkeeping, instant audits and the end of reconciliations. By 2026 the adoption pattern looks different. Use is concentrated where the asset itself lives on a blockchain, or where several companies need a shared record of goods moving between them.
| Use case | What blockchain contributes | Status in 2026 |
|---|---|---|
| Crypto asset accounting | The asset exists only as an on-chain record, so balances and transfers can be traced to the ledger | Mainstream for holders; fair value under ASU 2023-08 |
| Audits of crypto holdings | On-chain data supports existence and some ownership testing | Common, with PCAOB scrutiny of evidence quality |
| Third-party confirmations | Public ledger balances can corroborate some assertions | Limited; ownership and control still need separate evidence |
| Supply-chain tracing | Shared ledger of product movements among trading partners | Piloted and used in some industries, alongside standards like EPCIS |
| Smart contract payments | Automated settlement when coded conditions are met | Niche; mostly within crypto and DeFi |
| General ledger replacement | Distributed ledger as the company's books of record | Rare; ERP and cloud ledgers remain the norm |
This is the largest real use. A company holding bitcoin or ether keeps its subledger in the accounting system and ties it to wallet balances on the blockchain. Since FASB's ASU 2023-08, in-scope crypto assets that reside on "a distributed ledger based on blockchain or similar technology" are measured at fair value with changes in net income, effective for fiscal years beginning after December 15, 2024. The full scope test, presentation and disclosure rules are covered in our guide to cryptocurrency accounting under ASU 2023-08.
On the tax side, the blockchain record also feeds broker reporting. Our explainer on Form 1099-DA for digital asset proceeds covers what brokers now send, and the guide to calculating crypto cost basis explains how lot records connect to on-chain transfers.
The FDA's Drug Supply Chain Security Act pilot program tested ways for trading partners to exchange product tracing data electronically. Several of the 20 listed pilots used distributed ledgers, including the "DSCSA Blockchain Interoperability Pilot" led by IBM, KPMG, Merck and Walmart, and a UCLA Health project titled "UCLA-LedgerDomain: DSCSA Solution Through Blockchain Technology." The FDA said it "considered all viable technologies and methods from the pilot projects" and that selection should not be read as a position on any entity's compliance or as an endorsement of a particular technology. In other words, blockchain was one of several candidate tools, and the program did not mandate it.
For accountants, supply-chain ledgers matter mainly as an evidence source. Shared shipment and custody records can support inventory existence and cutoff testing, provided the auditor understands who controls the data. Manufacturers working through those questions should also review the basics of inventory accounting for manufacturers.
The most cited professional analysis is the 2018 audit and assurance alert "Blockchain Technology and Its Potential Impact on the Audit and Assurance Profession," prepared by the AICPA, CPA Canada and the University of Waterloo with Deloitte contributors. The Journal of Accountancy summary records its central caution: a blockchain record "may not provide sufficient audit evidence related to the nature of the transaction." The paper lists ways a recorded transaction can still be a problem. It may:
The paper also noted that "there is a good chance the blockchain would not be controlled by the entity being audited," so auditors must extract the data and judge its reliability themselves. It suggested new roles for CPAs, such as auditor of smart contracts and service auditor of consortium blockchains. That second role overlaps with the system and organization control reports discussed in our comparison of SOC 1 and SOC 2 audits.
The AICPA's more practical resource is its practice aid Accounting for and Auditing of Digital Assets, which the AICPA describes as nonauthoritative guidance. Its August 2026 update added "a new chapter dedicated to accounting considerations for stablecoin issuers" and a new auditing chapter on mining revenue arrangements, and it was "updated to reflect auditing standards through Statement on Auditing Standards (SAS) No. 148." Firms auditing crypto holders should work from the current edition.
PCAOB staff addressed crypto audits directly in June 2023. Their Spotlight, "Inspection Observations Related to Public Company Audits Involving Crypto Assets," grouped deficiencies into five areas, as summarized in Deloitte's DART news item on the release:
Two of those five go straight to the blockchain question. Ownership is hard because a public ledger shows that an address holds tokens, and it does not show who controls the private keys. Evidence reliability is hard because block explorers, node data and custodian reports are all information produced outside the entity, and the auditor has to test their relevance and reliability before relying on them. Preparers can use the five areas as a checklist of what their auditor is likely to test.
For a company preparing for its first audit with crypto on the balance sheet, practical steps (practitioner guidance) include:
Our PBC request list for first-time audits shows how to package this evidence, and the guide to internal controls testing for small businesses explains how auditors test key controls such as wallet access.
A major 2025 change for crypto custodians came from the SEC. Staff Accounting Bulletin 121, issued in March 2022, said an entity safeguarding crypto assets for platform users "should present a liability on its balance sheet to reflect its obligation to safeguard the crypto-assets", measured at fair value with a matching asset.
SAB 122, dated January 23, 2025 and effective January 30, 2025, "rescinds the interpretive guidance included in Topic 5.FF." Entities now decide whether to recognize a liability for the risk of loss by applying "the recognition and measurement requirements for liabilities arising from contingencies," meaning ASC 450-20 under US GAAP or IAS 37 under IFRS. The rescission applies "on a fully retrospective basis in annual periods beginning after December 15, 2024," with earlier adoption allowed. The SEC also says entities "should continue to consider existing requirements to provide disclosures that allow investors to understand" these obligations, citing Regulation S-K Items 101, 105 and 303 and ASC 275.
For banks, broker-dealers and platforms that custody digital assets, SEC staff guidance no longer requires the balance sheet gross-up. A liability is recorded only when ASC 450-20 or IAS 37 calls for one, while the disclosure work on safeguarding risk continues under the existing requirements.
This example is illustrative. A US company holds bitcoin as treasury assets in three wallets. At December 31, its subledger shows 40.00 BTC. The period-end price from its principal market at the policy cutoff time is $90,000 per BTC.
| Source | BTC | Fair value at $90,000 |
|---|---|---|
| Subledger balance | 40.00 | $3,600,000 |
| Wallet A on-chain | 25.00 | $2,250,000 |
| Wallet B on-chain | 10.00 | $900,000 |
| Wallet C on-chain | 4.98 | $448,200 |
| Total on-chain | 39.98 | $3,598,200 |
| Difference | 0.02 | $1,800 |
Tracing Wallet C's history on a block explorer shows a December 31 outbound transfer between the company's own wallets with a 0.02 BTC network fee. The internal transfer was booked, and the fee was not. The adjusting entry is a debit to transaction fee expense of $1,800 and a credit to digital assets of $1,800, bringing the carrying amount to $3,598,200.
The blockchain made this break easy to find, which is the real accounting benefit. It did not prove that Wallet C belongs to the company. The auditor would still ask for evidence of key control, such as a signed message from that address. A wallet reconciliation like this belongs in the monthly close checklist for any entity holding crypto, and month-end is when the evidence is easiest to collect.
Plenty of 2017 to 2019 predictions have not come true. Five limits explain most of the gap.
Recording is different from validating. A blockchain proves a transfer happened between addresses. It does not show the business purpose, the counterparty's identity or whether a related party sits behind the address. This is the core point of the AICPA and CPA Canada paper, and the PCAOB's fraud and ownership findings show it playing out in inspections.
Errors are preserved. An append only ledger preserves errors as well as correct entries. Corrections are new entries, which gives a cleaner trail and still requires someone to spot the error.
Most business activity is off-chain. Payroll, rent, vendor invoices and bank transactions run on banks, ERPs and payment networks. A blockchain only covers the slice of activity recorded on it, so auditors still need traditional procedures for everything else.
Smart contracts carry code risk. A coded payment executes exactly as written, including any bug. Auditing that logic requires technical skills most accounting teams do not have.
Integration cost. Shared ledgers need every trading partner to participate and agree on data standards. The FDA program listed blockchain among many tracing approaches, which reflects that interoperability problem.
Fraud risk does not disappear either. Our primer on fraud prevention covers controls that apply whether the record is on a blockchain or in a spreadsheet.
The audit change that did arrive at scale came from data analytics and AI, often applied to conventional ledgers. Full population testing, anomaly detection and automated matching now handle much of what early blockchain papers promised. Our guides to AI in audit and assurance and technology in auditing through analytics and automation cover those tools.
Where the two meet, blockchain supplies a clean, time-stamped data set and analytics tools test it. A practical outlook for firms is in our piece on the accounting firm of 2030.
What is blockchain in accounting used for in 2026? Mainly for accounting and auditing crypto assets, reconciling wallet balances to subledgers, and supply-chain tracing among trading partners. Few companies run their general ledger on a blockchain.
Can blockchain replace auditors? No. The AICPA and CPA Canada paper notes that a recorded transaction can still be unauthorized, fraudulent, linked to an off-chain agreement or misclassified. Auditors also have to judge the reliability of blockchain data the client does not control.
What did SAB 122 change? It rescinded SAB 121, effective January 30, 2025. Entities that safeguard crypto assets for others now apply ASC 450-20 or IAS 37 to decide whether to record a liability, and they continue to disclose safeguarding risks.
What does the PCAOB focus on in crypto audits? Its 2023 Spotlight grouped deficiencies into fraud and significant unusual transactions, ownership, the relevance and reliability of audit evidence, revenue recognition on crypto transfers, and mining pool arrangements.
How should crypto be measured on the balance sheet? In-scope crypto assets under ASU 2023-08 are measured at fair value with changes in net income for fiscal years beginning after December 15, 2024. Assets outside the scope, such as some stablecoins, follow other guidance.
Does a small business need blockchain software for bookkeeping? Generally no. A business that holds or accepts crypto needs wallet records, a pricing policy and a monthly reconciliation in its existing accounting system.
Madras Accountancy supports US businesses and CPA firms with bookkeeping, monthly close, tax preparation, CFO and advisory work, and audit support, including schedules and reconciliations for companies that hold digital assets. To discuss your books or audit preparation, contact our team.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



