


Entity choice drives how a client pays tax, who is exposed when something goes wrong, and how easily the business can be sold or funded later. This business entity selection guide is written for CPA firms advising founders and owners in 2026, and it reflects the One Big Beautiful Bill Act (OBBBA) of July 2025, which made the 20% qualified business income deduction permanent and expanded the qualified small business stock exclusion. Both changes shift the math between pass-through entities and C corporations.
Attorneys usually file the formation documents. The CPA's job is the modeling: tax cost this year and over the holding period, payroll and compliance load, state exposure and the exit. A recommendation that ignores any one of those tends to be revisited, at a cost, within a few years.
Clients often mix up two separate decisions. The legal entity (LLC, corporation, general or limited partnership) is created under state law and determines liability protection and governance. The tax classification is a federal choice that sits on top of it.
The IRS default rules, summarized on its business structures page, work like this:
An LLC can change its default with Form 8832 to be taxed as a corporation. To be taxed as an S corporation, an eligible LLC or corporation files Form 2553. An LLC that files a timely Form 2553 is treated as having elected corporate classification as well, so a separate Form 8832 is generally unnecessary. For a calendar-year business, the election is due no more than 2 months and 15 days after the start of the tax year it is meant to cover (March 15 for a calendar-year entity), and late-election relief exists for reasonable cause. Our walkthrough of what it takes to make an S corp election covers shareholder consents and common rejection reasons.
The LLC is the default for most closely held operating businesses because it gives state-law liability protection with pass-through tax treatment and few formalities. The operating agreement can allocate profits in almost any way the members agree, subject to the substantial economic effect rules.
Where it costs money is self-employment tax. Active members generally pay 15.3% on 92.35% of net earnings, with the 12.4% Social Security part capped at the annual wage base and the 2.9% Medicare part uncapped, plus the 0.9% Additional Medicare Tax at higher incomes. A profitable single-owner LLC pays that on every dollar of profit.
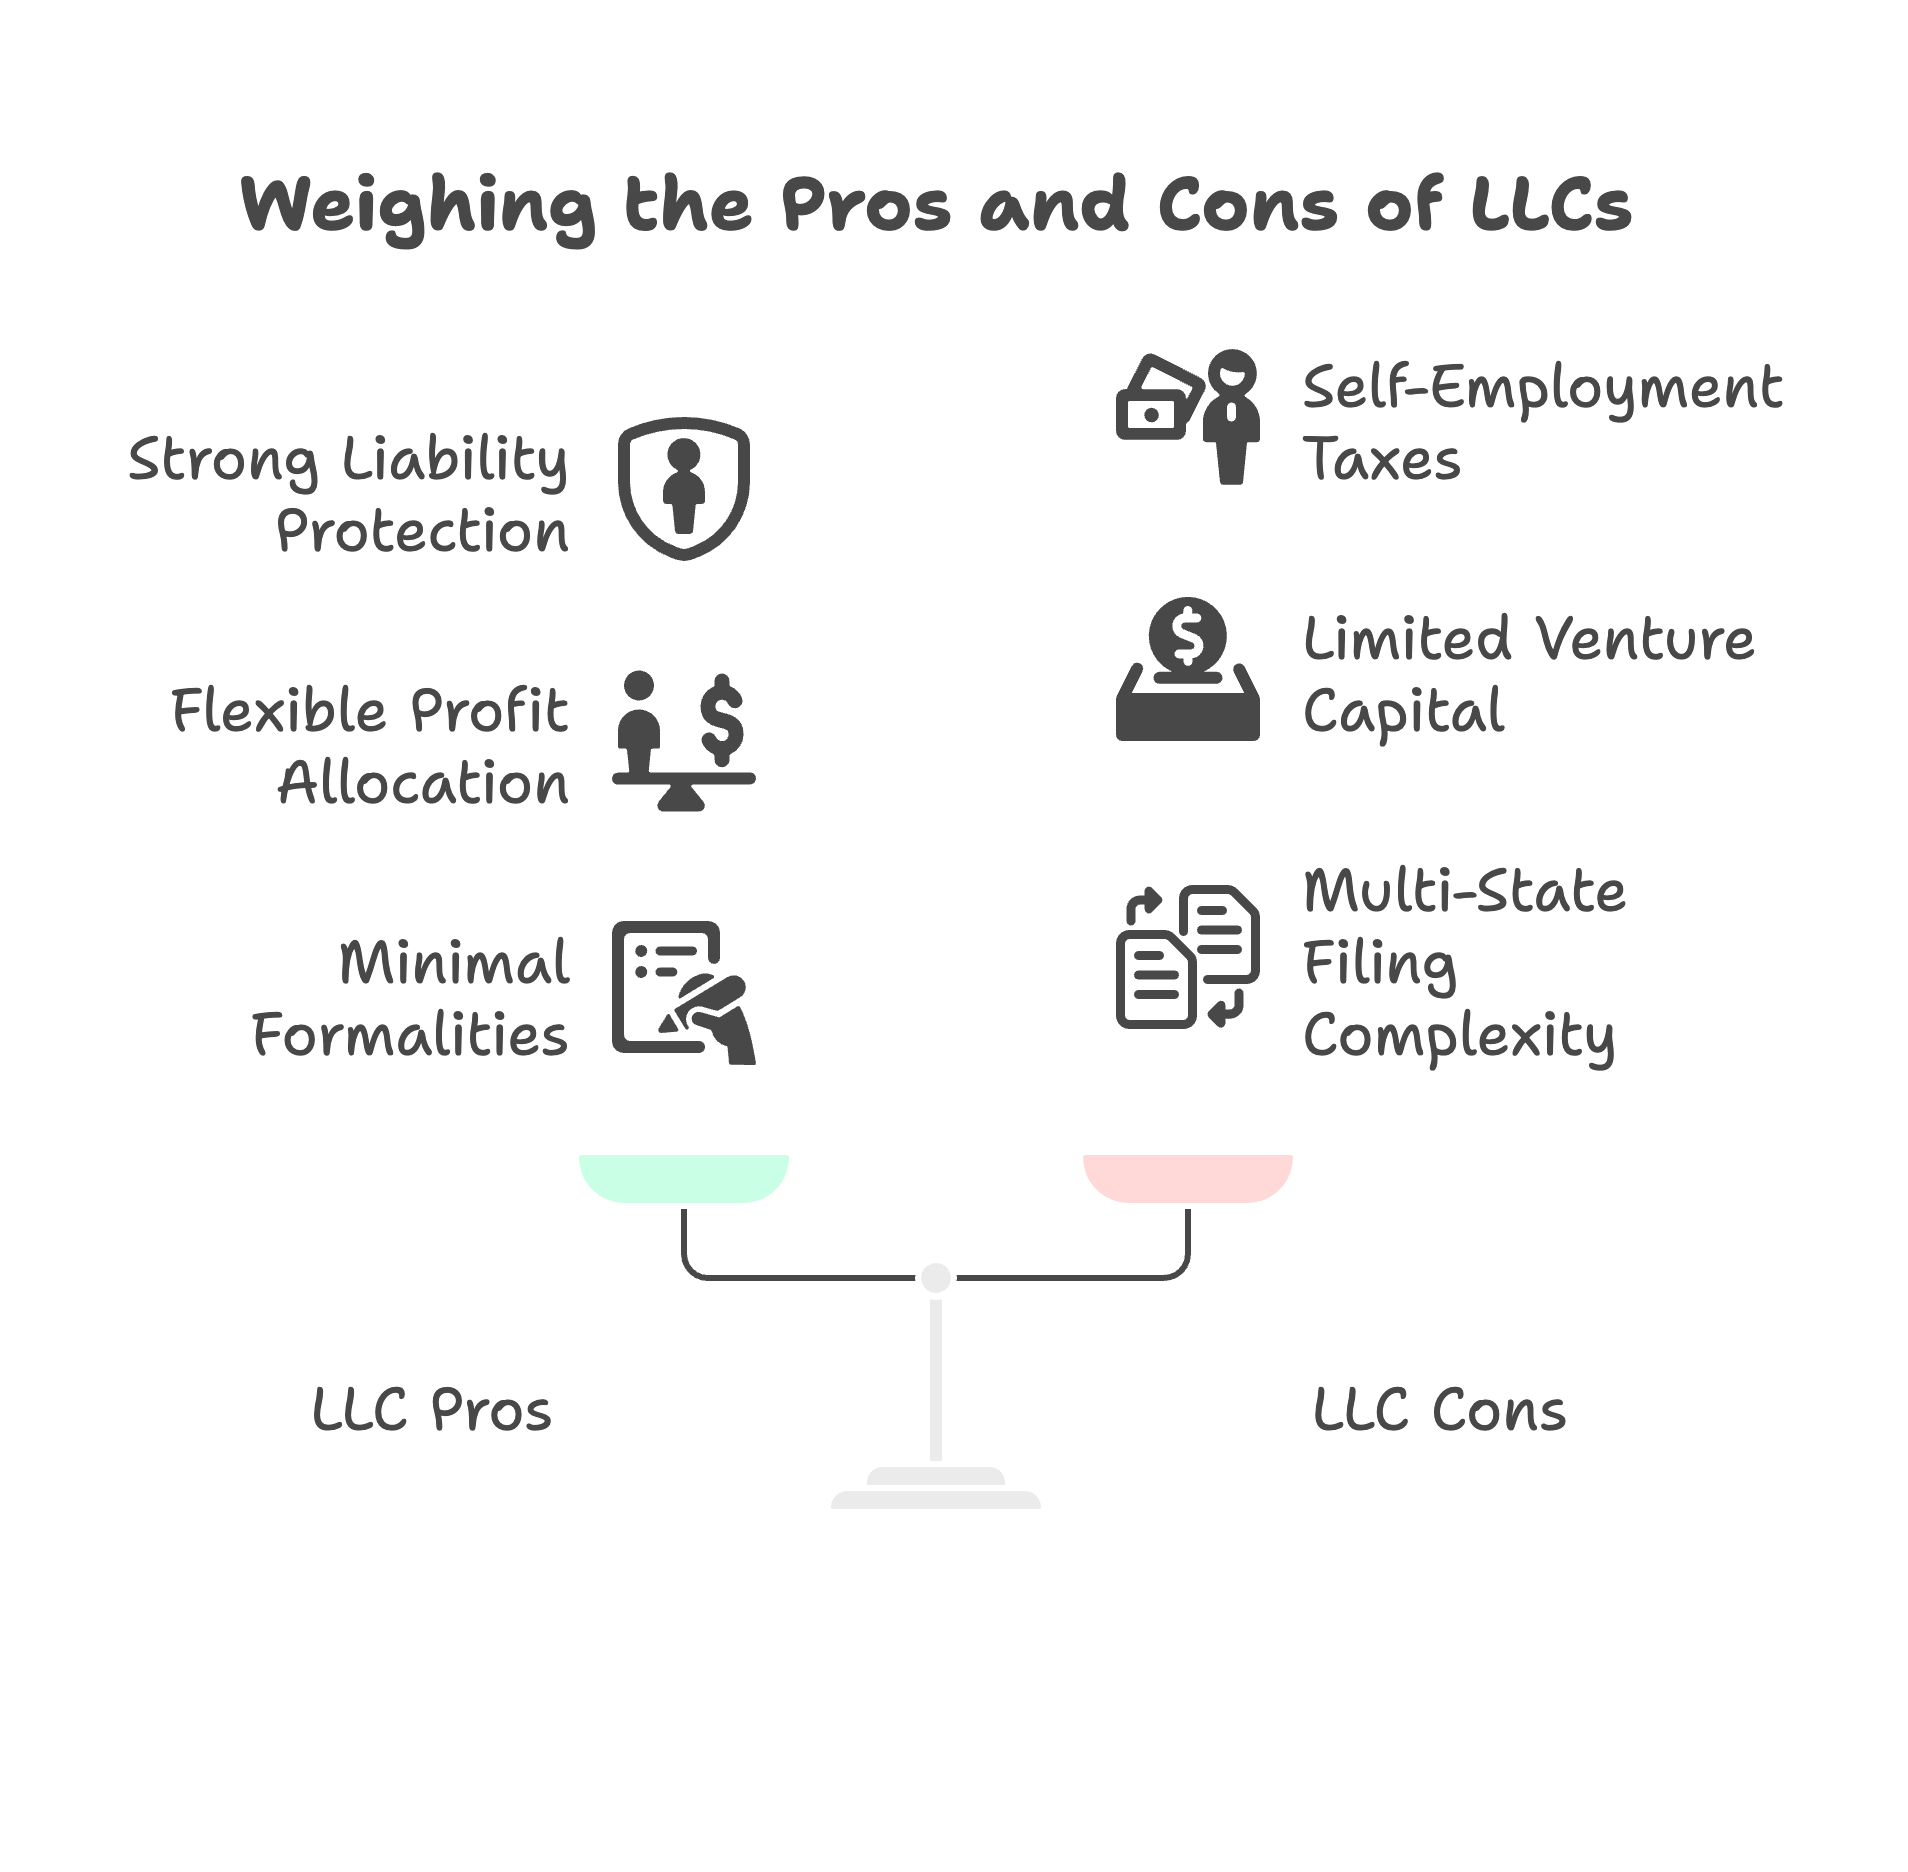
Partnership-taxed LLCs also carry real administrative weight once there are several members: capital accounts, basis tracking, guaranteed payments and Schedule K-1s. For single-owner structures, see our single-member LLC taxation guide.
An S corporation is a tax status, available to a domestic corporation or an LLC that elects it. The limits on who can own it are strict: no more than 100 shareholders, generally individuals who are US citizens or residents, certain trusts and estates, and some exempt organizations. Nonresident aliens, partnerships and corporations cannot hold shares, and only one class of stock is allowed (differences in voting rights alone are permitted).
The attraction is payroll tax. Owner-employees take a W-2 salary and the remaining profit passes through on a K-1 without self-employment tax. The salary must be reasonable for the work performed, and the IRS has won many cases recharacterizing distributions as wages. Before recommending the election, read our guide to reasonable compensation for S corp owners.
Take a consultant with $150,000 of net profit in 2026, single, no other wages.
| Single-member LLC | LLC electing S status | |
|---|---|---|
| Owner salary | n/a | $80,000 |
| Earnings subject to SE tax or FICA | $138,525 (92.35% of $150,000) | $80,000 |
| SE tax / combined FICA | about $21,194 | $12,240 |
| Approximate payroll tax difference | about $8,950 lower |
Against that saving, the S corp pays for payroll processing, a Form 1120-S with K-1s, state unemployment tax on the salary and in some states an entity-level tax. The salary also reduces qualified business income for the Section 199A deduction. The break-even depends on the state and the defensible salary, so run the numbers for each client.
A C corporation pays a flat 21% federal rate on its taxable income, and shareholders pay tax again on dividends. It allows unlimited shareholders, multiple classes of stock and foreign or institutional owners, which is why venture investors expect it.
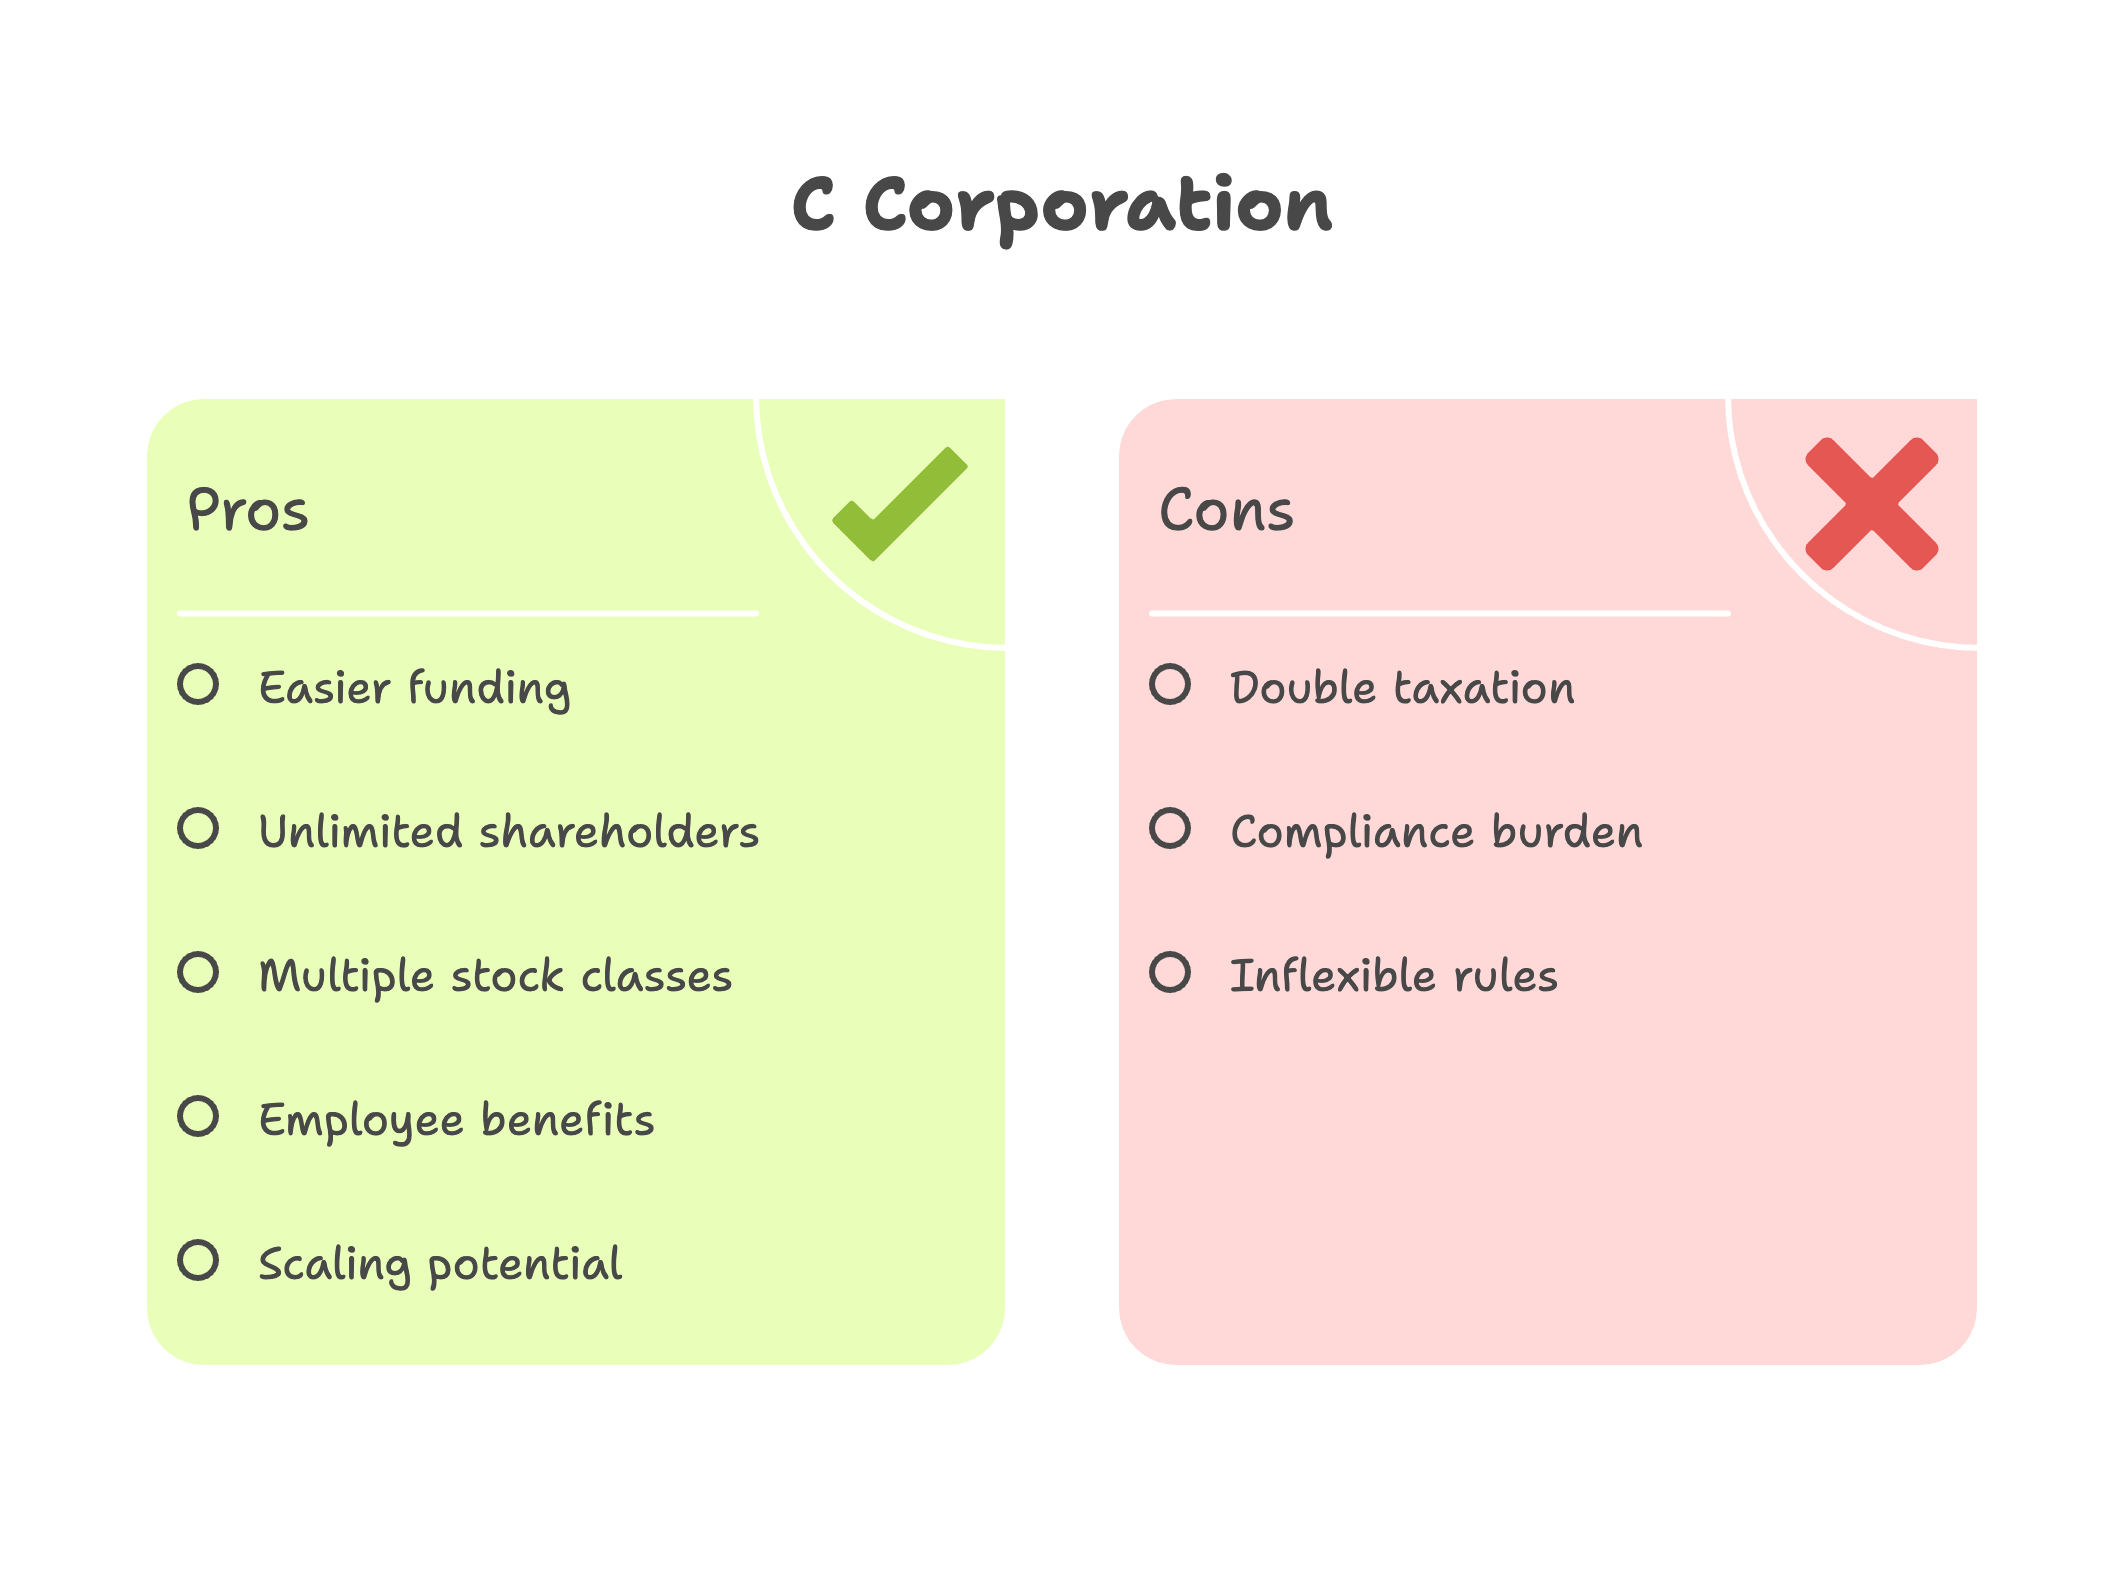
The double tax is easy to quantify. On $500,000 of profit, the corporation pays $105,000. If the remaining $395,000 is paid out as a qualified dividend to a top-bracket shareholder (20% plus the 3.8% net investment income tax), the second layer is about $94,010, for a combined rate near 39.8%. Retain the earnings instead and the effective rate stays at 21% until distribution, although large accumulations without a business need can draw the accumulated earnings tax.
Two OBBBA changes make the C corporation more competitive for growth companies. For stock issued after July 4, 2025, Section 1202 now excludes 50% of gain after three years, 75% after four and 100% after five. The per-issuer cap rose from $10 million to $15 million, and the gross-asset ceiling from $50 million to $75 million. Our guide to the qualified small business stock exclusion covers the active business requirement. Note that businesses in accounting, law, health, consulting and similar fields do not qualify, so QSBS is off the table for most professional practices. For a direct two-way comparison, see LLC vs C corp.
A general partnership needs no state filing; two people running a business together for profit already have one, which is the main problem. Every general partner is personally liable for partnership debts, including obligations created by the other partners.
A limited partnership has at least one general partner with unlimited liability and limited partners whose exposure is capped at their investment, provided they stay out of management. LPs remain common in real estate and investment funds, often with an LLC as the general partner. A limited liability partnership (LLP) protects partners from the malpractice of other partners and is widely used by accounting and law firms, though the scope of the shield varies by state.
All three file Form 1065 and pass income through on K-1s. A general partner's share of ordinary income is subject to self-employment tax, while a limited partner's distributive share generally is not (guaranteed payments for services are).
| Factor | LLC (default) | S corporation | C corporation | General / limited partnership |
|---|---|---|---|---|
| Federal return | Schedule C or Form 1065 | Form 1120-S | Form 1120 | Form 1065 |
| Entity-level federal tax | None | None (built-in gains tax can apply) | 21% | None |
| Owner limits | None | 100, US individuals and certain trusts | None | None (at least two partners) |
| Classes of ownership | Flexible | One class of stock | Multiple | Flexible |
| Owner payroll tax | SE tax on active members' profit | FICA on salary only | FICA on salary; dividends taxed separately | SE tax on general partners |
| Section 199A deduction | Yes | Yes | No | Yes |
| Section 1202 QSBS | No | No | Yes, if qualified | No |
| Liability shield | Yes | Yes | Yes | GP: no; LP: limited partners only |
| Typical fit | Small and mid-sized operators, real estate | Profitable owner-operators | Venture-backed, retained earnings, exit via stock sale | Funds, real estate, professional LLPs |
The 20% Section 199A deduction was set to expire after 2025. The OBBBA made it permanent, widened the phase-in range for the wage and property limits and for specified service businesses to $75,000 ($150,000 for joint filers), and added a $400 minimum deduction for taxpayers with at least $1,000 of qualified business income from active businesses, starting in 2026.
Under Rev. Proc. 2025-32, the 2026 threshold is $403,500 for joint filers, with the deduction fully phased out for specified service income at $553,500. For other filers the range is $201,750 to $276,750. A top-bracket owner of a qualifying non-service business who gets the full deduction pays an effective federal rate of 29.6% on that income, compared with roughly 39.8% for distributed C corporation profit.
Accounting is a specified service trade, so many CPA firm partners above the threshold lose the deduction entirely. That makes the S corporation payroll saving and the state pass-through entity tax (PTET) more important for practice owners than the 199A deduction.
State rules can reverse a federal conclusion. Points to check for every client:
When the client is the CPA firm itself, state accountancy law narrows the options. Most states follow the Uniform Accountancy Act model, which requires a simple majority of a firm's ownership, by votes and financial interest, to belong to licensed CPAs, and many limit the entity to a professional corporation, PLLC or LLP. Check the state board's rules before forming or admitting non-CPA owners. Private equity transactions generally use an alternative practice structure that splits the attest firm from the advisory business for this reason.
On the tax side, a partnership or LLP keeps flexible profit splits between partners, while an S corporation suits a firm with one or two owners who want to reduce payroll taxes. Because QSBS is unavailable and 199A often phases out, the C corporation rarely wins for a practice unless it plans to retain substantial earnings.
Changing structure later is possible but rarely free. Common moves:
Federal beneficial ownership reporting is no longer a formation step for domestic companies. FinCEN's beneficial ownership information page states that US companies are exempt, an exemption first adopted by interim final rule in March 2025 and finalized in August 2026. Our post on who must file BOI reports with FinCEN explains the rules that still apply to foreign entities.
There is no single answer, because it depends on profit level, how much is distributed and the owner's other income. Profitable owner-operators often do best as an S corporation, while companies that reinvest everything or plan a qualifying stock sale may favor a C corporation. Model at least three years of projections before deciding.
Yes. An eligible LLC files Form 2553 and is then treated as a corporation that has elected S status, while keeping its state-law LLC structure and operating agreement. It must then run payroll for working owners.
Typically when profit is high enough that the payroll tax saved on distributions exceeds the added cost of payroll, a separate return and state fees. The threshold moves with the reasonable salary for the owner's role, so a high-salary profession needs more profit to benefit.
Usually yes, since most institutional investors cannot or will not hold LLC interests that generate K-1s and unrelated business income. A C corporation also lets founders start the Section 1202 holding period on day one. Delaware is the common state of incorporation for these companies.
Review it whenever profit, ownership or exit plans change materially, and at least during annual planning. Law changes such as the OBBBA are also a trigger, as are moves into new states with different entity taxes.
Entity reviews take modeling hours that many firms struggle to find during busy season. Madras Accountancy supports CPA firms with tax preparation across 1040, 1065 and 1120 workflows, projections and entity comparison workpapers that your team reviews and signs. To scope support for your practice, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



