



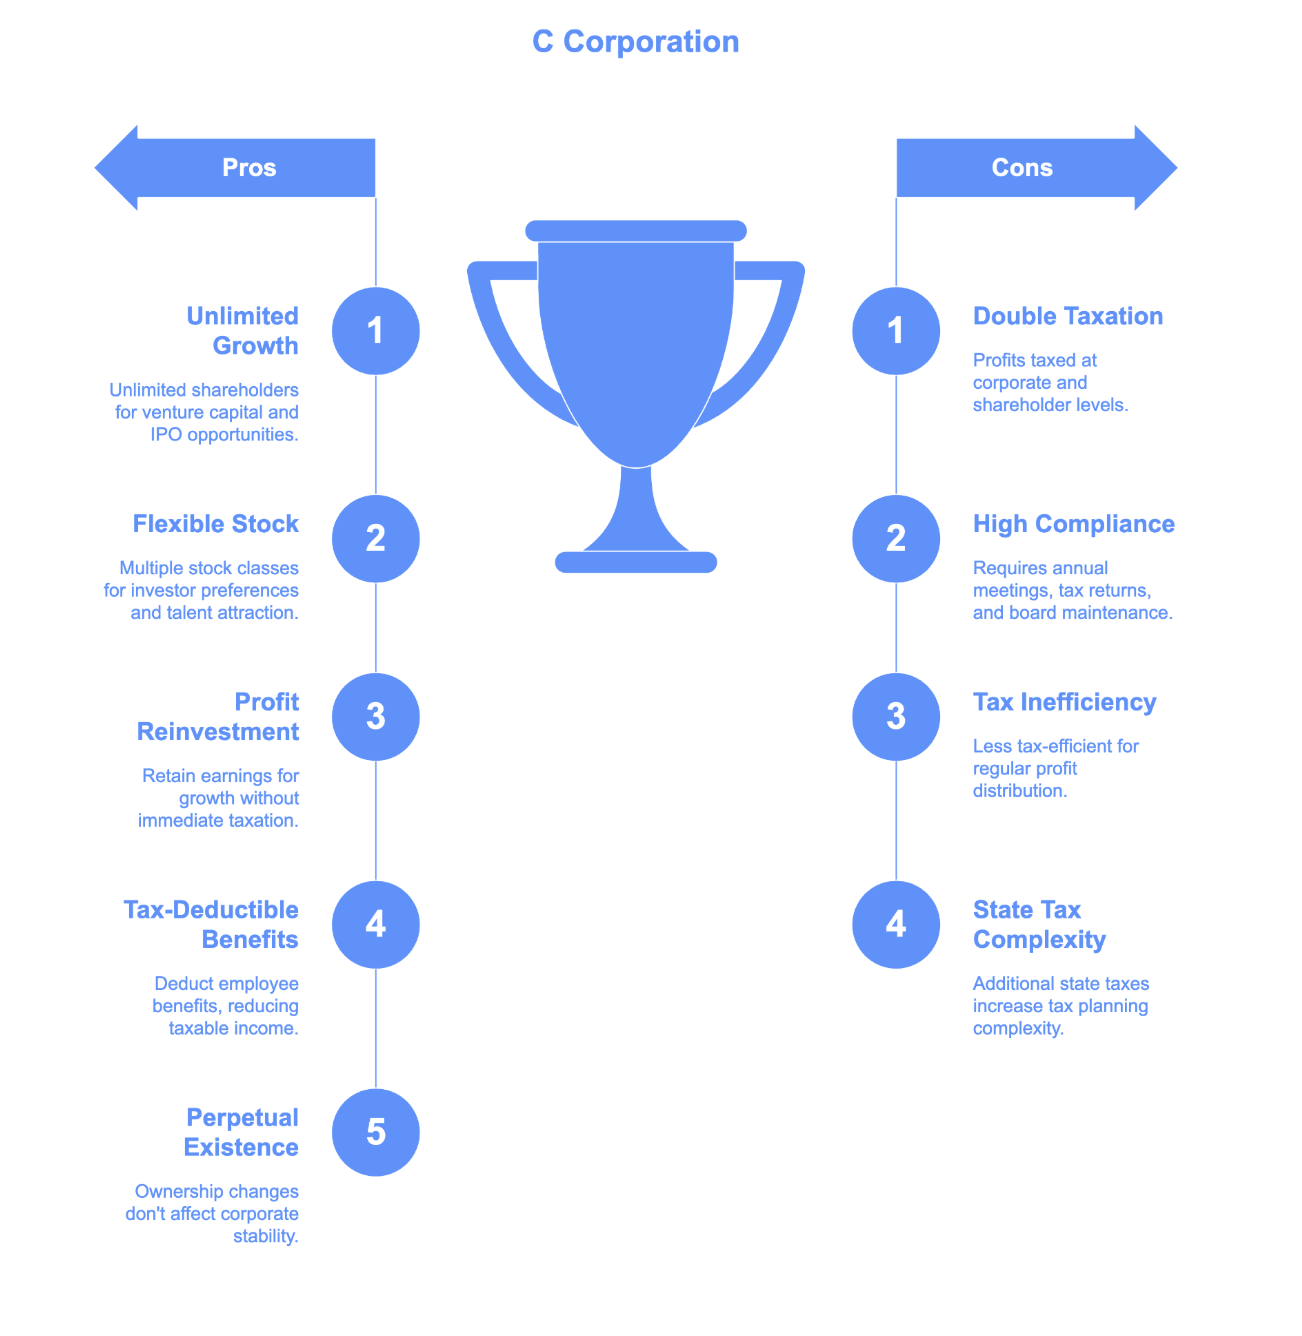
A C corp is a corporation that pays its own federal income tax, at a flat 21% of taxable income, separate from its owners. When it pays dividends, shareholders pay tax on them again on their personal returns. That second layer is the main cost of the structure. In exchange, a C corp can have any number of shareholders, issue several classes of stock, keep profits inside the company at the 21% rate, and qualify its founders for the qualified small business stock exclusion.
Every corporation formed under state law starts as a C corp for federal tax purposes. It stays one unless the shareholders file an S election. So the real decision for most founders is whether to keep C corp status or elect S status, and the answer turns mostly on who will own the shares and how much profit you expect to pay out each year. This guide covers how C corp taxation works in 2026, what the One Big Beautiful Bill Act changed, and how to compare a C corp with an S corp using real numbers.
A C corporation takes its name from Subchapter C of the Internal Revenue Code. You form it by filing articles of incorporation with a state, adopting bylaws, issuing stock, and electing a board of directors. The corporation is a separate legal person that holds its own assets and debts, which gives shareholders limited liability.
Federal tax treatment follows automatically. A corporation files Form 1120 each year and pays tax on its profit. An LLC can also choose to be taxed as a C corp by filing an entity classification election on Form 8832, which some owners use when they want corporate tax treatment while keeping an LLC's operating agreement. If you are still weighing an LLC against a corporation, our comparison of LLC and C corp structures covers the legal side in more depth.
Many startups incorporate in Delaware because investors know its corporate law. A Delaware corporation owes an annual franchise tax and report even if it operates elsewhere, so budget for the Delaware franchise tax requirements along with registration fees in the state where you actually do business.
The federal corporate rate is set by statute. Section 11 of the Internal Revenue Code says the tax "shall be 21 percent of taxable income", and that rate applies to the first dollar of profit and the last. There are no corporate brackets. The rate is permanent and did not change with the 2025 tax law.
The second layer arrives when the company distributes profit. Dividends from a domestic C corp are usually qualified dividends, which the IRS says are taxed at the lower capital gain rates. Those rates are 0%, 15%, or 20% depending on taxable income, and the IRS notes that a 20% rate applies above the 15% thresholds. For 2026, those thresholds are $545,500 of taxable income for single filers and $613,700 for married couples filing jointly, so many owners pay 15% on their dividends. Higher earners also owe the 3.8% net investment income tax on dividends once modified adjusted gross income passes $200,000 for single filers or $250,000 for married couples filing jointly.
Owners who work in the business can take salary instead of dividends. Salary is deductible to the corporation, though it carries payroll taxes and must be reasonable for the work performed. Most closely held C corps combine salary with retained earnings and pay dividends only when owners need the cash.
A C corp files Form 1120 by the 15th day of the 4th month after its tax year ends. The IRS instructions state that a corporation "must file its income tax return by the 15th day of the 4th month after the end of its tax year". For a calendar-year company, that is April 15. Our breakdown of the Form 1120 due date and filing tips covers extensions and fiscal-year math. Corporations that expect to owe $500 or more in tax for the year also make quarterly estimated payments.
Take a company with $400,000 of taxable profit after paying its owner a $100,000 salary. The assumptions:
C corp that keeps the profit. The company pays 21% of $400,000, or $84,000. The remaining $316,000 stays in the business, and the owner owes nothing more this year.
C corp that pays the profit out. The company still pays $84,000, then distributes $316,000 as a qualified dividend. The owner's taxable income becomes $399,900, below the $545,500 cutoff, so the whole dividend is taxed at 15%, or $47,400. The 3.8% net investment income tax applies to the $216,000 by which modified adjusted gross income of $416,000 exceeds $200,000, adding $8,208. Total federal tax is $139,608, an effective rate of about 34.9%.
S corp. The company pays no federal income tax. The full $400,000 flows to the owner's return, lifting taxable income to $483,900. Under the graduated brackets, that adds $124,964 of tax, an effective rate of about 31.2% on the profit. The top slice of the profit is taxed at 35%, and the rest at 22%, 24% and 32%.
| Federal tax on $400,000 of profit | C corp, profit retained | C corp, profit distributed | S corp |
|---|---|---|---|
| Entity-level tax | $84,000 | $84,000 | $0 |
| Owner's tax on the profit | $0 this year | $55,608 | $124,964 |
| Total federal tax | $84,000 | $139,608 | $124,964 |
| Cash left after tax | $316,000 in the company | $260,392 with the owner | $275,036 with the owner |
In this example the S corp saves about $14,600 when all profit is paid out. When the company reinvests most of what it earns, the C corp defers a large share of the tax, and that deferral compounds for as long as the money stays in the business. The gap shifts with income. A larger profit pushes more S corp income into the 35% and 37% brackets and more dividend income into the 20% band, so run the numbers at your own profit level.
Keeping profit inside a C corp is legal and common. The IRS does push back when a company stockpiles cash beyond its business needs to help shareholders avoid dividend tax. Section 531 imposes an accumulated earnings tax "equal to 20 percent of the accumulated taxable income" on corporations formed or used for that purpose.
The practical defense is documentation: board minutes that tie retained cash to specific plans, such as a facility purchase or a debt repayment. Our guide to the accumulated earnings tax walks through the minimum credit and the reasonable needs test.
The qualified small business stock exclusion under Section 1202 lets shareholders exclude some or all of the gain when they sell stock in a qualifying company. It only applies to C corp stock. The statute defines a qualified small business as "any domestic corporation which is a C corporation" that meets the asset test and other conditions.
The One Big Beautiful Bill Act, signed July 4, 2025, made this benefit much easier to use for stock issued after that date:
Example. A founder buys shares for $10,000 in March 2026, and the company stays under the asset limit. If she sells in April 2031 for $8,010,000, her $8,000,000 gain is fully excluded because she held the stock more than 5 years and the gain is under $15,000,000. If she sells in April 2029 instead, after 3 years, half the gain ($4,000,000) is excluded. The IRS notes that the taxable part of a Section 1202 gain is taxed at a maximum 28% rate.
Founders who receive restricted stock should pair this with a timely 83(b) election, which starts the holding period at grant. Our full guide to QSBS and the Section 1202 exclusion covers the active business test and excluded industries such as many professional service firms.
An S corp is a regular corporation that has elected pass-through taxation. The IRS lists the eligibility rules: the company must be domestic, have no more than 100 shareholders and only one class of stock, and its shareholders may be individuals, certain trusts, and estates. Partnerships, corporations, and nonresident aliens cannot hold S corp shares.
| Factor | C corp | S corp |
|---|---|---|
| Federal income tax at entity level | 21% flat | None (income passes through) |
| Tax on distributions | Qualified dividend rates plus 3.8% NIIT for higher earners | Generally none beyond the pass-through tax |
| Shareholder limit | Unlimited | 100 |
| Who can own shares | Anyone, including foreign persons and funds | U.S. citizens, resident aliens, certain trusts and estates |
| Classes of stock | Multiple, including preferred | One (voting differences allowed) |
| QSBS exclusion | Available | Not available |
| Owner salary rules | Must be reasonable to be deductible | Must pay reasonable compensation before distributions |
| Federal return | Form 1120 | Form 1120-S with K-1s |
S corp owners who work in the business must take a reasonable salary before taking distributions. Our guide to reasonable compensation for S corp owners explains how that salary is set. To switch from C to S status, shareholders file Form 2553 within the window the IRS allows, which is "no more than 2 months and 15 days after the beginning of the tax year" the election is to take effect. The steps are in our article on making an S corp election with Form 2553.
Foreign founders face a simpler choice. A nonresident alien cannot own S corp stock, so a company with even one nonresident shareholder cannot hold an S election. A C corp has no such restriction.
Foreign ownership brings its own filing duty. A U.S. corporation is a reporting corporation if it is 25% foreign owned, which the IRS defines as having "at least one direct or indirect 25% foreign shareholder at any time during the tax year". A reporting corporation files Form 5472 for transactions with related parties, and the instructions state that a "penalty of $25,000 will be assessed" for failing to file. Our Form 5472 filing guide explains which transactions count. Dividends paid to foreign shareholders can also carry U.S. withholding, so plan distributions with a tax adviser who knows the relevant treaty.
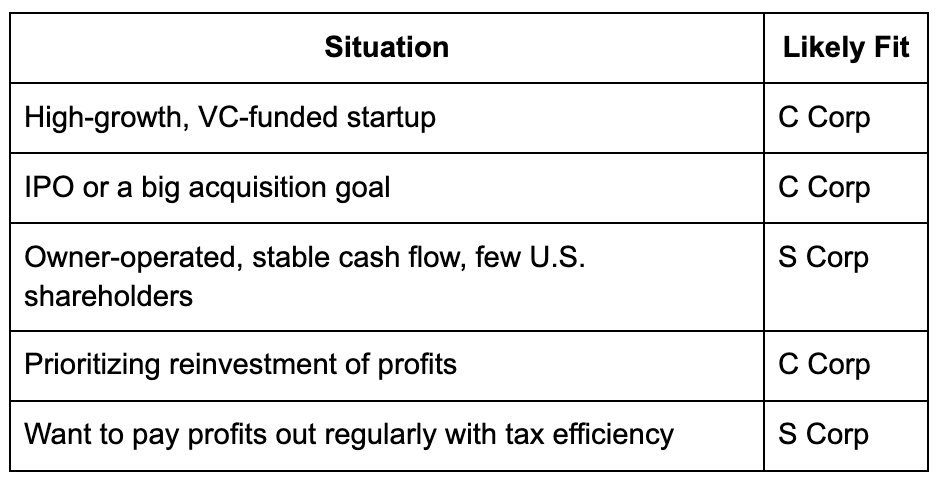
A C corp usually fits when one or more of these apply:
An S corp usually fits a profitable, owner-operated company with a small group of U.S. owners who take most profits out each year. Real estate investors face a different set of tradeoffs, because appreciated property held inside a corporation is hard to remove without tax, and our article on real estate C corporation setup covers those cases. For a wider view that includes partnerships and LLCs, see our business entity selection guide.
State taxes can change the answer, since most states tax C corp income at the entity level and some treat S corps differently. Run the numbers with your state rates before filing any election.
What is the C corp tax rate in 2026? The federal rate is a flat 21% of taxable income under Section 11, with no brackets. State corporate income tax applies on top in most states, and shareholders pay separate tax on any dividends they receive.
Can a C corp avoid double taxation? A C corp can reduce it by paying owners a reasonable salary, which is deductible, and by retaining profits for business use instead of paying dividends. Retained earnings above reasonable business needs can trigger the 20% accumulated earnings tax, so document the plans for any cash you hold.
Can a non-US citizen own a C corp? Yes. A C corp has no restrictions on shareholder residence or citizenship, unlike an S corp, which cannot have nonresident alien shareholders. A corporation that is at least 25% foreign owned must file Form 5472 for reportable related-party transactions.
Is an S corp or a C corp better for a startup raising money? Most venture investors require a C corp, because funds often cannot hold S corp stock and preferred shares would break the one-class-of-stock rule. A C corp also lets founders qualify for the QSBS exclusion, which can remove up to $15,000,000 of gain on stock issued after July 4, 2025.
Can a C corp switch to an S corp later? Yes, if it meets the eligibility rules, by filing Form 2553. A former C corp that converts can owe built-in gains tax if it sells appreciated assets within the recognition period, so review the asset values before electing.
Madras Accountancy supports U.S. businesses and CPA firms with corporate bookkeeping, Form 1120 preparation, and entity tax analysis. If you are deciding whether to keep C corp status or need help with a corporate return, contact our team to discuss your situation.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



