



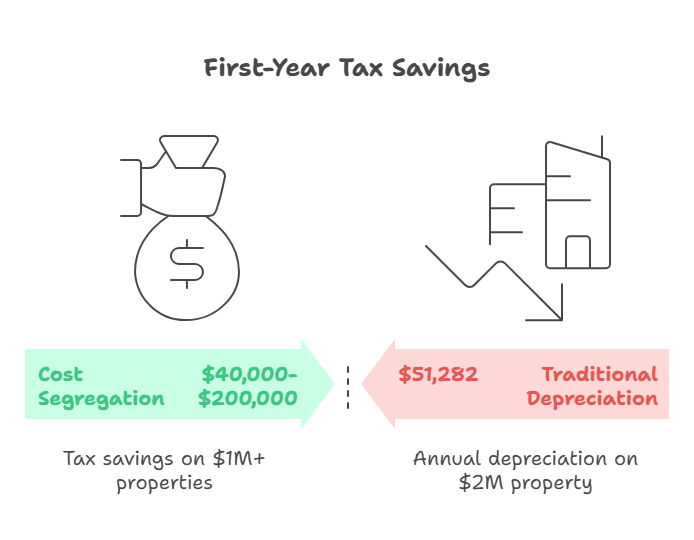
A cost segregation study identifies parts of a building that can be depreciated over 5, 7 or 15 years instead of 27.5 or 39. Under the One Big Beautiful Bill Act, those assets get permanent 100% bonus depreciation if acquired after January 19, 2025. The benefit is mainly timing, partly repaid through recapture on sale.
Without a study, a $2 million commercial building (excluding land) is depreciated over 39 years, roughly $51,000 a year. A study can move part of that cost into shorter recovery periods, which the IRS explicitly allows when the study is properly supported.
How much is reclassified depends entirely on the property; there is no standard percentage or guaranteed tax cut. Here's how it works, when it makes sense and what to weigh before ordering a study.
A cost segregation study is an engineering-based analysis that breaks a building's cost into components and reclassifies some of them from 27.5-year or 39-year property into 5-year, 7-year or 15-year property. Personal property and land improvements have shorter recovery periods than the building structure itself.
Items commonly reclassified include electrical and plumbing dedicated to specific equipment, specialty lighting, carpeting and some flooring, built-in cabinets and millwork, certain security and data systems, decorative finishes, parking lots, sidewalks, fencing and landscaping.
The study allocates your total cost basis across these classes. For a $2 million commercial building, a study might identify, say, $300,000 of 5- and 7-year property and $100,000 of 15-year land improvements, leaving $1.6 million as 39-year property. These amounts are illustrative only.
The benefit is timing. Standard depreciation spreads deductions over 27.5 years for residential rental property and 39 years for nonresidential property. Cost segregation moves deductions to the early years, which increases cash flow now.
Bonus depreciation makes the effect much larger. Under the One Big Beautiful Bill Act, 100% bonus depreciation is permanent for qualified property acquired after January 19, 2025. Property acquired before that date and placed in service in 2025 gets 40% (60% for certain longer-production-period property), and taxpayers may elect the lower rate for the first tax year ending after January 19, 2025. Qualified improvement property (interior improvements to nonresidential buildings) is also 15-year property eligible for bonus.
Illustrative example using the $2 million building above, acquired in 2026: without a study, first-year depreciation is roughly $51,000 (less in a partial first year). With the study, the $400,000 of 5-, 7- and 15-year property can be deducted in full, plus roughly $41,000 on the $1.6 million structure, for about $441,000 in year one. At an assumed 35% combined tax rate, the extra deduction of about $390,000 defers roughly $136,000 of tax. Your results will differ.
Section 179 can also apply to some building improvements, such as roofs, HVAC, fire protection and security systems on nonresidential property, within the 2026 limit of $2,560,000, phasing out above $4,090,000 of qualifying purchases. Manufacturers may also look at the new elective 100% deduction for qualified production property under Section 168(n).
The process starts with documentation: closing statements, blueprints, construction invoices, appraisals and improvement records. If original documents aren't available, the study team inspects the property, photographing and measuring components.
Engineers and tax specialists then classify assets using IRS guidance and case law. They separate personal property from structural components, identify land improvements and allocate costs using accepted methods.
The deliverable is a report documenting the basis allocation, recovery periods and methodology, with line-item detail. For a property placed in service in the current year, you simply use the study's classifications on that year's return. For a property placed in service in an earlier year, you generally file Form 3115 (Application for Change in Accounting Method) to switch to the new classifications.
Timing varies with property complexity and how quickly documents are available, so start well before your return is due.
Larger properties usually benefit most, because they contain more reclassifiable components and the study fee is spread over bigger deductions. Smaller properties can still benefit, especially now that reclassified assets are eligible for 100% bonus depreciation; run a preliminary estimate first.
Commercial properties often have the most short-life components: retail, office, medical, warehouse, hotel, restaurant and mixed-use buildings with extensive electrical systems, specialized finishes and significant site work.
Residential rental properties also benefit, particularly apartment complexes, student housing and properties with substantial amenities, appliances, flooring and site improvements.
Recently purchased or built properties offer the largest benefit. Properties you've owned for years can still benefit through a "look-back" study and Form 3115, which lets you claim missed depreciation as a catch-up adjustment in the current year.
Study fees vary with property size, complexity and documentation, and providers price differently. Get a fee quote and a preliminary benefit estimate before committing.
To judge whether a study is worthwhile, compare the fee with the present value of the tax deferral. Factors that matter:
Account for recapture. When you sell, depreciation on 5-, 7- and 15-year personal property (Section 1245 property) is generally recaptured as ordinary income, taxed at up to 37%. Depreciation on the building structure (unrecaptured Section 1250 gain) is taxed at up to 25%. Remaining gain is taxed at capital gains rates of up to 20%, plus the 3.8% net investment income tax where it applies.
Working with experienced providers matters. Our cost segregation accounting services cover the study and its tax implementation.
Cost segregation is well established. In Hospital Corporation of America v. Commissioner (1997), the Tax Court accepted that building components qualifying as tangible personal property can be depreciated separately. The IRS Cost Segregation Audit Techniques Guide (Publication 5653) describes how examiners review studies.
The guide describes several study approaches, from detailed engineering based on actual cost records to "rule of thumb" estimates with little documentation. Detailed engineering approaches are the most supportable on audit. A good report reconciles allocated costs to actual costs, lists Section 1245 property with amounts and includes photographs, drawings and an explanation of the methodology.
The study must show that reclassified items are truly personal property or land improvements, not structural components. For example, general building lighting is structural, while decorative or specialty fixtures may be personal property. HVAC serving the building is structural, while equipment serving a specific process may not be.
These distinctions require expertise. Our comprehensive tax planning strategies treat cost segregation as one part of a broader plan.
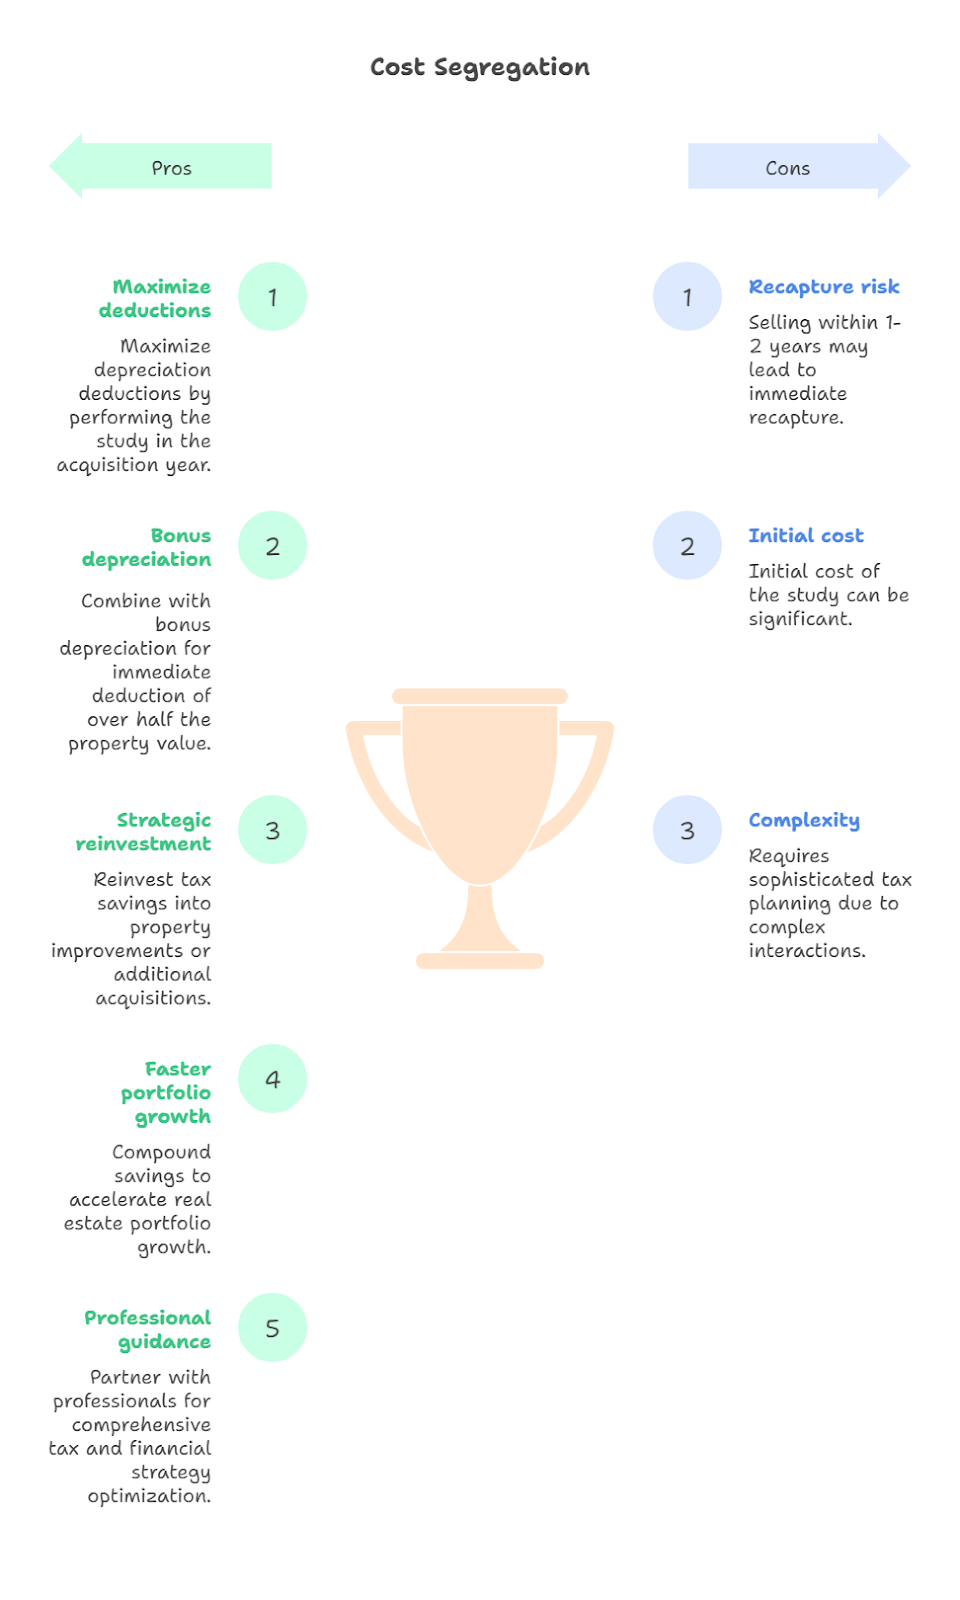
The main downside is recapture on sale: Section 1245 recapture at ordinary income rates, and unrecaptured Section 1250 gain at up to 25%. If you hold the property for years, the time value of the early deductions often outweighs this, but run the numbers.
Poorly supported studies create audit risk. The IRS scrutinizes reclassifications that aren't well documented or where personal property percentages look unusually high.
You may not be able to use the deductions right away because of the passive activity loss rules. If you are not a real estate professional, the $25,000 rental loss allowance phases out between $100,000 and $150,000 of modified AGI. Losses above what you can use carry forward, which reduces the time-value benefit.
For smaller properties, the study fee may exceed the benefit. Get a preliminary analysis first.
Timing matters. Ideally, order the study for the year you acquire or finish building the property. For older properties, a look-back study captures missed depreciation as a catch-up deduction in the current year.
With 100% bonus depreciation now permanent for property acquired after January 19, 2025, there is no longer a phase-down deadline to beat. The key question is whether you can use the deductions, given your income and the passive loss rules.
Plan around sales. If you expect to sell within a year or two, recapture comes quickly. A 1031 exchange can defer gain on the real property, but Section 1031 applies only to real property, so recapture on personal property identified in the study can still be triggered.
Use the cash flow deliberately: reinvest in improvements, acquire more property or pay down high-interest debt.
Look at the full picture. Cost segregation interacts with entity structure, passive activity rules, Section 163(j) interest limits and your holding strategy. Our fractional CFO services help real estate investors plan across these areas.
Consider a study if you own commercial or residential rental property with a substantial building basis, especially if you bought or built it recently.
New acquisitions offer the best opportunity. Older properties can still benefit from a look-back study with Form 3115, without amending prior returns.
Real estate professionals and owners of short-term rentals who materially participate can use the losses against other income. Passive investors still benefit from lower tax on rental income and can carry unused losses forward.
The break-even calculation is simple: if a study costs $10,000 and your combined tax rate is 35%, you need about $28,600 of additional first-year depreciation to recover the fee in year one ($28,571 x 35% = $10,000).
Madras Accountancy provides cost segregation support with engineers and CPAs, producing documentation designed to stand up to IRS review, through an offshore partnership model that keeps costs down.
Bottom line: cost segregation moves part of a building's cost into 5-, 7- and 15-year property. With permanent 100% bonus depreciation for property acquired after January 19, 2025, those amounts can often be deducted in year one. The benefit is mostly a deferral, so weigh it against recapture and your ability to use the losses.
Next steps:
Fees depend on property size, complexity and available documentation, and they vary by provider. Ask for a quote along with a preliminary estimate of the extra deductions, and compare the fee with the tax deferral at your marginal rate.
Yes. You file Form 3115 to change your accounting method, which generates a catch-up deduction in the current year for depreciation you could have claimed in prior years. You don't need to amend prior returns.
Depreciation on Section 1245 property identified in the study is generally recaptured as ordinary income (up to 37%). Depreciation on the building is taxed at up to 25%. A 1031 exchange can defer gain on the real property, but because Section 1031 covers only real property, recapture on personal property can still apply.
Yes, especially apartment complexes and properties with significant amenities. Appliances, carpet, certain fixtures and site improvements such as paving and landscaping can be reclassified into 5-, 7- or 15-year property.
There is no fixed minimum. It depends on how much can be reclassified, the study fee, your tax rate and whether you can use the losses. Ask for a preliminary analysis; if the expected first-year tax savings comfortably exceed the fee, it is usually worth doing.
A properly prepared study is a recognized practice, and the IRS publishes an Audit Techniques Guide describing what examiners look for. Poorly documented studies or aggressive reclassifications attract scrutiny. Use qualified engineers and CPAs who follow the methodologies the IRS describes.
Yes, but the passive activity loss rules may limit the immediate benefit. The $25,000 allowance for active participants phases out between $100,000 and $150,000 of modified AGI. Unused losses carry forward against future passive income or are released when you sell the property in a taxable transaction.
Madras Accountancy provides cost segregation services combining engineering analysis with CPA-level tax implementation, from the initial estimate through depreciation schedules, Form 3115 where needed and IRS documentation, through an offshore partnership model that keeps fees lower.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



