


A CPA for startup companies does three jobs a generalist tax preparer usually doesn't: sets up books that will survive investor due diligence, tracks the founder-specific tax deadlines that can't be fixed later, and claims the research incentives early-stage companies qualify for. Most of the expensive startup tax mistakes we clean up come from one of a handful of dates. An 83(b) election mailed on day 31. A Delaware franchise tax bill calculated on the wrong method. A research credit that could have offset payroll tax but was never elected.
What follows is what a startup CPA should be doing for you in 2026, which rules changed under the One Big Beautiful Bill Act of July 2025, and how to decide between an in-house hire and an outsourced team.
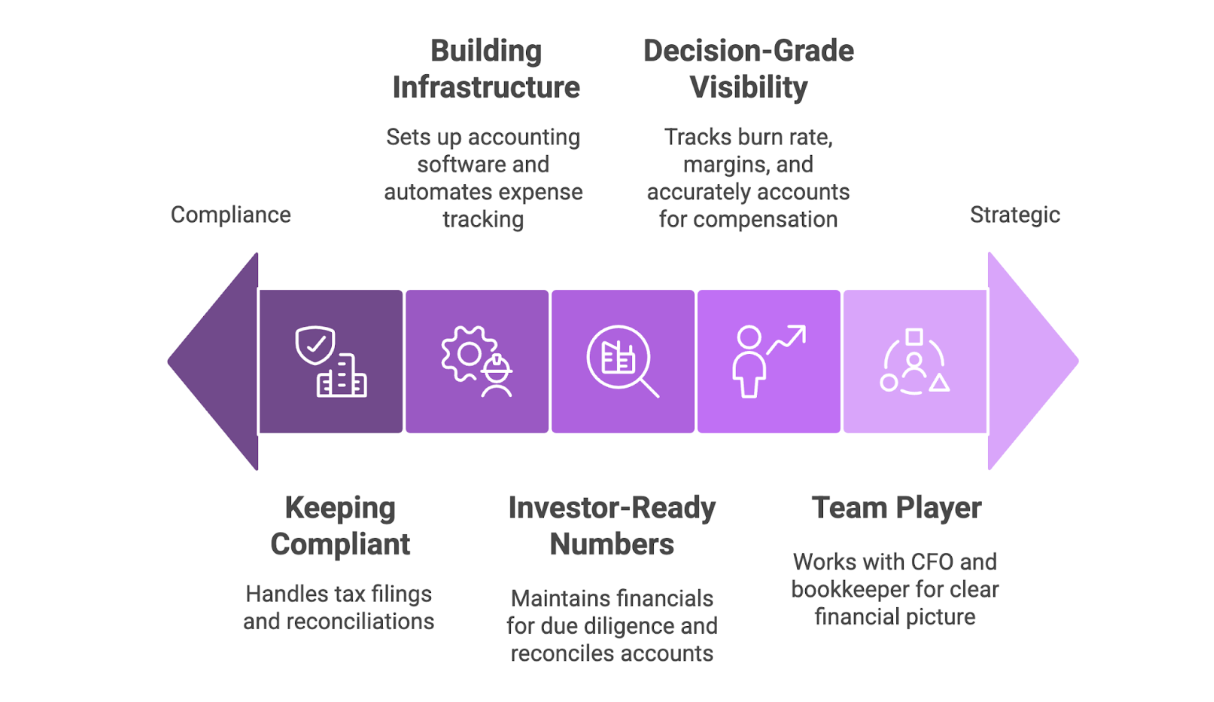
The work falls into four areas.
Accounting setup. Choosing the ledger (QuickBooks Online, Xero or NetSuite), building a chart of accounts that fits the business model, and connecting payroll, card and billing tools so transactions flow in daily. A SaaS company needs deferred revenue accounts from day one. A hardware company needs inventory and COGS tracking. Our startup accounting checklist for first-time founders walks through the setup in order.
Tax compliance. Federal and state income tax returns, payroll tax filings, 1099 reporting, sales tax where it applies, and state franchise taxes.
Tax planning. Equity elections, the research credit, the timing of expenses and the choice of entity and tax year. This is where a CPA earns their fee, since most of the value is created before the year closes.
Investor reporting. Monthly closes, GAAP-basis financial statements, burn and runway reporting, and support during due diligence or a first audit.
A bookkeeper covers daily transaction coding. A CPA signs off on the accounting and tax positions. A CFO owns forecasting, fundraising strategy and board reporting. Many startups need all three in small doses, which is why the distinction matters. Our comparison of a bookkeeper vs accountant vs CPA vs CFO explains who does what.
These are the federal and Delaware dates that matter most for a venture-backed C corporation on a calendar year. Your state adds its own.
| Item | Deadline | What happens if missed |
|---|---|---|
| Section 83(b) election | 30 days after restricted stock is transferred | Cannot be filed late; vesting shares become taxable as they vest |
| Form 1099-NEC to IRS and contractors | January 31 | IRS information return penalties |
| Delaware franchise tax and annual report | March 1 | $200 late annual report penalty plus 1.5% monthly interest on unpaid tax |
| Form 1120 (C corporation) | 15th day of the 4th month after year-end (April 15 for calendar year) | Late filing penalties; payroll R&D credit election lost for that year if return isn't timely |
| Form 941 payroll returns | Quarterly | Penalties; payroll R&D credit claimed here via Form 8974 |
When founders receive stock subject to vesting, an 83(b) election lets them be taxed on the value at grant (often close to zero at formation) instead of on the value as each tranche vests. The IRS instructions for Form 15620 state that the election must be filed no later than 30 days after the property is transferred and must be submitted by mail. A copy also goes to the company. Form 15620 is optional; a written statement meeting Treasury Regulation 1.83-2 still works. The election can't be revoked without IRS consent.
A CPA should calendar the date of every restricted stock grant, prepare the election the same week and keep the certified mail receipt in the corporate records. Our article on how the 83(b) election works for founders covers the valuation side.
Most venture-backed startups are Delaware corporations, and the franchise tax notice frequently alarms founders. According to the Delaware Division of Corporations, the tax and annual report are due by March 1. The minimum tax is $175 under the Authorized Shares method and $400 under the Assumed Par Value Capital method, plus a $50 annual report fee, with a $200,000 cap for most filers. A company with millions of authorized shares can receive a very large bill under the default method that drops sharply when recalculated under the Assumed Par Value Capital method using its gross assets. See our full guide to Delaware franchise tax requirements for the calculation.
Startups with little or no income tax can still benefit from the research credit. The Form 6765 instructions define a qualified small business as one with gross receipts under $5 million for the year and no gross receipts in any year before the five-year period ending with that year. Such a company can elect to apply up to $500,000 of its research credit against the employer share of payroll taxes.
The mechanics trip people up:
A pre-revenue company with $800,000 of engineering payroll that misses the Form 1120 deadline loses the payroll election for that year, even if the credit itself is valid. Our guide to maximizing R&D tax credits covers which activities and costs qualify.
From 2022 through 2024, companies had to capitalize research and experimental costs, including software development, and amortize them over five years (15 years for foreign research). The One Big Beautiful Bill Act added Section 174A, which, as summarized in Rev. Proc. 2025-28, allows an immediate deduction for domestic research or experimental expenditures paid or incurred in tax years beginning after December 31, 2024. Software development costs count as research expenditures. Foreign research is still amortized over 15 years.
Eligible small businesses could also elect to apply the new rules back to 2022, but Rev. Proc. 2025-28 set that election deadline at July 6, 2026, so it has passed. Companies that missed it should ask their CPA about the separate transition options for remaining unamortized amounts. Our article on how the One Big Beautiful Bill Act changed Section 174 has the detail.
1099 threshold. For payments made in 2026 and later, the IRS raised the reporting threshold for nonemployee compensation on Form 1099-NEC and several other payment types from $600 to $2,000, with inflation adjustments possible from 2027. Gross proceeds paid to attorneys still use a $600 threshold. See our 1099-NEC and 1099-MISC filing requirements for the details.
Beneficial ownership reporting. FinCEN now exempts all entities created in the United States from BOI reporting under the Corporate Transparency Act. Only foreign companies registered to do business in a US state still file.
State nexus. Hiring a remote employee in a new state usually creates payroll registration and often income tax filing obligations there. Selling software or goods across state lines can trigger sales tax once you pass a state's threshold. Our explainer on economic nexus for growing businesses lists what to check.
Investors and acquirers test the quality of your numbers long before they test your product. A startup CPA should make sure:
Our checklist for preparing startup finances for investor due diligence lists what buyers and lead investors typically request.
The cleanup projects we see most often trace back to a short list of habits formed in the first year.
Founders paying company costs personally. Software, travel and contractor invoices paid on a founder's card and never reimbursed leave the company's expenses understated and the founder holding undocumented deductions. Set up a written reimbursement policy and run every expense through the company.
Cash-basis books at fundraising time. Cash-basis records are fine for a very early company, but investors expect accrual-basis statements that show deferred revenue, accrued payroll and unpaid bills. Converting two years of history under deadline pressure is slow and expensive.
Research costs with no paper trail. The research credit depends on records showing who worked on which qualified project and for how long. Reconstructing that from memory a year later produces weaker claims. Time tracking by project from the first engineering hire makes the credit far easier to support.
Contractors who look like employees. Treating full-time, company-directed workers as contractors can lead to back payroll taxes and penalties. A CPA should review worker classification before the first offer letters go out.
No one owning the calendar. Most missed deadlines happen because the founder assumed the bookkeeper, the lawyer or the payroll provider was tracking them. Your CPA should own a single compliance calendar.
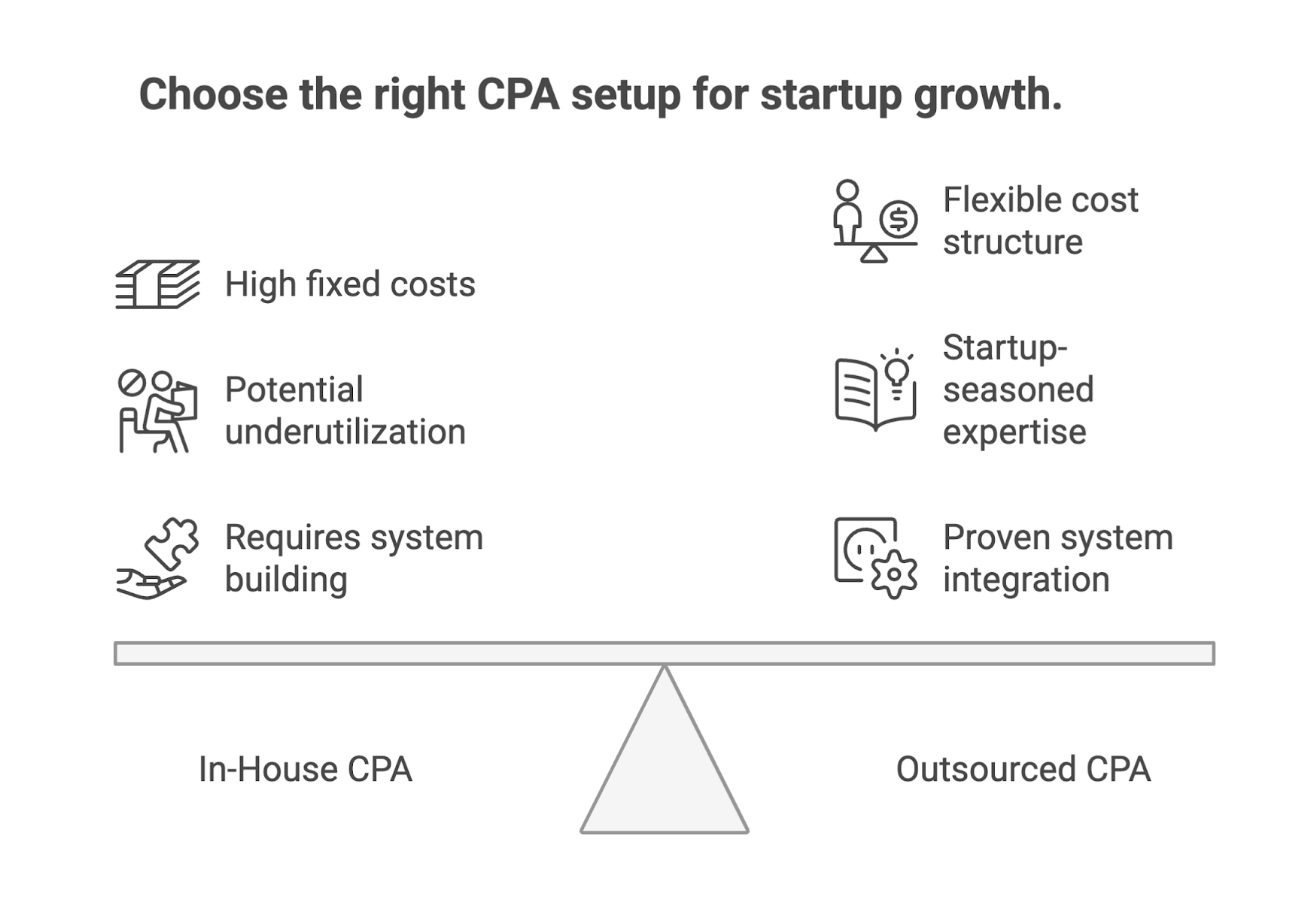
The Bureau of Labor Statistics reports that the median annual wage for accountants and auditors was $83,680 in May 2025, before benefits and employer payroll taxes. An experienced startup accountant in a major tech hub will usually cost more, and one person rarely covers bookkeeping, tax and CFO work equally well.
| Stage | Typical setup |
|---|---|
| Formation to first revenue | Outsourced bookkeeping plus a CPA for formation, 83(b) elections and the first returns |
| Seed to Series A | Outsourced accounting team with monthly closes, R&D credit work and part-time CFO support for fundraising |
| Post-Series A, high transaction volume | First in-house finance hire (controller or senior accountant), with tax still outsourced |
| Pre-audit or pre-acquisition | In-house controller plus outside CPA support for audit readiness |
An outsourced team gives you access to tax, accounting and CFO skills without paying three salaries, which suits most companies until transaction volume justifies a full-time hire. Our breakdown of what it costs to outsource accounting services shows the pricing models, and our article on a virtual CFO for startups explains when to add CFO support.
Ask these questions before signing an engagement letter:
Strong answers name specific forms, tools and deadlines. Vague answers about "full-service support" usually mean the firm hasn't done this work often.
When should a startup hire a CPA? At formation, ideally before founders receive restricted stock, so 83(b) elections are filed on time and the books start clean. If you have already incorporated without one, bring a CPA in before your first tax return or your first priced round, whichever comes first.
Does a pre-revenue startup need to file a tax return? Yes. A C corporation files Form 1120 every year it exists, even with no revenue. Filing on time also preserves the ability to elect the payroll research credit for that year.
How much does a CPA for a startup cost? Fees depend on transaction volume, the number of states you operate in and whether you need monthly accounting or only annual tax work. Ask for a fixed monthly quote that lists exactly what is included, including R&D credit studies and state filings.
Can a CPA help with our first financial statement audit? Yes, by preparing the reconciliations, schedules and documents the auditor will request. Many startups use one firm for monthly accounting and a separate firm for the audit, so ask early how the two will work together and what independence rules apply.
Should a startup use a CPA or just tax software? Tax software can file a simple return, but it won't flag a missed 83(b) election, calculate a Delaware franchise tax on the cheaper method or make the payroll research credit election. For a company with investors, those misses cost far more than the fee.
Madras Accountancy provides outsourced bookkeeping, tax and CFO support for US startups and the CPA firms that serve them. If your books need to be investor-ready or you want a second look at your 2026 tax position, contact our team.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



