

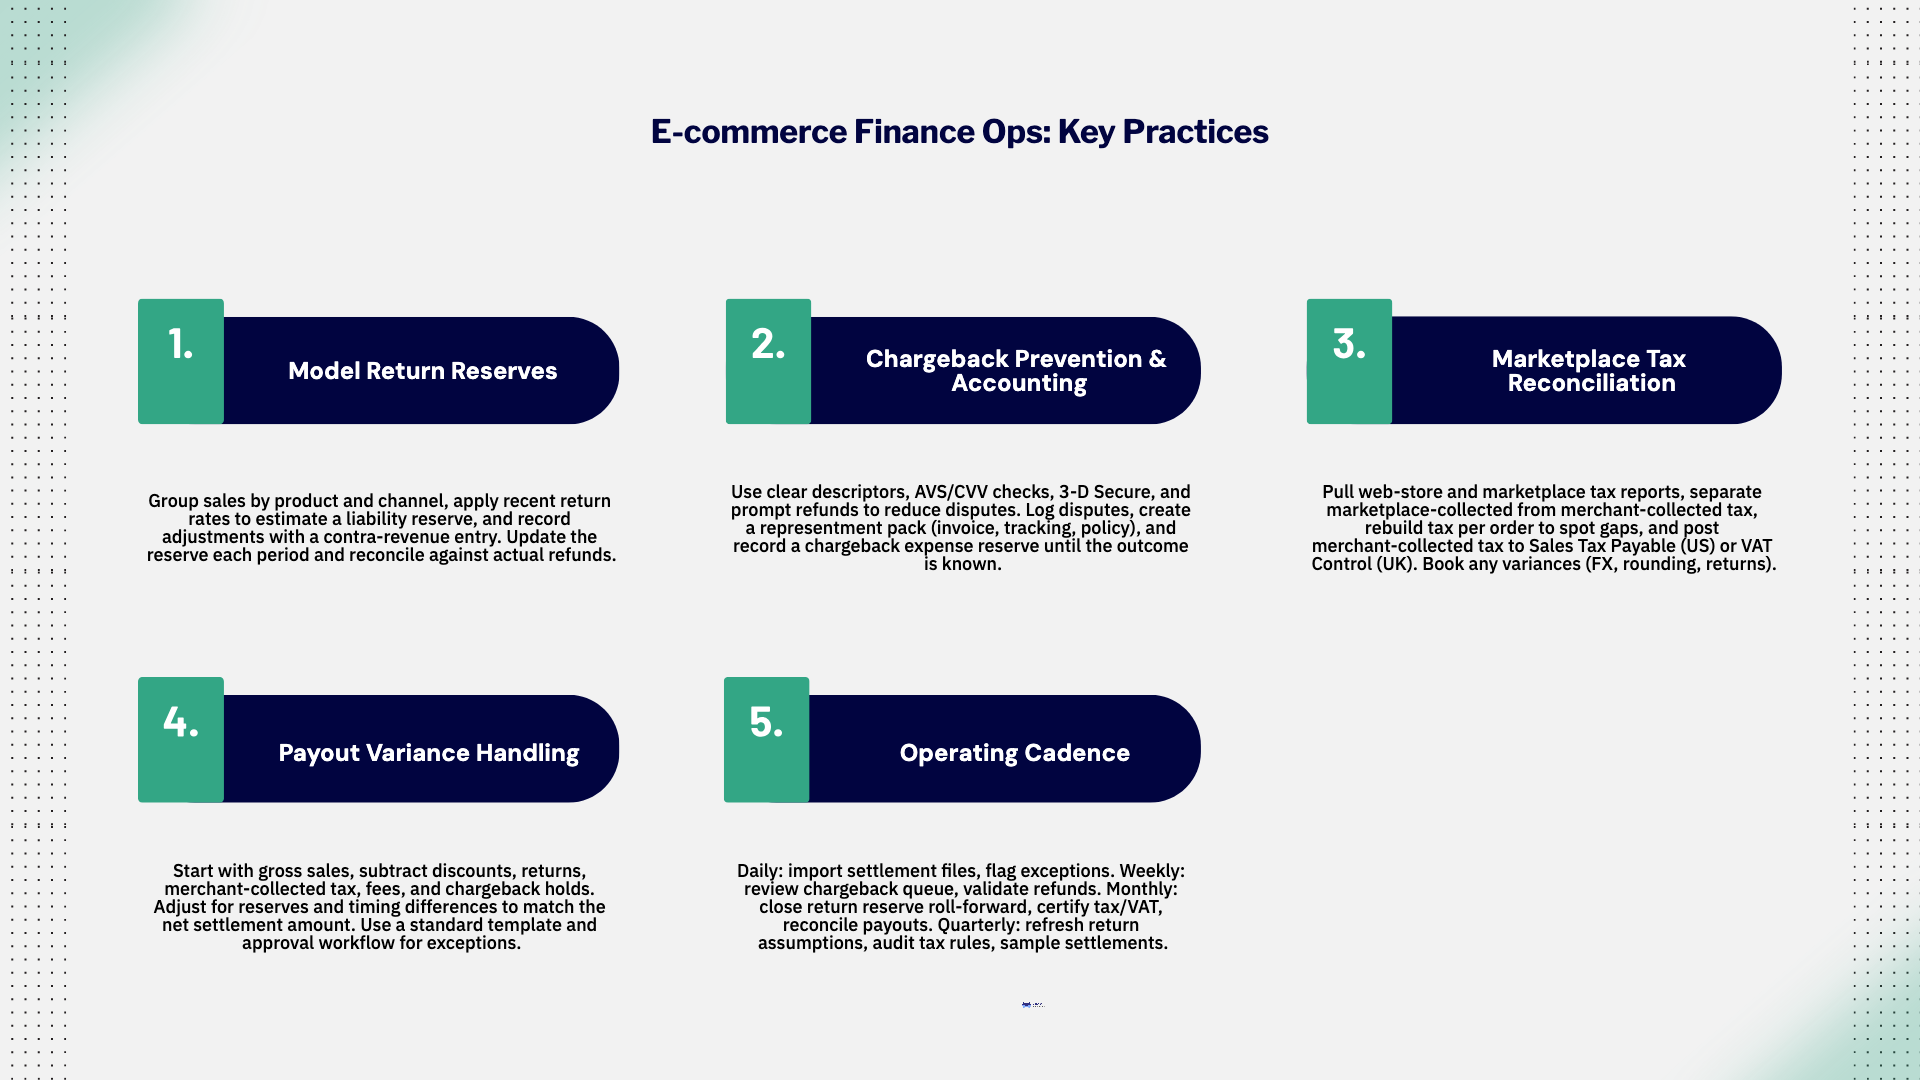

Ecommerce returns accounting under US GAAP means recording each sale net of the refunds you expect, with a refund liability for the cash you will pay back and a return asset for the goods you expect to get back. Chargebacks and the sales tax on refunded orders then run through the same monthly routine so that net revenue and tax payable tie to the orders customers actually kept.
This guide covers ecommerce returns accounting for online sellers and the CPA firms that close their books. It walks through the ASC 606 entries, a worked returns reserve for two product cohorts, a chargeback reserve, and how sales tax refunds on returned orders flow back to your filings. Sales tax reconciliation across channels is covered in depth in our separate guide, so this page focuses on the returns and disputes side of the ledger.
ASC 606 treats a return right as variable consideration. At the point of sale you do not book the full order value as revenue. Under ASC 606-10-55-23, as summarized in PwC's Viewpoint guide on rights of return, a seller recognizes three things:
The return asset is measured at the carrying amount of the goods at the time of sale, reduced by any expected costs to recover the goods and any expected reduction in their value. Prepaid return labels and inspection labor both reduce the asset. Goods that come back unsellable reduce it further, and an asset for items you expect to scrap may be impaired from day one.
Both balances are estimates. PwC's summary notes that the refund liability is remeasured at each reporting date, with the change recorded against revenue, and the asset is updated whenever the liability changes. The return asset is also presented separately from the refund liability on the balance sheet, so you cannot net them into a single "returns reserve" line.
Two related points matter for online stores. An exchange of one product for another of the same type, quality, condition and price is not a return under the standard, so size swaps do not touch the refund liability. A right to exchange a defective item is treated as a warranty, which sits outside the returns model. The refund liability is also distinct from a contract liability such as deferred revenue, because it represents cash owed back to the customer. A contract liability represents goods or services still to be delivered.
The estimate is only as good as the data behind it. A workable method for most online sellers looks like this.
The expected value method usually fits ecommerce, since you have many similar orders and a stable history. Document the cohorts, the lookback window and the reason code report in a short methodology memo, and refresh the assumptions at least quarterly.
A retailer closes October with $500,000 of eligible web store sales, excluding sales tax, in two cohorts. All figures are illustrative.
| Cohort | Sales | Expected return rate | Refund liability | Cost ratio | Carrying amount of expected returns | Recovery costs | Expected value loss | Return asset |
|---|---|---|---|---|---|---|---|---|
| Apparel | $300,000 | 18% | $54,000 | 45% | $24,300 | $2,000 | $2,430 (10%) | $19,870 |
| Home goods | $200,000 | 6% | $12,000 | 50% | $6,000 | $600 | $1,200 (20%) | $4,200 |
| Total | $500,000 | $66,000 | $30,300 | $2,600 | $3,630 | $24,070 |
The refund liability is sales times the expected return rate, assuming full cash refunds. The return asset starts from the carrying amount of the expected returns (the refund liability times the cost ratio), then subtracts recovery costs and the expected loss in value.
The summary entries for the month are:
Inventory leaves the books at its full cost of $235,000, which is $135,000 for apparel plus $100,000 for home goods. Cost of sales is reduced by the return asset, giving $210,930. Net revenue of $434,000 less cost of sales of $210,930 leaves a gross margin of $223,070, or 51.4% of net revenue. The $6,230 difference between the $30,300 carrying amount and the $24,070 asset is the expected cost of handling returns plus the expected loss in value, and it stays in cost of sales.
In November, refunds paid against October sales are charged to the refund liability and returned goods are moved from the return asset back into inventory at their assessed value. If the October return window closes with actual refunds of $61,500, the remaining $4,500 of refund liability is released to revenue, and the return asset is trued up in the same entry. Units that come back damaged belong with your inventory shrinkage accounting and write-off process.
The cost ratio in this example depends on how you value inventory. Our guide to ecommerce inventory accounting and COGS methods explains how FIFO, weighted average and landed cost choices flow into that number.
The book reserve and the tax return do not move in lockstep. For a sole proprietor or single-member LLC filing Schedule C, the IRS Schedule C instructions say to report sales returns and allowances as a positive number on line 2, and define a sales return as "a cash or credit refund you gave to customers who returned defective, damaged, or unwanted products." That wording refers to refunds you gave. A book reserve for refunds you expect to give in a later period is an estimate, so the timing of the tax deduction for it needs separate review by the preparer, and the difference often shows up as a book-to-tax adjustment.
A chargeback starts when a cardholder disputes a payment with the bank that issued the card. For consumer credit cards, federal law gives the cardholder a formal path. Under Regulation Z, 12 CFR 1026.13, a billing error includes a charge for property or services "not accepted by the consumer" or "not delivered to the consumer or the consumer's designee as agreed," and the consumer's notice must reach the card issuer no later than 60 days after the first periodic statement that shows the charge. Card network rules then set the merchant side of the process.
On the cash side, the processor pulls the money before the case is decided. Stripe's documentation on how disputes work states that it "debits the disputed amount, plus a dispute fee" from the merchant's account, that card networks typically allow disputes within 120 days of the original payment, and that merchants usually have 7 to 21 days to respond. Stripe also notes that for businesses outside Mexico the fee for receiving a dispute is non-refundable even if the merchant wins. Check your own processor's terms, because fees and timelines vary.
Many sellers treat disputes over non-delivery or damaged goods as an extension of the returns model, since the customer ends up with a refund, and treat fraud losses and dispute fees as operating expense. Pick a policy, document it, and apply it consistently from month to month.
At month end, open disputes and expected future disputes on current-period sales both need an estimate. Suppose the same retailer expects 24 disputes from October card sales, with an average disputed amount of $90 and a historical win rate of 25%. It expects to lose 18 disputes, which is $1,620 of lost sales. With an assumed $15 non-refundable fee per dispute, fees add $360. The October chargeback reserve is $1,980. Refit the dispute rate and win rate each quarter using processor reports by reason code.
Prevention lowers the reserve directly. Clear billing descriptors, delivery confirmation for physical goods, 3D Secure on higher-risk orders and fast refunds for genuine complaints all reduce how many disputes reach the formal stage.
Sales tax you collect sits in sales tax payable and is never part of revenue, so it stays out of the refund liability calculation above. When a customer returns an order and you refund the tax along with the price, the entry is Dr Refund Liability for the price, Dr Sales Tax Payable for the tax, Cr Cash. If a customer returns a $120 item taxed at 8%, the $129.60 refund splits into $120 against the refund liability and $9.60 against sales tax payable.
State rules decide whether you can take a deduction on the sales tax return. California is a useful reference point. Under CDTFA Regulation 1655, the amount on which tax is computed does not include merchandise returned by customers if "the full sale price, including that portion designated as 'sales tax', is refunded either in cash or credit," and the customer is not required to purchase other property at a price greater than the amount charged in order to get the refund. A restocking fee may be withheld, but it "may not exceed the actual cost of rehandling and restocking." Other states set their own rules, so check each state where you file.
A few practical points follow for ecommerce returns accounting:
For the full monthly tie-out between your tax engine, marketplace reports and the general ledger, see our guide to sales tax reconciliation for ecommerce clients. Subscription sellers that issue credit notes instead of physical returns face a different set of issues, covered in our article on SaaS billing sales tax and ASC 606.
Is a returns reserve the same as a refund liability? In everyday use the terms overlap, but ASC 606 splits the idea into two balances. The refund liability covers the cash you expect to pay back, and a separate return asset covers the goods you expect to recover, presented apart from the liability.
Should expected returns reduce revenue or be booked as an expense? Under ASC 606, expected refunds reduce revenue, because revenue is recognized only for the consideration you expect to be entitled to. The cost of goods you expect to recover is moved out of cost of sales into the return asset.
How often should the return rate assumptions be updated? The refund liability is remeasured at each reporting date, so the estimate should reflect current data every month end. Most sellers refit the full cohort model at least quarterly and after policy changes such as a longer holiday return window.
Can I deduct sales tax on a returned order if I charged a restocking fee? In California, Regulation 1655 still treats the refund as complete when a restocking fee is withheld, provided the fee does not exceed the actual cost of rehandling and restocking. Other states have their own rules, so confirm before claiming the deduction.
Are chargeback fees refunded if I win the dispute? It depends on your processor. Stripe, for example, states that the fee for receiving a dispute is non-refundable for businesses outside Mexico, while a separate dispute countered fee is returned if you win.
Madras Accountancy supports online sellers and CPA firms with ecommerce bookkeeping, month-end close, returns and chargeback reconciliations, and sales tax workpapers. To discuss your returns process or close calendar, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



