

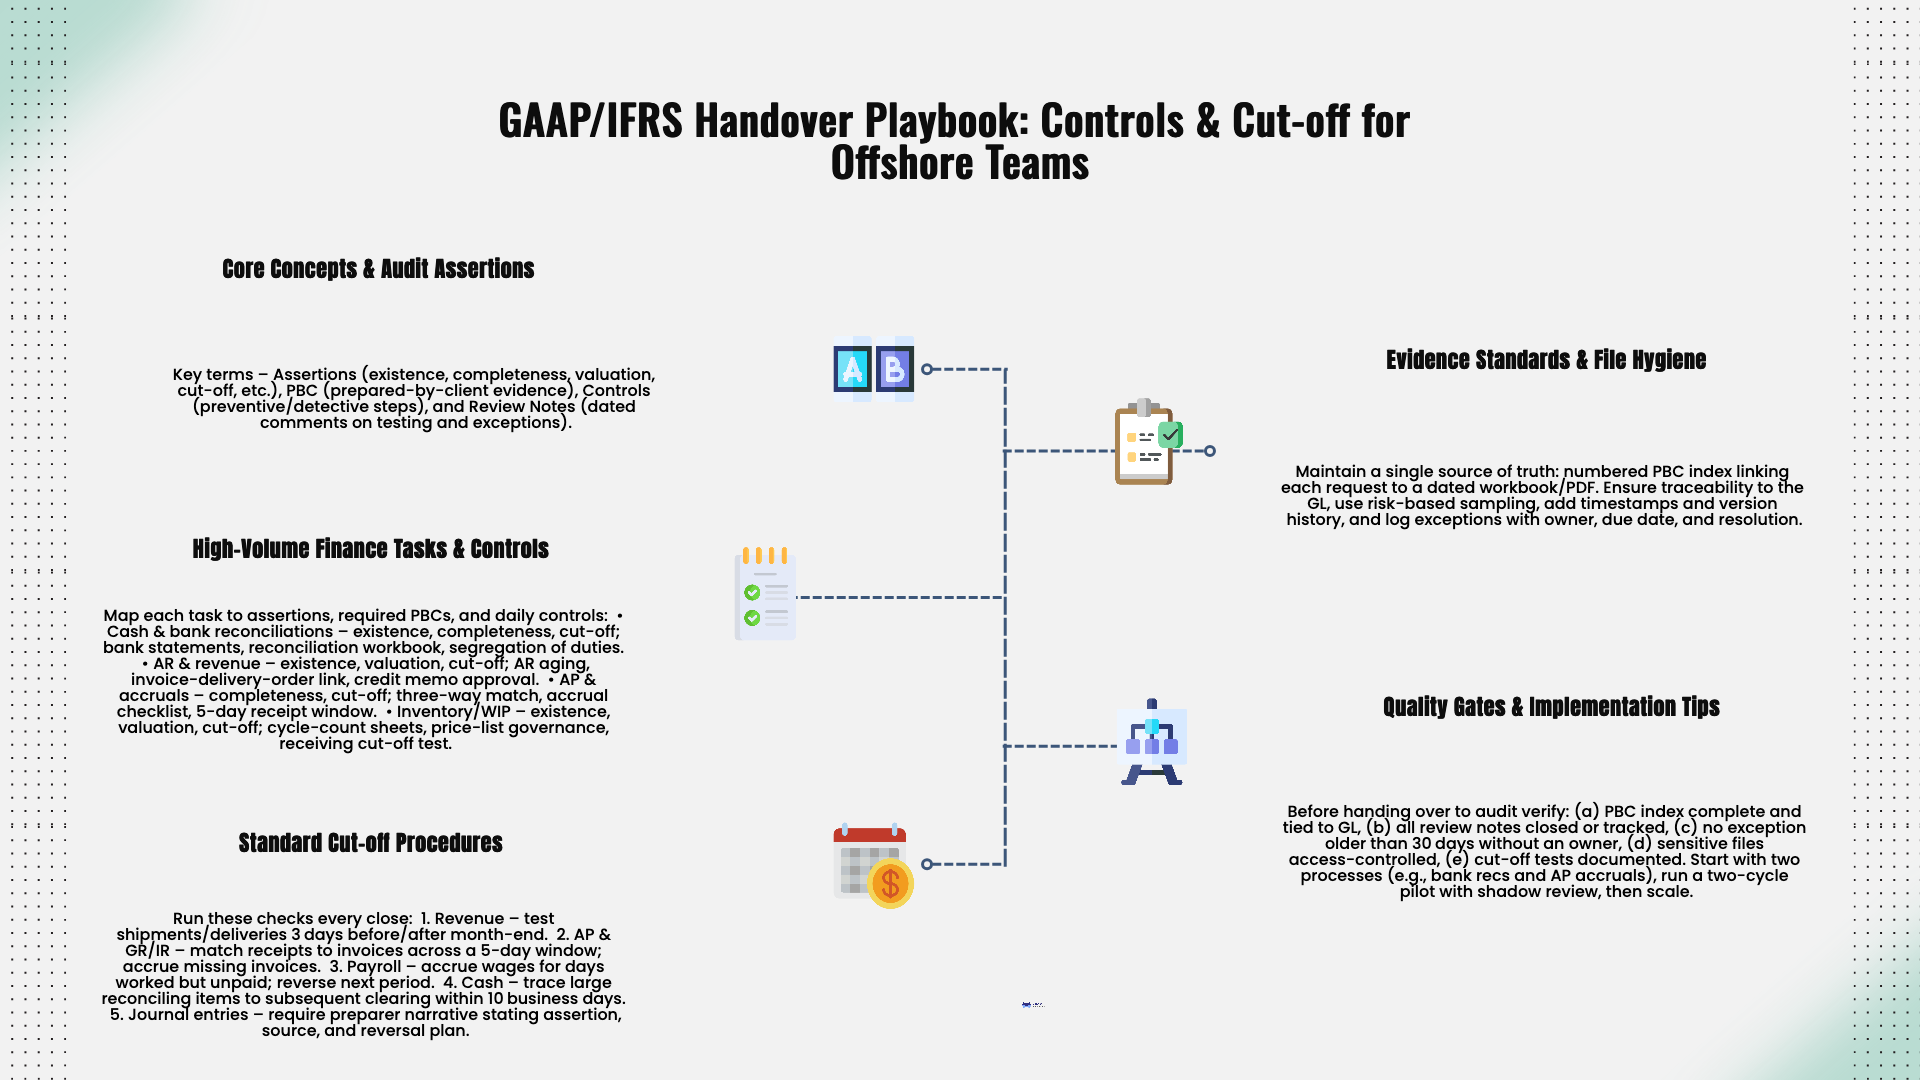

Cut-off procedures are the tests that make sure every receipt, shipment, invoice and hour worked lands in the period it belongs to. When an offshore team takes over month-end close, those procedures need to be written down as step-by-step SOPs with fixed test windows, evidence requirements and an onshore reviewer who signs off before the books are locked.
This playbook shows how to hand cut-off procedures and related close controls to an offshore team under US GAAP or IFRS, including the evidence auditors expect and the framework differences that change period-end entries.
Cut-off is an assertion auditors test on almost every balance sheet account. Errors usually cluster in the last few days before month-end and the first few days after, when goods arrive before the invoice, invoices arrive before the goods, or staff work days that are paid in the next payroll run.
For an offshore team, the risk is highest in the first few cycles, before the team learns which vendors invoice late or which projects bill in arrears. Good SOPs replace that local knowledge with explicit rules. If you are setting up the wider close calendar at the same time, the monthly close checklist 5 day plan with AP, AR and reconciliation SOPs shows how these tests slot into a day-by-day schedule.
The core vocabulary every handover document should define:
Each procedure below should appear in the SOP with an owner, a test window, a sample rule and the evidence file name. The windows shown are common starting points; adjust them for volume and materiality.
Revenue cut-off. Pull shipments, delivery confirmations or service acceptance records for 3 business days before and after month-end. Compare the delivery or acceptance date with the invoice date and the revenue posting period. Correct any item recognized in the wrong month with a dated journal entry.
AP and goods received not invoiced (GRNI). Match receiving records to vendor invoices across a 5-day window around month-end. Where goods or services were received and no invoice has arrived, book an accrual and set it to reverse on day one of the next period. Where an invoice was posted for goods not yet received, move it out of the period.
Payroll. Accrue wages for days worked but unpaid at period end. Reverse the accrual after the first payroll of the new month.
Cash. Trace large reconciling items on each bank reconciliation to clearing in the following period, typically within 10 business days. Escalate items older than 30 days to the process owner.
Inventory receiving. Goods on the receiving dock at month-end are either recorded in both inventory and payables or excluded from both, depending on whether control has passed under the shipping terms.
Journal entries. Every cut-off entry needs a preparer narrative that states the assertion addressed, the data source, the amount calculation and the reversal plan.
Assume a US company closes September on Wednesday, 30 September 2026. The offshore analyst runs the cut-off procedures above and finds the following.
| Item | Finding | Calculation | Entry |
|---|---|---|---|
| Payroll | Biweekly gross payroll of $84,000 covers 10 working days. Last pay period ended Friday, 25 September. Staff worked Monday 28 to Wednesday 30 September unpaid. | $84,000 / 10 x 3 days | Accrue $25,200 wages expense, reverse in October |
| GRNI | Two receipts on 29 and 30 September with no invoice: $18,400 materials and $6,250 freight | $18,400 + $6,250 | Accrue $24,650, reverse in October |
| Revenue | One shipment of $42,000 invoiced 30 September, delivered 2 October under terms where control passes on delivery | Full invoice moves to October | Reverse $42,000 revenue and receivable in September, and move the related cost of sales back to inventory |
The reviewer checks each line against source evidence. The review note might read: "Agreed payroll accrual to calendar, 3 unpaid days. Traced both GRNI receipts to receiving log. Shipment 4471 delivered 2 Oct per carrier POD; revenue moved to October. All three entries set to auto-reverse."
The cut-off tests sit inside a broader handover. Use this map as the base SOP and adapt thresholds, materiality and owners to your environment.
| Close area | Key assertions | PBC evidence | Controls the offshore team operates |
|---|---|---|---|
| Cash and bank recs | Existence, completeness, cut-off | Bank statements, recon workbook with outstanding items aging, GL detail | Preparer and reviewer separation, threshold for reconciling items, follow-up on items over 30 days |
| AR and revenue | Existence, valuation, cut-off | AR aging tied to GL, sample invoices with delivery proof, credit memo log, allowance rollforward | Order, delivery and invoice match; credit memo approval matrix |
| AP and accruals | Completeness, accuracy, cut-off | AP aging, GRNI report, accrual workbook, top vendor statements | Three-way match, recurring vendor accrual checklist, receipt window test |
| Inventory and COGS | Existence, valuation, cut-off | Subledger, count sheets with variances, cost build, write-down calculation | Cycle counts with thresholds, obsolescence policy applied quarterly |
| Fixed assets | Existence, valuation, classification | Rollforward, additions support, disposal approvals, depreciation schedule | Capitalization threshold policy, impairment indicator checklist |
| Leases | Completeness, valuation, classification | Lease register, contracts, discount rate memo, ROU asset and liability rollforward | New contract intake checklist, quarterly register reconciliation to AP |
| Payroll | Accuracy, cut-off, classification | Payroll register, headcount reconciliation, bonus accrual calculation | Gross-to-net review, HR master data kept separate from payroll processing |
For a full list of what auditors usually request in the first year, the PBC request list for first-time audits gives a 30-day preparation plan. Companies that need to design these controls from scratch before the first audit can start with the SOX-lite internal controls guide for scale-ups.
An offshore team that has worked mainly under one framework will default to its habits. The handover SOP should list the differences that affect period-end entries for the framework your client reports under, or both if a US subsidiary reports into an IFRS parent. The three that cause the most rework at close are inventory costing, development costs and leases.
| Topic | US GAAP | IFRS | What the offshore team does at close |
|---|---|---|---|
| Inventory cost formula | LIFO permitted, along with FIFO and weighted average | LIFO not permitted | For IFRS reporting, convert LIFO balances to FIFO or weighted average using the LIFO reserve |
| Inventory write-down reversal | Reversal of prior write-downs generally precluded | Reversal required when conditions reverse, capped at the original write-down | Track write-downs by item so IFRS reversals can be calculated |
| Development costs | Research and development generally expensed as incurred, with software development exceptions | Development costs capitalized once qualifying criteria are met | Keep project-level time and cost records so capitalization criteria can be tested monthly |
| Lessee accounting | Dual model: finance and operating leases | Single lessee model | Classify each new lease under ASC 842; under IFRS 16 apply one model with the short-term and low-value exemptions |
The SEC staff comparison of the two frameworks states that "U.S. GAAP also permits the use of the last-in, first-out (LIFO) method, which IFRS does not permit" (SEC staff paper). IAS 2 limits cost formulas to "the first-in, first-out or weighted average cost formula" for interchangeable items and measures inventories "at the lower of cost and net realisable value" (IFRS Foundation, IAS 2).
US companies that use LIFO for tax face the conformity rule in 26 U.S.C. 472(c), which ties tax LIFO to the method used in reports to shareholders and for credit purposes. So a US subsidiary may keep LIFO in its own books while its IFRS parent needs FIFO numbers. A simple example: inventory carried at $1,200,000 under LIFO with a $150,000 LIFO reserve becomes $1,350,000 on a FIFO basis for the group package. Post that adjustment in the consolidation layer and document the reserve calculation each month. The retail inventory accounting methods comparison of FIFO, LIFO and weighted average explains how each method moves cost of goods sold.
The same SEC paper notes that IFRS requires reversal of inventory write-downs when the impairment condition reverses, limited to the original write-down, while US GAAP generally precludes reversal. The practical close step is an item-level write-down log, so the reviewer can see what would reverse under IFRS.
Under IFRS, "Research expenditure is recognised as an expense" and "Development expenditure that meets specified criteria is recognised as the cost of an intangible asset" (IFRS Foundation, IAS 38). The SEC staff paper summarizes the US position: ASC 730 "generally requires that research and development costs are expensed as incurred, except for costs related to the development of computer software."
For the offshore team, this means IFRS clients need a monthly capitalization review on each development project, with the criteria assessment saved as evidence. US GAAP clients expense most of the same spend. The ASC 730 guide to research and development costs under GAAP covers the US rules in more depth.
IFRS 16 "introduces a single lessee accounting model" and "requires a lessee to recognise assets and liabilities for all leases with a term of more than 12 months" unless the asset is of low value (IFRS Foundation, IFRS 16). The IASB's own project summary explains that "the FASB decided to retain a dual accounting model," which leads to different expense recognition and cash flow reporting for leases that were previously off balance sheet (IFRS 16 Project Summary).
At close, that means a US GAAP lease register needs a classification column and separate rollforwards for finance and operating leases, while an IFRS register runs every qualifying lease through the same depreciation and interest pattern. The ASC 842 lease accounting implementation guide walks through the US register in detail.
Cut-off procedures only work if someone independent of the preparer checks them.
Keep each review note short. State what was agreed ("AR aging agrees to GL 1200"), the size of any variance against materiality, the exceptions with journal entry numbers, and the re-test result after correction. Store the note in the same folder as the PBC item or as a tab in the workbook, tagged with the period.
Run cash, AP, AR, payroll and revenue cut-off monthly, review estimates and reserves quarterly, and revisit policies annually. Firms preparing workpapers for an external auditor can align this with the offshore audit support guide to PCAOB and US GAAP workpapers.
A numbered PBC index is the backbone of the handover. Each line links one request to a dated workbook or PDF, the source system, the period, the preparer, the reviewer and the GL account it ties to.
| PBC # | Area | Assertions | File name | Tie-out |
|---|---|---|---|---|
| 1 | Bank recs | Existence, completeness | 01_Bank_Recs_Sep26.xlsx | GL 1000 to 1002 |
| 2 | AR aging and samples | Existence, valuation, cut-off | 02_AR_Aging_Sep26.xlsx | GL 1200 |
| 3 | AP and accruals | Completeness, cut-off | 03_AP_Accruals_Sep26.xlsx | GL 2000 |
| 4 | Fixed asset rollforward | Existence, valuation | 04_FA_Rollforward_Q3FY26.xlsx | GL 1500 |
Every workbook should carry a reconciliation tab that ties to the GL or subledger, record preparer and reviewer dates with version history switched on, and feed an exception log that lists each issue, its owner, a due date and the resolution. Payroll, tax and contract files belong in access-controlled folders.
Start with two processes, such as bank reconciliations and AP accruals. Run at least two close cycles in parallel, with the onshore team preparing the same schedules, before the offshore team takes full ownership. Lock the PBC index, SOPs and file naming rules before the first auditor request arrives. After each audit, add the auditor's comments to the SOPs.
The step-by-step guide to transitioning accounting work offshore covers the wider transition plan, and the guide on how to train an offshore accounting team on US GAAP and US tax covers the technical onboarding that should come before the first close.
Before each handover to audit, confirm these quality gates:
What are cut-off procedures in accounting? Cut-off procedures are tests that confirm transactions near period end are recorded in the correct period. They usually cover revenue, purchases and payables, payroll, cash and inventory movements in a window of a few days either side of month-end.
How many days before and after month-end should cut-off testing cover? There is no single required window. Many teams start with 3 business days for revenue and 5 days for receipts and payables, then widen the window for high-volume or high-risk accounts.
Can an offshore team sign off on its own cut-off work? The offshore team should prepare and document the tests, and an onshore reviewer who did not prepare them should approve the results and any adjusting entries. That separation is what auditors look for when they test the control.
Does IFRS allow LIFO inventory? No. IAS 2 allows FIFO or weighted average for interchangeable items, and LIFO is not permitted. A US subsidiary using LIFO needs a conversion adjustment when it reports into an IFRS group.
Are leases classified differently under US GAAP and IFRS? Yes. ASC 842 keeps a dual model with finance and operating leases for lessees, while IFRS 16 uses a single lessee model with exemptions for short-term and low-value leases.
Madras Accountancy supports US CPA firms and finance teams with outsourced bookkeeping, month-end close, reconciliations and audit preparation work under US GAAP and IFRS, with SOPs and review structures agreed up front. To talk through which close tasks to hand over first, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



