


With GAAS standards explained properly, most of the confusion about them goes away. GAAS stands for Generally Accepted Auditing Standards. They are the rules a CPA must follow when auditing the financial statements of a US entity that is not an SEC registrant: private companies, nonprofits, employee benefit plans and state and local governments. The AICPA's Auditing Standards Board (ASB) issues them as Statements on Auditing Standards (SASs).
Many textbooks still describe GAAS as "ten standards." That structure was retired more than a decade ago. Below we explain the original ten (they still appear on the CPA exam and in older literature), what replaced them, and the 2025 and 2026 effective dates that matter for audit work this year.
GAAS full form: Generally Accepted Auditing Standards. Three bodies set auditing standards in the US, and the one that applies depends on the entity being audited:
| Entity audited | Standards | Issued by |
|---|---|---|
| Private companies, nonprofits, benefit plans (nonissuers) | GAAS (AU-C sections) | AICPA Auditing Standards Board |
| Public companies and SEC-registered broker-dealers (issuers) | PCAOB auditing standards (AS sections) | Public Company Accounting Oversight Board |
| Governments and entities receiving federal awards, when required by law, contract or grant | Government Auditing Standards (Yellow Book), which incorporate GAAS for financial audits | US Government Accountability Office |
A common error is citing PCAOB section numbers such as AS 2110 as if they were SASs. They are separate standards for issuer audits. A private company audit report refers to "auditing standards generally accepted in the United States of America," and the work is measured against the AU-C sections.
GAAS also should not be confused with GAAP. GAAP governs how the company prepares its financial statements; GAAS governs how the auditor tests them. Our explainer on GAAP, generally accepted accounting principles covers the accounting side.
Before the clarity project, AU section 150 listed ten standards in three groups. They remain the easiest way to understand what an audit demands.
General standards (3)
Standards of field work (3)
Standards of reporting (4)
Some sources list "four general standards," adding ethics as a fourth. That is not how either the original or the clarified framework is organized. Ethics and independence requirements come from the AICPA Code of Professional Conduct, which GAAS requires the auditor to follow. Our guide to AICPA ethics rules for outsourcing shows how those rules apply when a firm uses offshore staff.
The ASB's clarity project redrafted every SAS into a consistent format (objective, definitions, requirements, application material) and converged them closely with the international standards on auditing. The clarified SASs are codified with an "AU-C" prefix and became effective for audits of financial statements for periods ending on or after December 15, 2012.
The ten standards were replaced by principles underlying an audit conducted in accordance with GAAS, grouped into four areas:
AU-C 200 sets the auditor's overall objective: to obtain reasonable assurance that the financial statements as a whole are free from material misstatement, whether due to fraud or error, and to report on them. "Reasonable assurance" is high but not absolute, which is why the concept of materiality runs through every later section. Our piece on materiality and risk in audits explains how auditors set it.
The AICPA's codification of currently effective SASs is the authoritative source and groups the AU-C sections by subject, for example AU-C 200 to 299 for general principles and responsibilities.
The ASB has rewritten a large share of GAAS since 2019. These are the standards a firm should have built into its methodology by now.
| Standard | Topic | Effective for |
|---|---|---|
| SAS 134 to 140 | Auditor reporting (opinion first, going concern section, optional key audit matters) and related amendments | Periods ending on or after Dec. 15, 2021 |
| SAS 142 | Audit evidence | Periods ending on or after Dec. 15, 2022 |
| SAS 143 | Auditing accounting estimates | Periods ending on or after Dec. 15, 2023 |
| SAS 144 | Use of specialists and pricing information | Periods ending on or after Dec. 15, 2023 |
| SAS 145 | Understanding the entity and assessing risk of material misstatement | Periods ending on or after Dec. 15, 2023 |
| SAS 147 | Inquiries of the predecessor auditor about fraud and noncompliance | Periods beginning on or after June 30, 2023 |
| SAS 146 | Quality management for an engagement (replaces AU-C 220) | Periods beginning on or after Dec. 15, 2025 |
| SAS 149 | Audits of group financial statements (replaces AU-C 600) | Periods ending on or after Dec. 15, 2026 |
SAS 146, Quality Management for an Engagement Conducted in Accordance With GAAS, makes the engagement partner responsible for managing and achieving quality on each audit, including sufficient and appropriate involvement throughout the engagement. It works alongside two firm-level standards issued at the same time: SQMS 1, which requires a risk-based system of quality management that firms had to design and implement by December 15, 2025, and SQMS 2 on engagement quality reviews. Firms must complete the first evaluation of their SQMS 1 system within one year of that date. Our article on SQMS and the AICPA quality management standards covers the firm-level requirements.
For a calendar-year client, SAS 146 first applies to the audit of the year beginning January 1, 2026, so most firms will feel it in the 2027 busy season.
SAS 149 replaces the "significant component" approach with a risk-based one. The group auditor decides where work is needed based on assessed risks, and has more responsibility for directing and reviewing component auditors' work. The US option to make reference to another auditor's report remains. For calendar-year groups, the December 31, 2026 audit is the first under the new standard. See our summary of how SAS 149 changes group audits.
The ASB's 2026 agenda includes fraud, going concern, confirmations, technology and a definition of public interest entities. On going concern, the Journal of Accountancy reports that the ASB began a project in August 2025 to consider targeted amendments to AU-C 570 in light of the IAASB's revised ISA 570. As of October 2026 no final US standard on either topic has an effective date, so treat these as watch items.
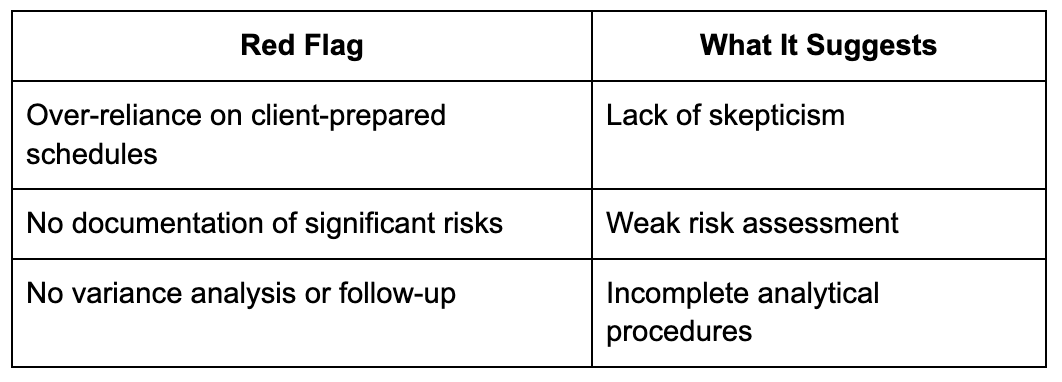
Peer reviewers and courts look for evidence in the file, so it helps to know what GAAS expects to see.
Engagement acceptance and independence. A signed engagement letter that sets out management's responsibilities (AU-C 210), plus a documented independence evaluation.
Risk assessment. Under SAS 145, auditors must separately assess inherent risk and control risk, understand the entity's IT environment and general IT controls, and identify significant risks. If the auditor does not plan to test controls, control risk is assessed at maximum. Clients with weak controls should expect more substantive testing; our post on internal controls testing for small businesses shows what auditors look for.
Evidence. SAS 142 asks the auditor to evaluate the relevance and reliability of information used as evidence, including data the client generates from its systems and data analysed with automated tools. That is the basis for using analytics in place of some sampling. Our guide to AI in audit and assurance covers how firms apply it.
Documentation. AU-C 230 requires the final audit file to be assembled within 60 days of the report release date and retained for at least five years from that date, unless law or regulation requires longer. (PCAOB rules for issuer audits require seven years, which is where the "seven-year" figure often quoted for GAAS comes from.)
Reporting. Since SAS 134, the opinion comes first, followed by the basis for opinion, and the report includes explicit statements on management's and the auditor's going concern responsibilities.
A private manufacturer with $25 million in revenue needs its first audit for a bank covenant. The audit is under GAAS, not PCAOB standards, because the company is not an issuer.
Owners can shorten this audit by preparing a complete PBC package before fieldwork. Our PBC request list template for first-time audits lists what to gather.
Government Auditing Standards apply when law, regulation, contract or grant terms require them. For financial audits they adopt GAAS and add requirements on independence, internal control reporting, compliance reporting and continuing education. The 2024 revision of the Yellow Book is effective for financial audits of periods beginning on or after December 15, 2025, and requires audit organizations to have a quality management system designed and implemented by that date.
Our guides to the Yellow Book audit for government contractors and Single Audit requirements for federal awards go further.
The volume of new SASs has stretched smaller firms, especially in the 2024 to 2026 seasons when SAS 145, SQMS 1, SAS 146 and SAS 149 all landed. Firms commonly update their audit methodology through a licensed practice aid provider, add risk assessment and IT controls training, and move preparation work (lead schedules, confirmations, sample selections) to support staff so senior auditors can concentrate on judgment areas. Many firms now use outsourced audit support for that preparation work, with review and sign-off staying with the US engagement team.
GAAS stands for Generally Accepted Auditing Standards. In the US, the term refers to the AICPA's Statements on Auditing Standards, codified as AU-C sections, which govern audits of entities that are not SEC issuers.
Not in their original form. Since the clarified SASs took effect for periods ending on or after December 15, 2012, the ten standards have been replaced by principles underlying a GAAS audit and the detailed AU-C requirements. The ten remain useful for studying and for reading older literature.
GAAS applies to audits of nonissuers such as private companies and nonprofits. PCAOB standards apply to audits of public companies and SEC-registered broker-dealers, and the PCAOB inspects the firms performing them.
No. Reviews and compilations of a private company's financial statements fall under the Statements on Standards for Accounting and Review Services (SSARS). Our comparison of financial statement audits vs. reviews vs. compilations explains which level of service a lender or investor will usually require.
SAS 146 applies to audits of periods beginning on or after December 15, 2025, and SAS 149 applies to group audits of periods ending on or after December 15, 2026. Firms also had to have SQMS 1 quality management systems in place by December 15, 2025.
If your firm needs extra capacity for audit preparation work under the new SASs, Madras Accountancy supports US CPA firms with workpapers, lead schedules and PBC tracking under your review. Contact us to discuss your audit season.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



