



Set aside about 25% to 35% of your net 1099 profit for taxes. For 2026, self-employment tax alone takes about 14.1% of net profit (15.3% applied to 92.35% of profit, with the Social Security part capped at a $184,500 wage base). The rest covers federal and state income tax, which depends on your situation.
If you freelance, consult or run a side business, no one withholds tax from your payments. That makes setting money aside your job. This guide walks through the 2026 self-employment tax figures, a worked example at three income levels, the 2026 estimated tax due dates and the safe harbor rules that keep you clear of underpayment penalties.
Before you can save the right amount, you need to know which taxes apply to self-employment income and why the bill is larger than many new freelancers expect.
When you work for yourself, you are self-employed. Instead of a W-2 showing wages and withholding, you may receive a Form 1099-NEC from clients. For payments made after December 31, 2025, a client generally only has to issue a 1099-NEC once it pays you $2,000 or more in the year (the old threshold was $600). Payment platforms report on Form 1099-K once you receive over $20,000 across more than 200 transactions.
Common sources of 1099 income include:
The higher thresholds mean you will receive fewer forms, not that you owe less tax. All of your self-employment income is reportable, whether or not a 1099 arrives.
A W-2 employer withholds federal income tax, state income tax where it applies, and the employee's share of Social Security and Medicare. The employer pays the other half of Social Security and Medicare itself.
With 1099 income, you receive the full payment and handle all of it yourself, including both halves of Social Security and Medicare through self-employment tax.
Federal income tax: charged on your total taxable income, including 1099 profit, any W-2 wages and other income. The rate that applies to you depends on your filing status, deductions, credits and other income, so it varies a great deal from person to person.
State and local income tax: some states have no income tax; others tax self-employment profit at meaningful rates. Some cities and counties add their own tax.
Self-employment tax: 15.3% on net earnings from self-employment, made up of:
You don't pay tax on everything clients pay you. You pay on net profit after deductible business expenses:
Gross 1099 income minus deductible business expenses = net profit.
Common deductible expenses include:
Tracking expenses all year lowers your net profit, which lowers both income tax and self-employment tax.
Self-employment tax is the part of the bill that surprises most new freelancers. It is separate from income tax and applies even if you owe little or no income tax.
As a self-employed person you are both the employer and the employee, so you pay both halves of Social Security and Medicare. That is why the rate is 15.3% rather than the 7.65% an employee sees on a pay stub.
Think of them as two separate bills. Income tax is charged on your taxable income after deductions such as the standard deduction, and the rate depends on your whole financial picture. SE tax is charged on your net self-employment earnings at a flat rate, with no standard deduction and no personal brackets. That is why someone with modest freelance profit can owe little income tax but still owe several thousand dollars of SE tax.
It is also why SE tax is the most predictable part of your set-aside. Once you know your net profit, you can calculate it to the cent.
Self-employment tax is figured on Schedule SE, which attaches to your Form 1040. The calculation works like this:
Example: net profit of $65,000 gives net earnings of $65,000 x 92.35% = $60,027.50. SE tax is $60,027.50 x 15.3% = $9,184.21. As long as you are under the wage base, SE tax works out to about 14.13% of net profit.
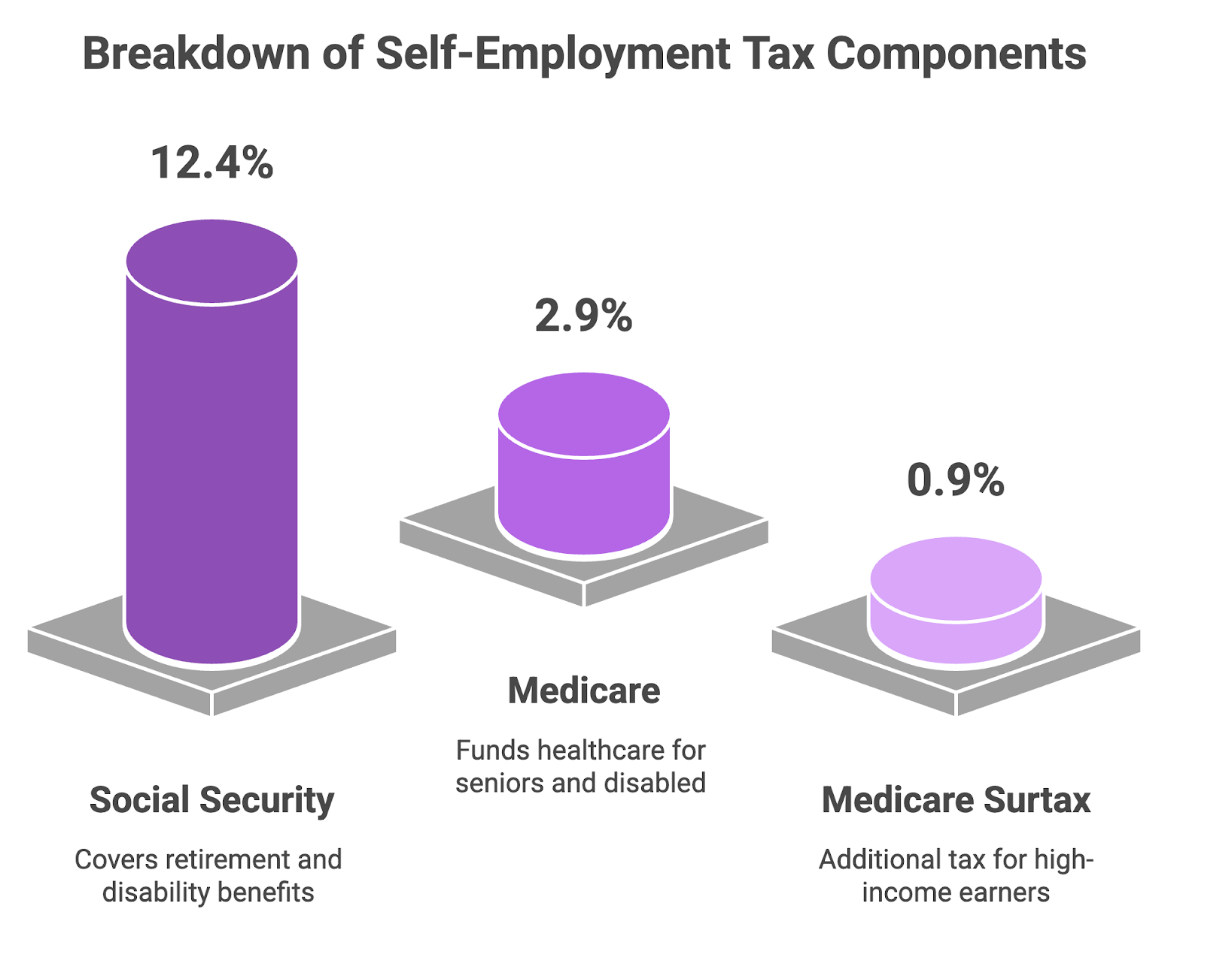
The 12.4% Social Security portion stops once your combined wages and net self-employment earnings reach $184,500 for 2026. Medicare's 2.9% keeps going with no cap.
If you also have a W-2 job, your W-2 Social Security wages count toward the $184,500 first. For example, with $120,000 of W-2 wages, only the next $64,500 of self-employment earnings is subject to the 12.4% Social Security tax in 2026.
You can deduct half of your SE tax as an adjustment to income on Form 1040. With SE tax of $9,184.21, the deduction is $4,592.11. It does not reduce the SE tax itself, but it lowers the income that federal income tax is charged on.
The practical rule: set aside 25% to 35% of net profit. Lean toward the lower end if your income is modest and your state has no income tax; lean toward the upper end if your income is high, you also have W-2 wages, or your state tax is significant.
Self-employment tax takes about 14.1% of net profit up to the wage base. Federal income tax and any state tax sit on top of that. Because SE tax is predictable and income tax varies, a 25% to 35% range covers most freelancers without leaving them short.
There is no single federal income tax rate for 1099 income. Your bill depends on filing status, the standard or itemized deductions you take, the qualified business income deduction, credits, a spouse's income and any W-2 wages. Two freelancers with the same profit can owe very different amounts.
For that reason, the example below shows SE tax precisely but uses an illustrative income tax rate. Treat that rate as a placeholder, not as your bracket. To estimate your own figure, use last year's return, the Form 1040-ES worksheet or a tax professional.
Assumptions: single filer, no W-2 wages, all figures are net profit after business expenses. SE tax uses the 2026 rules. The income tax and state tax rates are illustrative, deliberately cautious assumptions, not actual brackets.
Level 1: $40,000 net profit
Level 2: $90,000 net profit
Level 3: $200,000 net profit (above the wage base)
Two points stand out. SE tax is roughly 14.1% of profit at the first two levels and dips slightly at the third because of the $184,500 cap. Income tax, by contrast, is the part that grows with income and changes with your circumstances, which is why your own rate should replace the illustrative one. If you live in a state with no income tax, drop the state line.
Side income stacks on top of your salary, so it is often taxed at a higher rate than your first dollars of wages. Withholding on your W-2 covers the salary, not the side income. Say you net $17,000 from a side business: SE tax is $17,000 x 92.35% x 15.3% = $2,402.02. Add income tax at whatever rate your salary already puts you in (use an illustrative 20% here, or $3,400), and you would set aside about $5,800, or roughly 34% of the side profit. You can also cover this by increasing withholding at your job with a new Form W-4.
Use the worked example as a template rather than a rule. A quick way to pick a starting rate:
After your first full year, compare what you set aside with what you actually owed on your return. That ratio is the best guide for next year.
Freelance income rarely arrives evenly, so apply the percentage to each payment rather than to a monthly average. Using the Level 2 rate of about 31%:
If those payments are gross receipts rather than profit, the percentage will slightly over-save, because expenses have not been deducted yet. That is usually the safer mistake. When you review each quarter, you can release any excess once expenses are accounted for.
1. Open a separate tax savings account. Each time a client pays you, move your set-aside percentage into it straight away.
2. Track income and expenses monthly. A spreadsheet or bookkeeping software is enough.
3. Review every quarter. Compare year-to-date profit with your estimate and adjust your percentage up or down.
4. Pay estimated tax on time. The money only protects you from penalties once it reaches the IRS by each due date.
The IRS expects tax to be paid as you earn. If you wait until you file, you can owe an underpayment penalty and interest even if you pay the full balance at filing.
The U.S. tax system is pay-as-you-go. Employees meet that requirement through withholding from each paycheck. Self-employed people meet it through estimated payments. Paying four times a year also spreads the cost, so you are not trying to find a full year's tax in one month.
You generally need to make estimated payments if you expect to owe at least $1,000 in federal tax for the year after withholding and refundable credits, and your withholding and credits will fall short of the safe harbor amounts below.
If you missed an earlier 2026 payment, pay as soon as you can. The penalty is calculated on how much was short and for how long, so paying late is better than not paying until you file.
You avoid the underpayment penalty for 2026 if your withholding plus on-time estimated payments equal at least the smaller of:
Example: your 2025 return showed total tax of $18,000 and AGI of $120,000. You now expect 2026 tax of $26,000. Ninety percent of $26,000 is $23,400; 100% of 2025 tax is $18,000. The smaller amount is $18,000, so four payments of $4,500 by the due dates protect you from the penalty. If your 2025 AGI had been $160,000, the prior-year figure would be 110% of $18,000 = $19,800, or $4,950 a quarter.
Safe harbor protects you from the penalty, not from the tax. If your 2026 tax is $26,000 and you paid $18,000, you still owe the remaining $8,000 when you file, so keep that money in your tax account.
Step 1: Estimate net profit. Project gross 1099 income for the year and subtract expected business expenses.
Step 2: Estimate the tax. Calculate SE tax precisely (net profit x 92.35% x 15.3%, with the Social Security cap), then add an estimate of federal and state income tax based on your own situation.
Step 3: Compare with safe harbor. Work out 100% (or 110%) of last year's tax. If that is lower than 90% of this year's estimate and you want certainty, you can pay that amount instead.
Step 4: Divide by four and pay by each due date, less any withholding from W-2 wages.
Many states also require estimated payments. Check your state tax agency's site for its forms and dates.
Freelance income is uneven. If a quarter is slow, you can pay less; if it is strong, pay more to avoid falling behind. If most of your income arrives late in the year, the annualized income installment method on Form 2210 can reduce or remove a penalty for earlier quarters.
The final 2026 installment covers income earned from September through December. Before you pay it:
Year-end is also the time to make planned business purchases and retirement contributions that affect your 2026 profit, so your final estimate reflects them.
Every legitimate business expense lowers both income tax and SE tax. Common deductions include:
Filing is much easier when you keep:
As your income grows, consider:
If your income is substantial, uneven or comes from several sources, a professional can help you size your quarterly payments, find missed deductions and decide whether safe harbor or current-year estimates make more sense.
Setting aside 25% to 35% of net profit, holding it in a separate account and paying it to the IRS by each due date is the simplest way to avoid a large bill and penalties. For 2026, calculate SE tax precisely using the 92.35% factor and the $184,500 wage base, and estimate income tax based on your own circumstances rather than a one-size rate.
The next payment for 2026 is due January 15, 2027. If you are not sure you are on track, check your year-to-date profit against the safe harbor amounts now.
At Madras Accountancy, we help freelancers, consultants and growing business owners with 1099 income, bookkeeping, quarterly estimated payments and tax planning.
If you want to simplify your tax life and focus on your work, our team can help.
Talk to Madras Accountancy today and stay ahead of your 1099 taxes.
Question: What percentage of 1099 income should be set aside for taxes?
Answer: A common rule is 25% to 35% of net profit. About 14.1% of that covers self-employment tax for 2026 (up to the $184,500 wage base). The remainder covers federal and state income tax, which depends on your filing status, deductions, credits and other income. Higher earners, people with W-2 wages and residents of higher-tax states should lean toward the top of the range or above it.
Question: How do you calculate self-employment tax on 1099 income for 2026?
Answer: Multiply net profit by 92.35% to get net earnings from self-employment. If that is $400 or more, apply 12.4% Social Security tax to net earnings up to $184,500 (reduced by any W-2 Social Security wages) and 2.9% Medicare tax to all net earnings. An additional 0.9% Medicare tax can apply at high incomes. You then deduct half of the SE tax on Form 1040. Schedule SE does this calculation.
Question: What business expenses can reduce taxable 1099 income?
Answer: Ordinary and necessary business costs, such as supplies, equipment, software, professional fees, marketing, business travel, vehicle expenses (actual costs or the standard mileage rate), business insurance, licenses and a qualifying home office. Keep receipts and note the business purpose. Expenses reduce both income tax and self-employment tax.
Question: When are 2026 estimated tax payments due?
Answer: April 15, 2026; June 15, 2026; September 15, 2026; and January 15, 2027. To avoid an underpayment penalty, pay at least the smaller of 90% of your 2026 tax or 100% of your 2025 tax (110% if your 2025 AGI was over $150,000, or $75,000 if married filing separately) through withholding and on-time payments.
Question: What are effective ways to manage tax savings through the year?
Answer: Keep tax money in a separate account, move your set-aside percentage there every time you are paid, track income and expenses monthly, and adjust your percentage each quarter. An interest-bearing savings account lets the money earn something while you wait for the next due date.
Question: How do state taxes affect 1099 tax planning?
Answer: Some states have no income tax, while others take a meaningful share of self-employment profit, and some localities add their own tax. Many states also require their own estimated payments. Add your state's expected tax to your set-aside percentage and check its estimated payment schedule.
Question: What mistakes should 1099 workers avoid when setting aside taxes?
Answer: Forgetting self-employment tax, mixing tax money with spending money, skipping quarterly payments, leaving out income that came without a 1099, failing to track deductible expenses, and not raising the set-aside rate when income rises. Also remember that safe harbor only prevents penalties; any remaining tax is still due when you file.
Question: Do I pay self-employment tax on earnings above $184,500?
Answer: For 2026, the 12.4% Social Security portion stops once your combined W-2 Social Security wages and net self-employment earnings reach $184,500. The 2.9% Medicare portion continues on all earnings, and an additional 0.9% Medicare tax can apply at higher incomes.
Question: Do I need to set aside tax on income if I didn't receive a 1099?
Answer: Yes. All self-employment income is reportable, with or without a form. For payments made in 2026, clients only have to issue a 1099-NEC at $2,000 or more, and payment apps only issue a 1099-K above $20,000 and 200 transactions, so many payments will arrive with no form. Set aside tax on all of it.
Question: How can 1099 workers lower their tax beyond saving for it?
Answer: Claim every legitimate business deduction, contribute to a SEP-IRA or solo 401(k), use a health savings account if you have a qualifying plan, and review with a professional whether an entity choice such as an S corporation election fits your income level.
For CPA firms: Madras Accountancy supports U.S. CPA firms with tax preparation and planning, including seasonal capacity for busy season. See our tax preparation and planning services.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



