

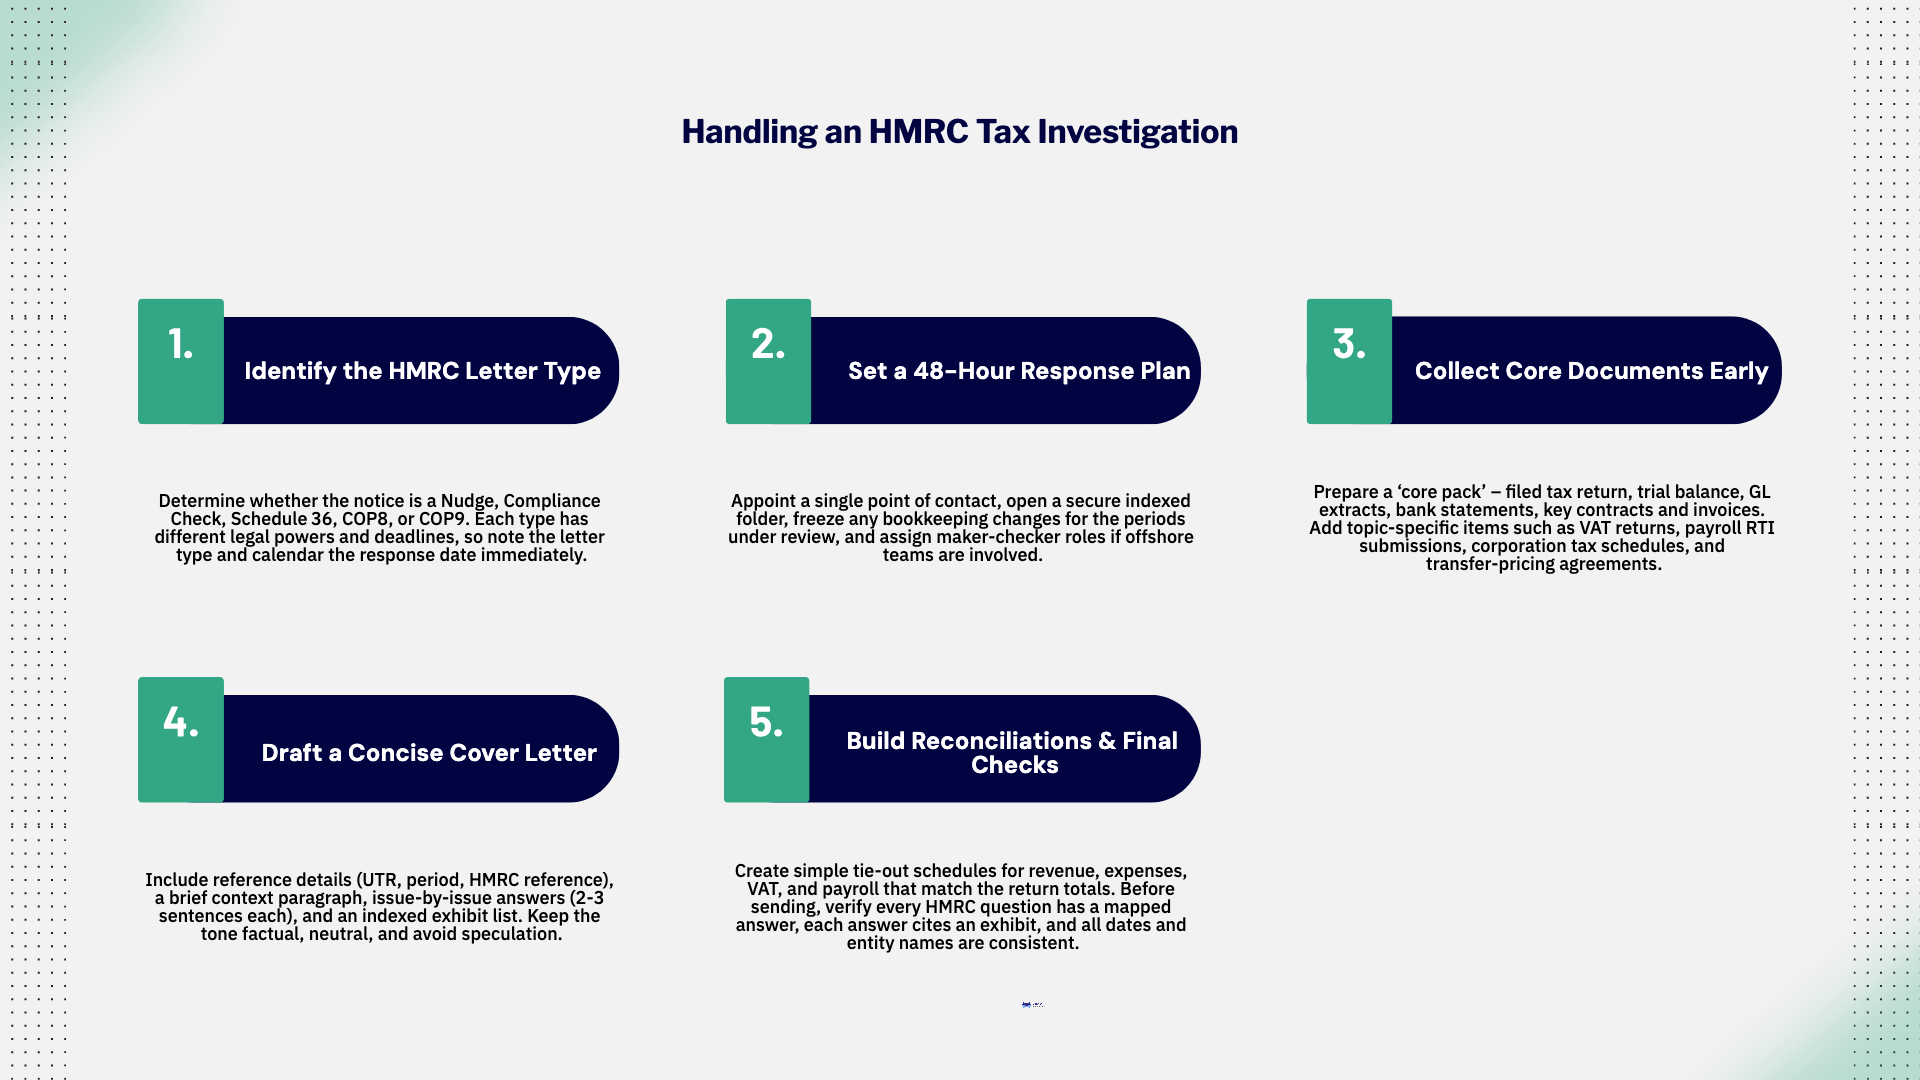

An HMRC compliance check is HMRC's review of whether a return or tax position is correct, and it usually starts with a letter or call setting out what HMRC wants to see. To handle it, confirm the scope and reply date, then answer only what HMRC asks with indexed evidence. If you find an error, tell HMRC before it finds the problem, because early disclosure keeps any penalty lower.
This guide covers how an HMRC compliance check works for UK companies and for US groups with a UK subsidiary or branch: the types of check, the 12-month enquiry window, Schedule 36 information notices, inaccuracy penalties by behaviour, the Digital Disclosure Service, and the 4, 6 and 20-year time limits. Figures and rules are stated as of October 2026. The Chancellor presents Budget 2026 on Wednesday 28 October 2026, so check gov.uk for any announced changes after that date.
HMRC describes it plainly: "A compliance check (sometimes known as a 'tax enquiry') is when HMRC checks your tax position." In its compliance checks help and support guidance, HMRC says it will "call or write to you to tell you what we want to check and why", and will also write to your authorised agent if you have one.
A check can cover any tax you pay, from Company Tax Returns to PAYE records. Selection alone does not mean HMRC has found a mistake.
For US-headquartered groups, the UK entity is usually the one receiving the letter, and the person answering may sit in the US finance team or an offshore support team. If you are still setting up, the guide to expanding to the UK covers the registrations and filings that a later check will test.
HMRC uses several routes, and the first job is to work out which one you are in.
| Route | What it means | What to do first |
|---|---|---|
| Compliance check (enquiry) on a return | A formal check of a specific return or issue | Diary the reply date and confirm the scope |
| Information notice under Schedule 36 | A legal demand for information or documents | Comply by the stated date or ask the officer for more time |
| Contractual Disclosure Facility (COP9) | HMRC suspects tax fraud and offers a disclosure contract | Take specialist advice at once; you have 60 days to decide |
The COP9 route is different in kind. HMRC's Contractual Disclosure Facility guidance says "You have 60 days to decide if you want to accept HMRC's offer of the Contractual Disclosure Facility", and that HMRC "will agree to not criminally investigate with a view to prosecute you" for the conduct disclosed under the contract. A business in that position should stop handling the matter internally and appoint a specialist adviser.
Some checks happen by phone, and HMRC may ask to visit premises or meet you. If an adviser is going to deal with HMRC for you, HMRC's guidance says they "must have formal agent authorisation". You remain "responsible for giving us accurate information", even when an agent replies.
For a return filed on time, HMRC generally has 12 months to open an enquiry.
Once the enquiry window has closed, HMRC can still raise assessments for earlier periods within the time limits set out below.
HMRC normally asks for information informally first. If that does not work, or sometimes without an informal request, it can issue an information notice. HMRC's factsheet CC/FS2 on information notices defines one as "a legal document that requires a person to provide information and produce documents to HMRC."
The power comes from Schedule 36 to the Finance Act 2008. HMRC's Compliance Handbook lists five types of notice, and a taxpayer notice covers information "reasonably required for the purpose of checking their tax position." Third parties, such as a bank or a customer, can also receive notices about your affairs.
Key points from CC/FS2:
If a request looks wider than the check needs, say so in writing. HMRC's guidance invites this: "If we request something that you think is not reasonable or relevant, let us know."
The process below keeps the useful structure of a well-run response and is the same whether the check is on corporation tax, VAT or PAYE.
1. Read the letter and fix the scope. Note the tax, the period, the specific questions and the reply date. Put the reply date in the calendar on the day the letter arrives. If anything is unclear, ask HMRC to confirm exactly which records it needs.
2. Set up a response file in the first two days. Nominate one contact for HMRC. Open a secure folder with a numbered index. Stop any changes to the books for the periods under review. If an offshore or US team is helping, assign a preparer and a reviewer for every schedule and agree who sends what, and when.
3. Collect the core pack. For most business checks that means the filed return and computations, the trial balance and general ledger extracts, bank statements and reconciliations, and the key contracts and invoices behind the questioned figures. Topic-specific packs add VAT returns and evidence of digital links for VAT (see the guide to MTD for VAT digital links), RTI submissions and benefits records for payroll, or intercompany agreements for transfer pricing.
4. Reconcile the books to the return. Build short schedules that tie the ledger to each return line, with adjustments shown. Use clear file names such as R1_GL_to_Return_FY2025.xlsx.
5. Write a short cover letter. Include the UTR or VAT number, the period and HMRC's reference. Answer each question in a few sentences and point to an exhibit. Keep the tone factual and avoid speculation. If an item will take longer, give the date you will send it. The structure is close to an IRS audit response pack, which helps US finance teams that already use one.
6. Communicate in writing and keep a log. Use one numbered thread of questions and answers, and track every request, owner and due date. HMRC's guidance says you can ask for more time: "If you need more time, tell us. We may agree to this if there's a valid reason."
7. Check for errors and disclose them early. If the review turns up a mistake, tell HMRC about it with the figures. As the next section shows, how and when you disclose has a direct effect on the penalty.
8. Review the outcome. HMRC's factsheet CC/FS1a says that at the end of a check HMRC will "either send you one or more 'decision notices' or agree a contract settlement with you." If you disagree with a decision you can appeal it, and HMRC also offers alternative dispute resolution.
If a check finds an inaccuracy, the penalty depends on your behaviour and on whether you told HMRC before it found the problem. HMRC's factsheet CC/FS7a on penalties for inaccuracies sets out four behaviours. There is no penalty if you took reasonable care. Careless means you "failed to take reasonable care to get things right". Deliberate means you "knew that a return or document was inaccurate when you sent it". Deliberate and concealed adds active steps to hide the inaccuracy.
Penalties are a percentage of the potential lost revenue (the extra tax due):
| Behaviour | Unprompted disclosure | Prompted disclosure |
|---|---|---|
| Reasonable care | No penalty | No penalty |
| Careless | 0% to 30% | 15% to 30% |
| Deliberate | 20% to 70% | 35% to 70% |
| Deliberate and concealed | 30% to 100% | 50% to 100% |
A disclosure is unprompted if you make it before you have reason to believe HMRC has found, or is about to find, the inaccuracy. Once a check has started, disclosures of matters within it are normally prompted.
Within each range, HMRC reduces the penalty for the quality of your disclosure. The maximum reductions are 30% for telling, 40% for helping and 30% for giving access to records. HMRC can also suspend a penalty for a careless inaccuracy for up to 2 years if you meet conditions it sets. It "cannot suspend penalties for any other type of behaviour."
HMRC's Compliance Handbook (CH82510) calculates the penalty rate in three steps: take the maximum less the minimum, multiply that by the quality of disclosure, and deduct the result from the maximum.
Assume a UK subsidiary under-declared corporation tax, with potential lost revenue of £18,000. Its disclosure scores 25% for telling, 30% for helping and 25% for giving access, a quality of disclosure of 80%. These figures are illustrative.
| Behaviour and disclosure | Range | Reduction (range x 80%) | Penalty rate | Penalty on £18,000 |
|---|---|---|---|---|
| Careless, unprompted | 0% to 30% | 24 points | 6% | £1,080 |
| Careless, prompted | 15% to 30% | 12 points | 18% | £3,240 |
| Deliberate, prompted | 35% to 70% | 28 points | 42% | £7,560 |
| Deliberate and concealed, prompted | 50% to 100% | 40 points | 60% | £10,800 |
In this example the same careless error costs £1,080 if the company finds and reports it first, and £3,240 if HMRC's check prompts the disclosure.
If you find unpaid tax from earlier years and HMRC has not raised it, the main route is the Digital Disclosure Service. HMRC's guide to making a disclosure confirms that "Individuals and companies can use the digital disclosure service to notify." The steps are:
The deadline is strict: "you must disclose within 90 days of the date that we acknowledge your notification." Offshore matters use the Worldwide Disclosure Facility, and suspected fraud goes through the Contractual Disclosure Facility described above. Businesses holding digital assets should also read the guide to crypto accounting for UK SMEs, since unreported gains are a common reason to disclose.
How far back HMRC can assess depends on your behaviour. HMRC's Compliance Handbook at CH53100 sets out "the normal time limit of 4 years from the end of the relevant tax period", extended to "6 years (careless)" and "20 years (deliberate) from the end of the relevant tax period." The handbook notes that the 6-year careless limit applies only to certain taxes, such as income tax and corporation tax, so check the limit for VAT and duties separately.
| Behaviour | Assessment time limit | Years covered in a disclosure |
|---|---|---|
| Reasonable care | 4 years from the end of the period | Up to 4 years |
| Careless | 6 years from the end of the period (certain taxes, such as income tax and corporation tax) | Up to 6 years |
| Deliberate | 20 years from the end of the period | Up to 20 years |
The disclosure guide matches this: if you took reasonable care you pay for a maximum of 4 years, careless errors for a maximum of 6 years, and deliberate underpayments for a maximum of 20 years. The US rules work differently, as the guide to how far back the IRS can audit you explains, so US parents should not assume the same windows apply to a UK entity.
Most of the issues that drive a check come from weak records or unclear structures. Owner pay is one example, and the guide to salary vs dividends in the US and UK covers the UK rules. Staff working in the UK for a US company raise another, and the guide to US-UK permanent establishment risk for remote employees explains when a UK taxable presence can arise.
A monthly close that reconciles the ledger to VAT and payroll filings gives you most of a response pack before any letter arrives. Keeping the working papers behind each return in the same indexed folder makes the rest quick to assemble. Teams that rely on outside support should agree who owns HMRC correspondence, a point covered in the guide to outsourcing accounting for UK businesses.
How long does an HMRC compliance check take? HMRC does not publish a fixed duration. A narrow check can close after one exchange, while a multi-year check can run for months.
Can HMRC open a compliance check after the 12-month enquiry window closes? Yes, in some cases. If HMRC discovers an underpayment, it can raise an assessment within 4 years, or within 6 years for careless errors (for certain taxes, such as income tax and corporation tax) and 20 years for deliberate ones, counted from the end of the relevant period.
What happens if I ignore a Schedule 36 information notice? HMRC can charge a £300 penalty, followed by daily penalties of up to £60 for each day you do not comply. Ask the officer for more time before the deadline if you need it.
Will I get a penalty if HMRC finds an error? Only if the error was careless or deliberate. If you took reasonable care there is no penalty, though you still pay the extra tax. Telling HMRC early and helping fully reduces the penalty within the legal range.
Should I use the Digital Disclosure Service if a check has already started? Usually no. Once HMRC has opened a check, you should disclose the error to the officer handling it. The Digital Disclosure Service is for unpaid tax that HMRC has not yet raised with you.
Madras Accountancy supports UK entities and US groups with UK operations on bookkeeping, reconciliations and the supporting schedules that a compliance check calls for, working alongside your tax adviser. To discuss a current HMRC letter or tidy your records before the next return, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



