

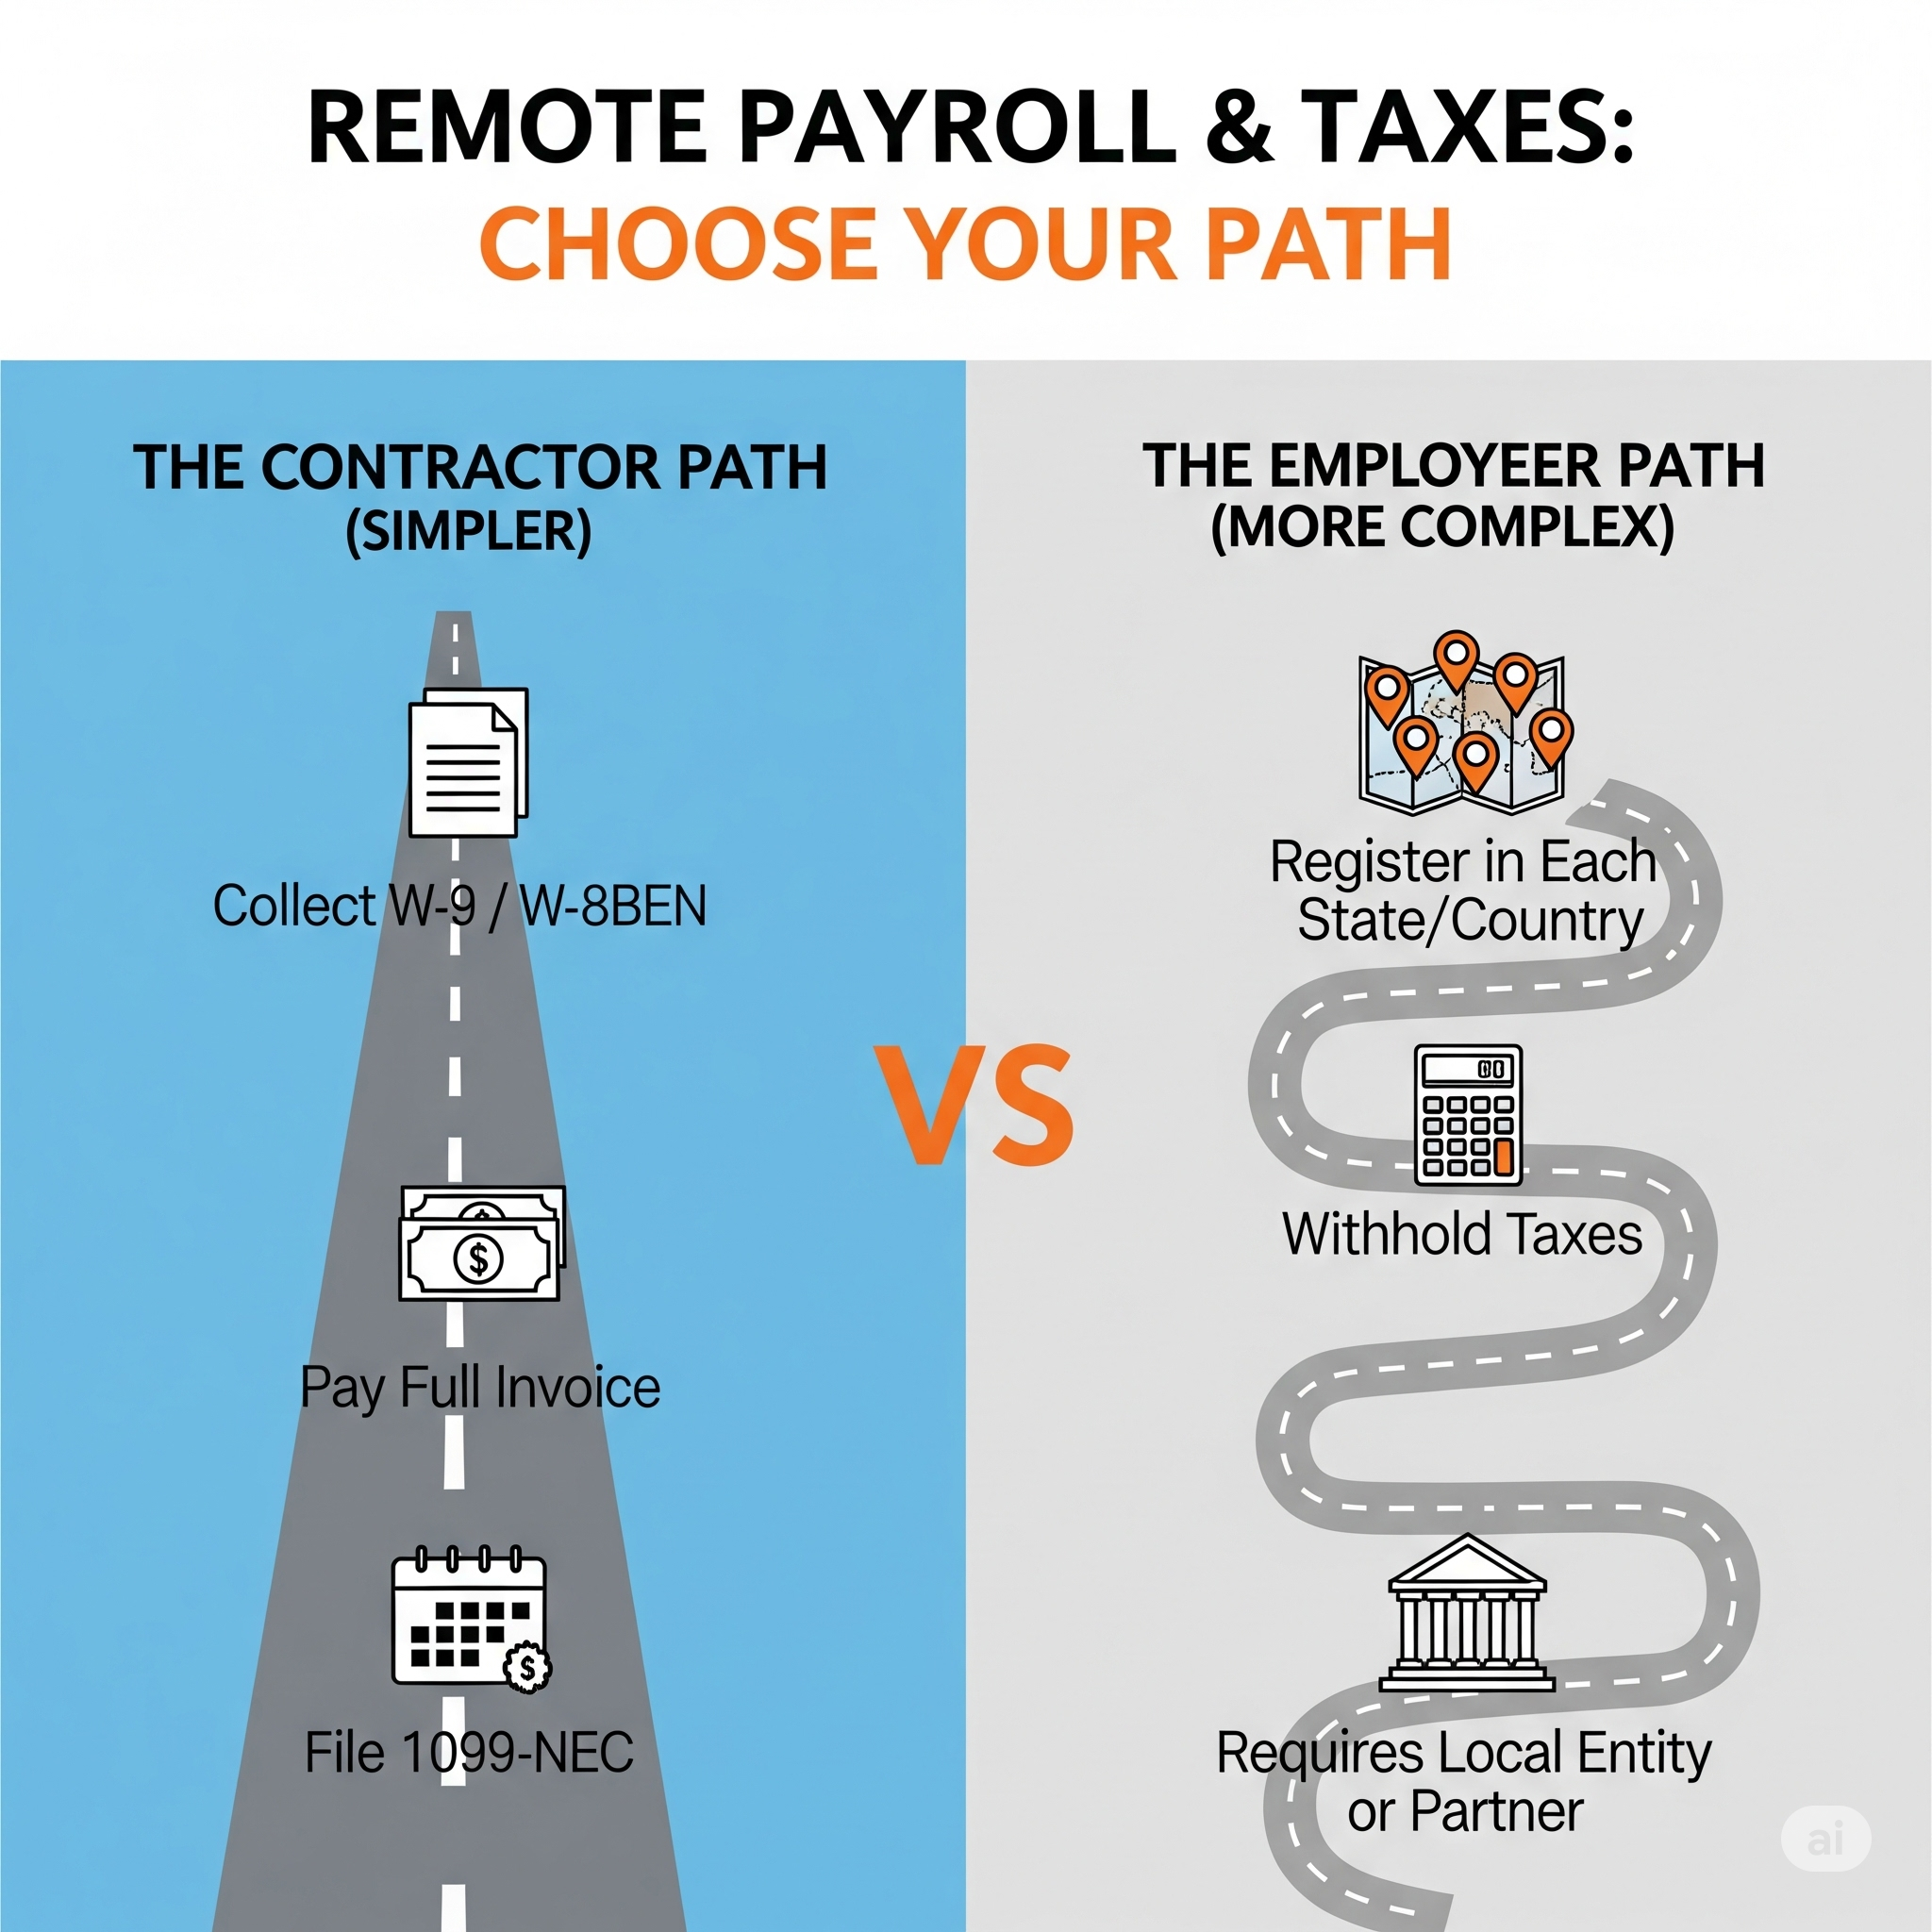

Setting up payroll for remote workers starts with one fact: a US employee's wages are generally taxed where the employee physically does the work, which for a remote hire is usually their home state. You register as an employer in that state, withhold its income tax (and any local tax), open a state unemployment (SUI) account there, and run federal withholding exactly as you would for an office employee.
This guide covers how to set up payroll and taxes for remote workers step by step, from the first state registration to remote Form I-9 verification. It focuses on the setup work for a single new remote hire. For the ongoing rules once you employ people across many states, see our multi-state payroll 101 guide, and for the recurring filing calendar, use the payroll compliance checklist.
Classification comes before any registration. If you direct how, when and where the person works, the IRS and most states will treat them as an employee, and every step below applies. If the person runs an independent business and controls their own methods, they may be a contractor paid by invoice with no withholding.
Remote work does not change the classification tests. States can apply stricter tests than the IRS. California's ABC test is the best-known example, explained in our article on AB5 worker classification in California. For the federal factors and how 1099 status works in practice, read understanding 1099 workers.
For US contractors, collect a Form W-9 before the first payment and track annual totals, since the 1099-NEC filing threshold changed for 2026. The details are in our breakdown of the 2026 1099 reporting threshold.
Once you hire a remote employee in a state where you have no other staff, you generally need two new state accounts there: an income tax withholding account with the state revenue department and an unemployment insurance account with the state labor or workforce agency.
Pennsylvania shows how the sequence works. The Department of Revenue's employer withholding page says an employer must first get a Federal Employer Identification Number from the IRS and then register through the Pennsylvania Online Business Tax Registration on myPATH. Other states follow a similar order: federal EIN first, then state accounts.
Register before the first payroll date, since a state account number can take days or weeks to arrive. Some employers also need to register their company with the state's Secretary of State as a foreign entity doing business there. Whether one remote employee triggers that requirement depends on the state, so treat it as a question for counsel or your accountant.
| Setup item | Where it is handled | When |
|---|---|---|
| Federal EIN | IRS | Before any payroll |
| State withholding account | Employee's work state revenue department | Before first payroll |
| State unemployment (SUI) account | Employee's work state labor or workforce agency | Before first payroll |
| Local tax account, if any | City, county, school district or appointed collector | Before first payroll |
| New hire report | State new hire registry | Shortly after the hire date (state deadlines vary) |
| Form W-4 and state withholding certificate | Employee completes; you keep on file | First day of work |
| Form I-9 | Employer, in person or by the E-Verify remote procedure | Section 2 within three business days of the start date |
| Workers' compensation coverage | Insurer or state fund covering the employee's state | Before the start date |
Federal payroll tax does not change for a remote employee. IRS Publication 15 tells employers to "Ask each new employee to complete the 2026 Form W-4" and to use it to figure federal income tax withholding. For 2026, Social Security tax is 6.2% each for the employer and employee on wages up to the $184,500 wage base, and Medicare tax is 1.45% each with no wage cap. Deposits and quarterly reporting go through the same channels as your other employees, as covered in our guide to Form 941, the quarterly federal return.
State withholding follows the work location. Pennsylvania's rule is typical: the state requires withholding at "a flat rate of 3.07 percent of compensation" when resident employees perform services within or outside Pennsylvania, and when nonresident employees perform services within Pennsylvania. Many other states use graduated rates and their own withholding certificates, so ask each remote hire for the state form as well as the federal W-4.
Reciprocity agreements are an exception worth checking. Pennsylvania has agreements with Indiana, Maryland, New Jersey, Ohio, Virginia and West Virginia. Under those agreements, an employer that does not withhold Pennsylvania tax for a resident of one of those states must withhold that resident state's tax instead. An employee who lives in one reciprocal state and works in another can file the exemption form, and you withhold only for the home state.
States without a wage income tax, such as Texas and Florida, require no state income tax withholding account. You still need an SUI account in those states if the employee works there.
Every state runs its own unemployment insurance tax, with its own wage base, new employer rate and quarterly wage report. For a remote employee, you generally pay SUI to the state where the work is "localized." The US Department of Labor's guidance on state UI coverage (UIPL 20-04, Attachment I) describes the standard test that states share. Service is localized in a state if it is performed entirely within that state, or if work done elsewhere is incidental to the work in that state. A fully remote employee working from home in Colorado is localized in Colorado, even if the company is based in Illinois.
When the localization test does not settle the question, states apply fallback tests in order: the employee's base of operations, then the place from which the work is directed or controlled, and finally the state where the employee lives.
SUI also affects your federal unemployment tax. The IRS explains in Topic 759 that "The FUTA tax rate is 6.0%" on the first $7,000 of each employee's wages, and that an employer entitled to the maximum 5.4% credit pays a net rate of 0.6%. The credit depends on paying state unemployment tax in full and on time, and it is reduced if the state is a credit reduction state. Paying SUI to the wrong state can therefore cost you twice: once in back state tax and once in a lost FUTA credit. Our explainers on Form 940 and federal unemployment tax and on FUTA credit reduction states cover the annual filing.
Local payroll taxes catch many employers off guard because they depend on the employee's exact address. Cities, counties and school districts in states such as Pennsylvania, Ohio, Michigan, Kentucky, Indiana, Maryland and New York impose their own wage taxes, and the rules differ by locality.
Pennsylvania's local earned income tax under Act 32 is a clear example. The Department of Community and Economic Development's Act 32 FAQ says employers are required to withhold the higher of the employee's total resident earned income tax rate and the non-resident rate of the municipality where they work, and to send the money to the workplace tax collector.
Collect the employee's full home address, confirm the local jurisdiction codes in your payroll system, and recheck them whenever the employee moves. A move across a municipal line can change the rate even when the state stays the same.
The convenience-of-the-employer rule applies when an employee is assigned to an office in one state but chooses to work from home in another. A handful of states source those home-working days to the office state, so the employee can owe tax there even on days spent at home.
New York's nonresident FAQ addresses an employee whose primary office is inside New York but who telecommutes from outside the state. It says "your days telecommuting are considered days worked in the state" unless the employer has established a bona fide employer office at the telecommuting location. New Jersey adopted its own version, retroactive to January 1, 2023. The New Jersey Division of Taxation's convenience rule page says the rule only applies to employees who are residents of states that impose a similar test, and gives Delaware, Nebraska and New York as examples.
The practical setup step is to document each employee's assigned office. Record the assignment in the offer letter and the HR system so payroll withholds for the right state from the first paycheck. Our article on tax planning for remote and hybrid workforces covers the business-level planning.
This example is illustrative. A Texas company hires its first remote employee, who lives and works full time from home in Pennsylvania. Salary is $78,000 a year, paid biweekly over 26 pay periods, so each gross paycheck is $3,000. The employee's municipality is assumed to have a combined earned income tax rate of 1.5%. Actual local rates vary.
| Item (per paycheck) | Employee withheld | Employer pays |
|---|---|---|
| Social Security, 6.2% | $186.00 | $186.00 |
| Medicare, 1.45% | $43.50 | $43.50 |
| Pennsylvania income tax, 3.07% | $92.10 | None |
| Local earned income tax, 1.5% (illustrative) | $45.00 | None |
| Pennsylvania UC employee contribution, 0.07% | $2.10 | None |
| FUTA, 0.6% on first $7,000 | None | $18.00 (paychecks 1 and 2), $6.00 (paycheck 3) |
| Federal income tax | Per Form W-4 | None |
Before federal income tax, the employee's take-home pay is $3,000 minus $368.70 in withholdings, or $2,631.30. Over the year, Social Security withholding totals $4,836, Medicare $1,131, Pennsylvania tax $2,394.60, local tax $1,170 and the Pennsylvania UC employee contribution $54.60. Pennsylvania is one of the few states that withholds an unemployment contribution from employees (0.07% of gross wages for 2026). The employer's FUTA cost reaches its $42 annual maximum ($7,000 x 0.6%) in the third paycheck, because cumulative wages pass $7,000 at $9,000.
The employer also owes Pennsylvania SUI at its assigned new employer rate, and Texas has no role in this employee's payroll. The company needs a Pennsylvania withholding account, a Pennsylvania UC account and a local EIT account before the first pay date, even though it has no office in the state.
Hiring someone who lives and works outside the US is a different setup, and in most cases it does not run through US payroll at all. The IRS page on persons employed abroad by a US person states that "as a general rule, wages earned by nonresident aliens for services performed outside of the United States for any employer are foreign source income," so they are generally not subject to US federal income tax reporting and withholding. US citizens and residents working abroad are different: the same page says their wages from a US employer are generally subject to federal income tax withholding.
For a foreign national abroad, the employer usually picks one of two routes:
A long-term remote employee abroad can also create a permanent establishment for your company in that country. Our article on permanent establishment risks for remote teams explains the trigger points, and managing global payroll covers payment mechanics.
Every US employee needs a Form I-9, remote or not. The USCIS employer handbook says Section 2 must be completed "within three business days of the date employment begins," and that the employer or an authorized representative must generally review documents in the employee's physical presence.
Employers enrolled in E-Verify have another option. USCIS's page on remote examination of documents describes an alternative procedure for employers in good standing with E-Verify at the hiring site. The employer must examine copies of the documents (front and back if two-sided), conduct a live video interaction with the employee presenting the same documents, check the alternative procedure box in Section 2, and retain clear copies of the documents. If an employer offers the procedure at a hiring site, it must offer it consistently to all employees at that site, though it may limit the procedure to remote hires as long as the choice is not discriminatory.
Employers not enrolled in E-Verify can name an authorized representative near the employee, such as a notary, to inspect documents in person.
An employee working from a state can create income or franchise tax filing obligations for the company there, separate from payroll. Each state sets its own nexus rules, and some count an in-state employee as physical presence. Review the multi-state tax compliance guide when a hire opens a new state.
Do I withhold taxes for the state where my company is or where the remote employee lives? Generally, withhold for the state where the employee physically works, which for a fully remote employee is usually their home state. Exceptions include reciprocity agreements and convenience-of-the-employer states such as New York.
Do I need to register in a state for just one remote employee? Yes, in most cases. One employee working in a state usually requires a state withholding account (if the state taxes wages) and a state unemployment account, plus any local tax accounts.
Which state gets unemployment tax for a remote employee? Under the localization test that states share, SUI goes to the state where the employee performs all or nearly all of the work. Fallback tests use base of operations, direction and control, and then residence.
Can I complete Form I-9 remotely? Yes, if you are enrolled in E-Verify and in good standing. You examine document copies, hold a live video call, check the alternative procedure box and keep copies. Otherwise, use an authorized representative who sees the documents in person.
How do I pay a remote worker who lives outside the US? Most US companies use either an independent contractor agreement with a Form W-8BEN on file or an employer of record in the worker's country. Wages a nonresident alien earns for work performed outside the US are generally foreign source income and not subject to US federal withholding.
Madras Accountancy supports US businesses and CPA firms with payroll processing, state registrations, bookkeeping, tax preparation and CFO advisory. If you are adding remote employees in new states and want help setting up accounts and withholding correctly, contact our team.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



