


An M&A due diligence checklist is the list of documents, analyses and questions a buyer works through before closing an acquisition. It covers four workstreams: financial (including a quality of earnings review), tax, legal and operational. Each item on the list should either confirm the price in the letter of intent, change it, or move a risk into the purchase agreement through an indemnity, escrow or specific representation.
This M&A due diligence checklist is written for owners preparing to sell, buyers of lower middle market companies, and CPA firms supporting either side. It reflects rules in force in October 2026, including the One Big Beautiful Bill Act (OBBBA) tax changes and the 2026 Hart-Scott-Rodino filing thresholds. If the deal is a property purchase rather than a company, the real estate due diligence checklist for property buyers covers title, survey and lease items that this guide leaves out.
Diligence normally starts once the letter of intent is signed and the seller opens a virtual data room. Findings from each workstream feed the valuation model, the purchase agreement and the integration plan.
Assign an owner to every workstream on day one and keep a single tracker of requests and their status. Sellers who build that tracker before going to market, much like a startup preparing its finances for investor due diligence, usually close faster because the buyer spends less time chasing documents.
| Workstream | Core question | Typical lead | Main output |
|---|---|---|---|
| Financial | Are reported earnings and cash flows real and repeatable? | Accounting firm (QoE team) | Quality of earnings report, net working capital peg |
| Tax | What tax exposure transfers to the buyer, and what attributes survive? | Tax adviser | Tax diligence memo, structuring advice |
| Legal | What contracts, disputes and approvals affect the deal? | Deal counsel | Legal diligence report, disclosure schedule comments |
| Operational | Can the business keep running the same way after closing? | Buyer's management or operating partner | Integration plan, 100-day priorities |
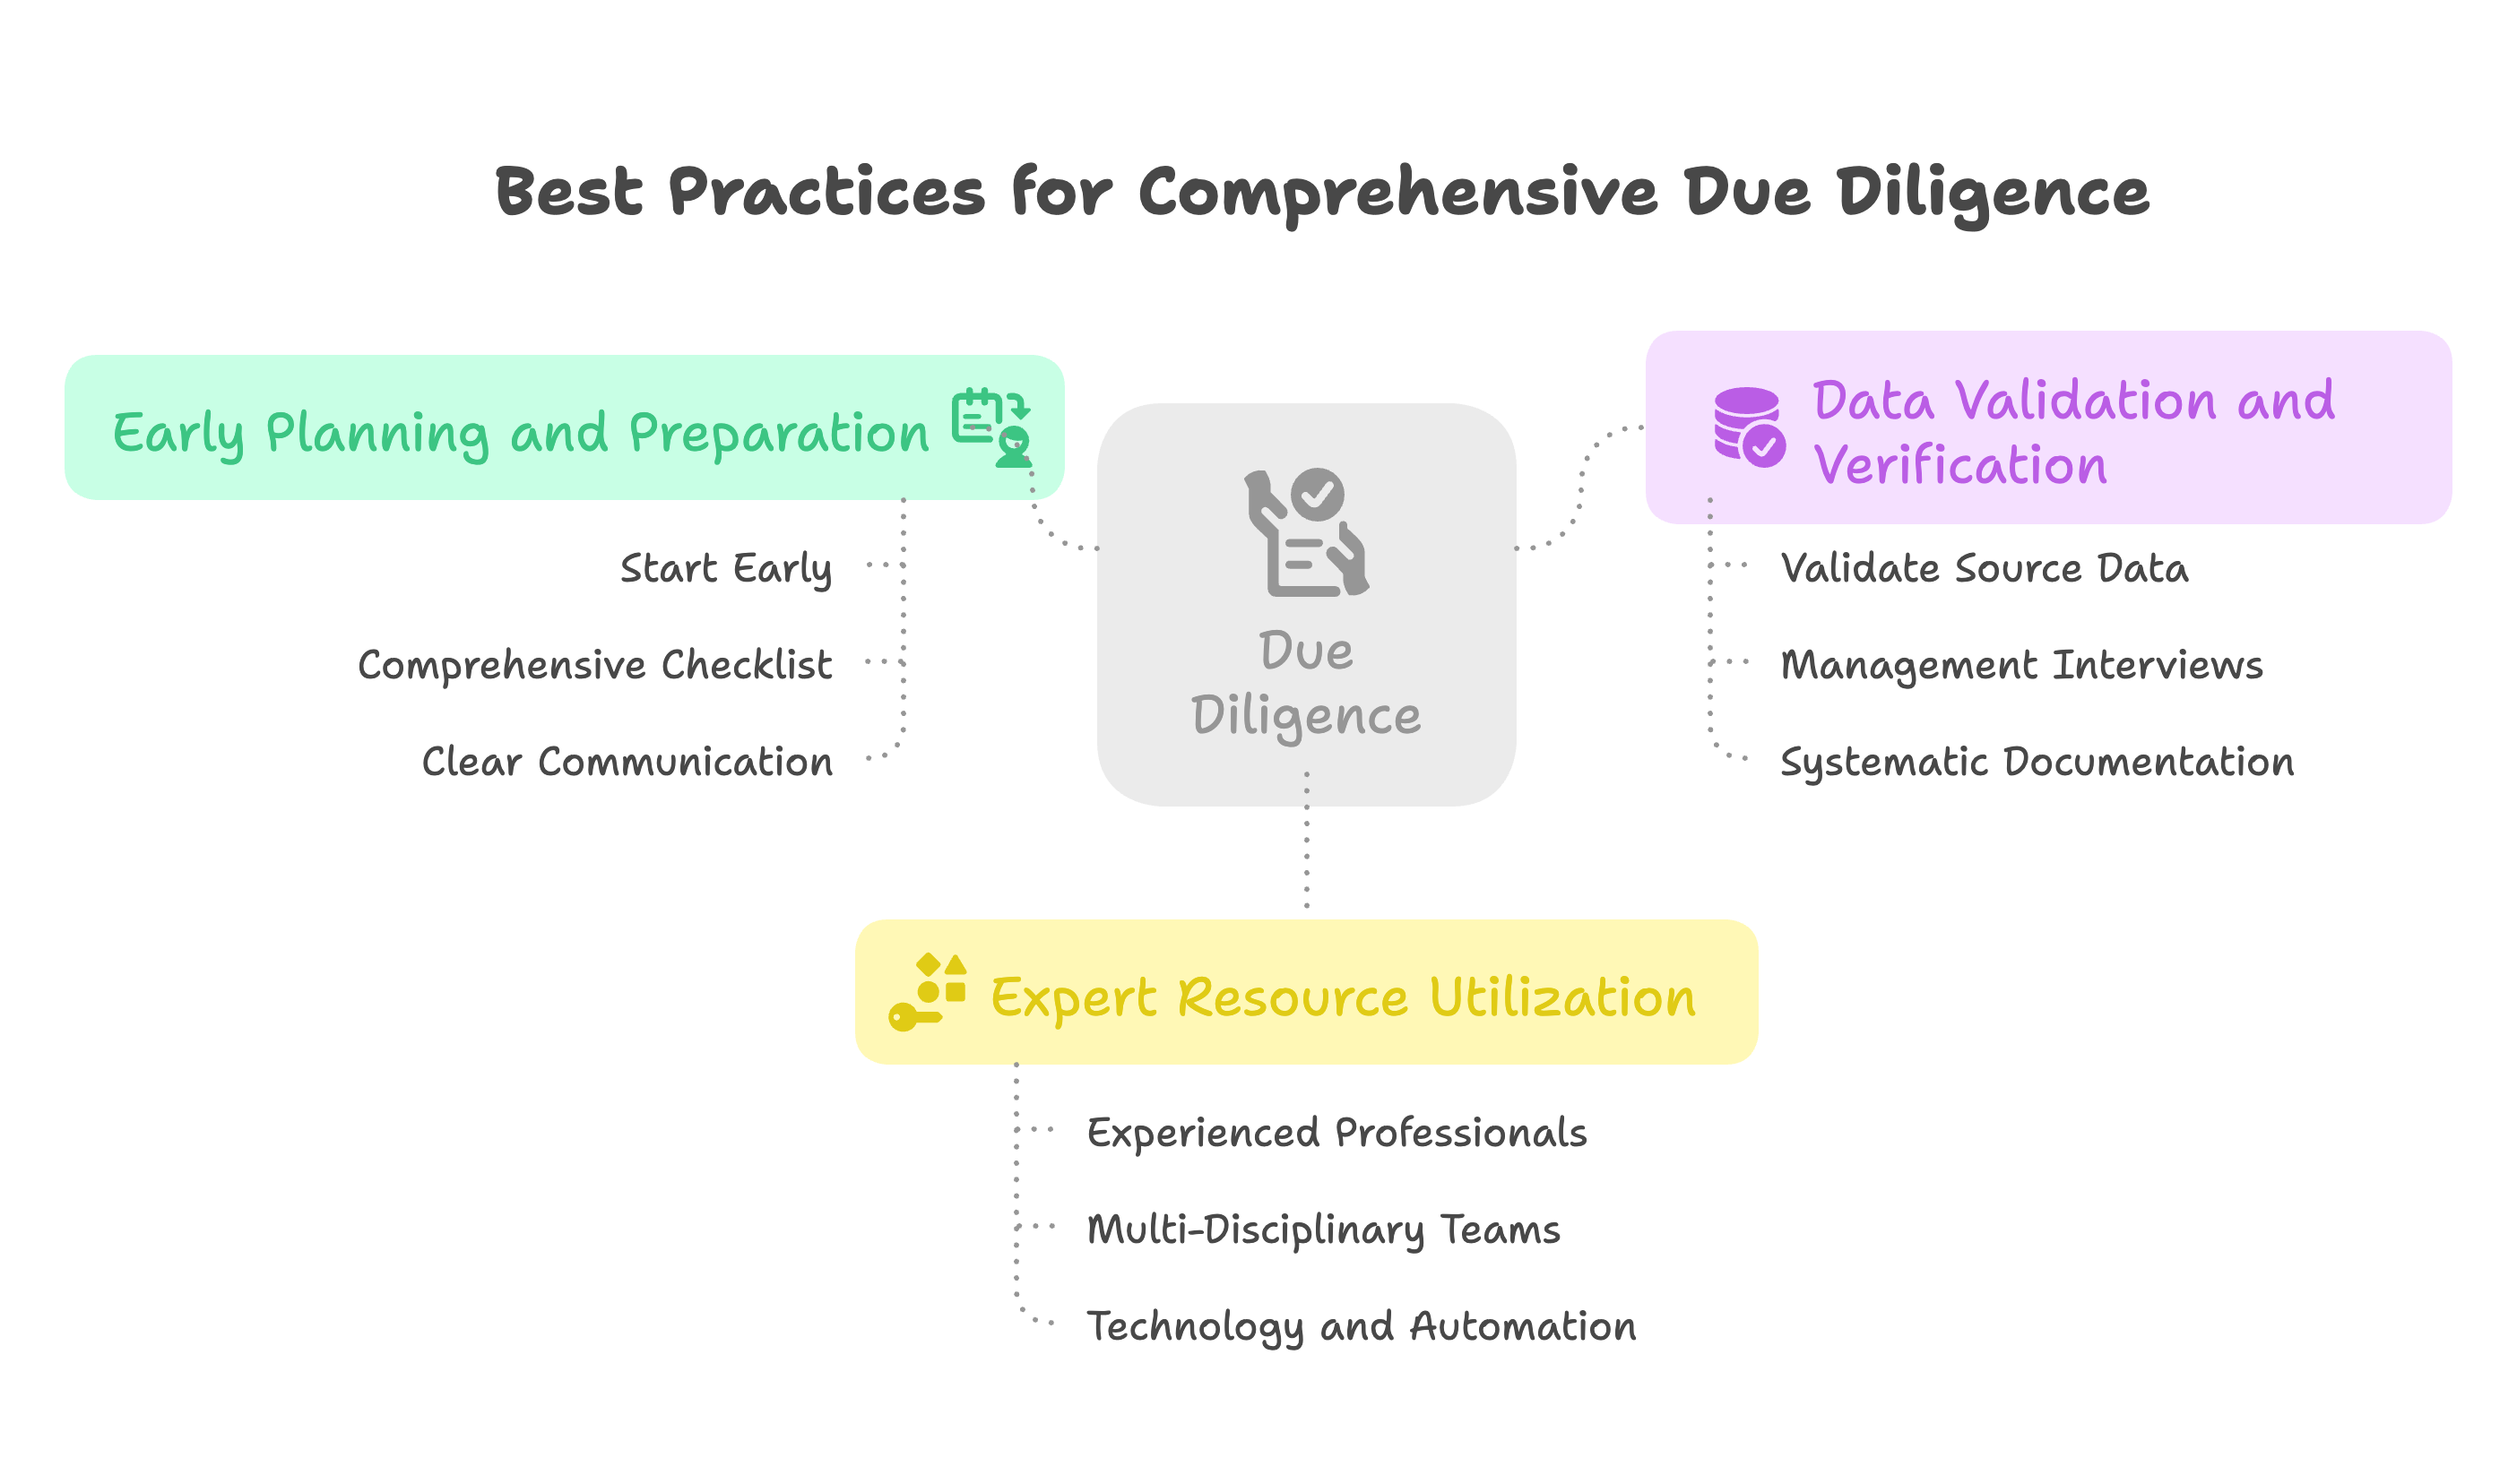
The financial workstream tests whether the marketing numbers match the books, and the books match the bank. Request at least three years of history plus the current year to date.
Historical statements and reporting
Revenue and customers
Working capital and cash
Debt and debt-like items
A quality of earnings (QoE) report restates EBITDA to show what the business earns on a normal, recurring basis under the buyer's ownership. Most lower middle market deals are priced as a multiple of adjusted EBITDA, so each dollar of adjustment moves the price by the multiple.
A QoE review usually covers four tests:
The SEC's guidance on non-GAAP measures offers a useful discipline even for private deals. The staff states that a measure that "excludes normal, recurring, cash operating expenses necessary to operate a registrant's business" could be misleading, and it views an expense that occurs "repeatedly or occasionally, including at irregular intervals" as recurring (SEC non-GAAP interpretations). A buyer's QoE team applies the same test to yearly "one-time" add-backs.
The figures below are illustrative. Harbor Supply Co., a distributor, reports trailing twelve month EBITDA of $2,400,000. The buyer's offer uses a 6.0x multiple, also illustrative. The QoE team proposes five adjustments.
| Adjustment | Reason | Effect on EBITDA |
|---|---|---|
| Owner salary of $450,000 reset to a market CEO salary of $250,000 | Owner pay above market | +$200,000 |
| Lawsuit settlement paid in the period | Non-recurring legal cost | +$120,000 |
| Warehouse leased from the owner's LLC at $60,000 a year; market rent is $150,000 | Related-party rent below market | -$90,000 |
| Year-end employee bonuses never accrued | Accrual correction | -$80,000 |
| ERP implementation consulting | Claimed as one-time project cost | +$95,000 |
| Adjusted EBITDA | $2,645,000 |
Adjusted EBITDA is $2,400,000 + $200,000 + $120,000 - $90,000 - $80,000 + $95,000 = $2,645,000, about 10.2% above the reported figure. At 6.0x, the headline value rises from $14,400,000 to $15,870,000, a difference of $1,470,000.
The ERP add-back is where negotiation usually happens. If the buyer shows the company spends on system projects every few years and rejects the $95,000, adjusted EBITDA falls to $2,550,000 and value at 6.0x falls to $15,300,000. That single line is worth $570,000 of price. The rent and bonus adjustments cut against the seller, and a sell-side QoE lets the seller deal with all of these items before a buyer raises them.
For a full valuation build around adjusted EBITDA, see our guide to financial modeling for business valuation, which works through a DCF alongside the multiple method.
As general information, tax exposure usually stays with the legal entity in a stock purchase, so the buyer indirectly takes on the target's open years. In an asset purchase, historic income tax generally stays with the seller, although sales tax, payroll tax and state successor liability rules can still reach the buyer. The right structure depends on the facts of each deal and should be confirmed with a tax adviser.
Open years and filings
State and indirect tax
Structure and tax attributes
OBBBA changes to model in 2026
Counsel leads legal diligence, though many findings carry a dollar value.
For 2026, the Federal Trade Commission raised the size-of-transaction threshold for Hart-Scott-Rodino reporting from $126.4 million to $133.9 million, effective February 17, 2026 (FTC notice in the Federal Register). Once a filing is complete, the parties wait 30 days before closing, or 15 days for a cash tender offer or bankruptcy. The same notice sets the 2026 filing fees by deal size:
| 2026 size of transaction | Filing fee |
|---|---|
| Less than $189.6 million | $35,000 |
| $189.6 million to less than $586.9 million | $110,000 |
| $586.9 million to less than $1.174 billion | $275,000 |
| $1.174 billion to less than $2.347 billion | $440,000 |
| $2.347 billion to less than $5.869 billion | $875,000 |
| $5.869 billion or more | $2,460,000 |
Deals between $133.9 million and $535.5 million are reportable only if the parties also meet the size-of-person tests. Most lower middle market deals, including the $15.9 million Harbor Supply example, fall well below the threshold and need no filing. A federal district court vacated the expanded HSR form introduced in February 2025, and the vacatur took effect on March 19, 2026, after the appeals court declined to stay it. The FTC now accepts filings on the form that was in place before February 10, 2025, and in March 2026 the FTC and DOJ asked for public comment on changes to the form, so counsel should confirm the current form before preparing a filing.
Operational diligence asks whether the business will perform the same way once the seller steps back.
The buyer's own books change on the closing date. Under ASC 805, the acquirer records the assets acquired and liabilities assumed, and since ASU 2021-08 it applies Topic 606 to "recognize and measure contract assets and contract liabilities in a business combination" instead of fair value (FASB ASU 2021-08). For private companies this applies to fiscal years beginning after December 15, 2023, so deferred revenue diligence feeds the opening balance sheet. Our ASC 805 business combinations guide covers the full acquisition method, and any goodwill recorded is later subject to the goodwill impairment test.
After closing, our post-merger integration checklist picks up from here.
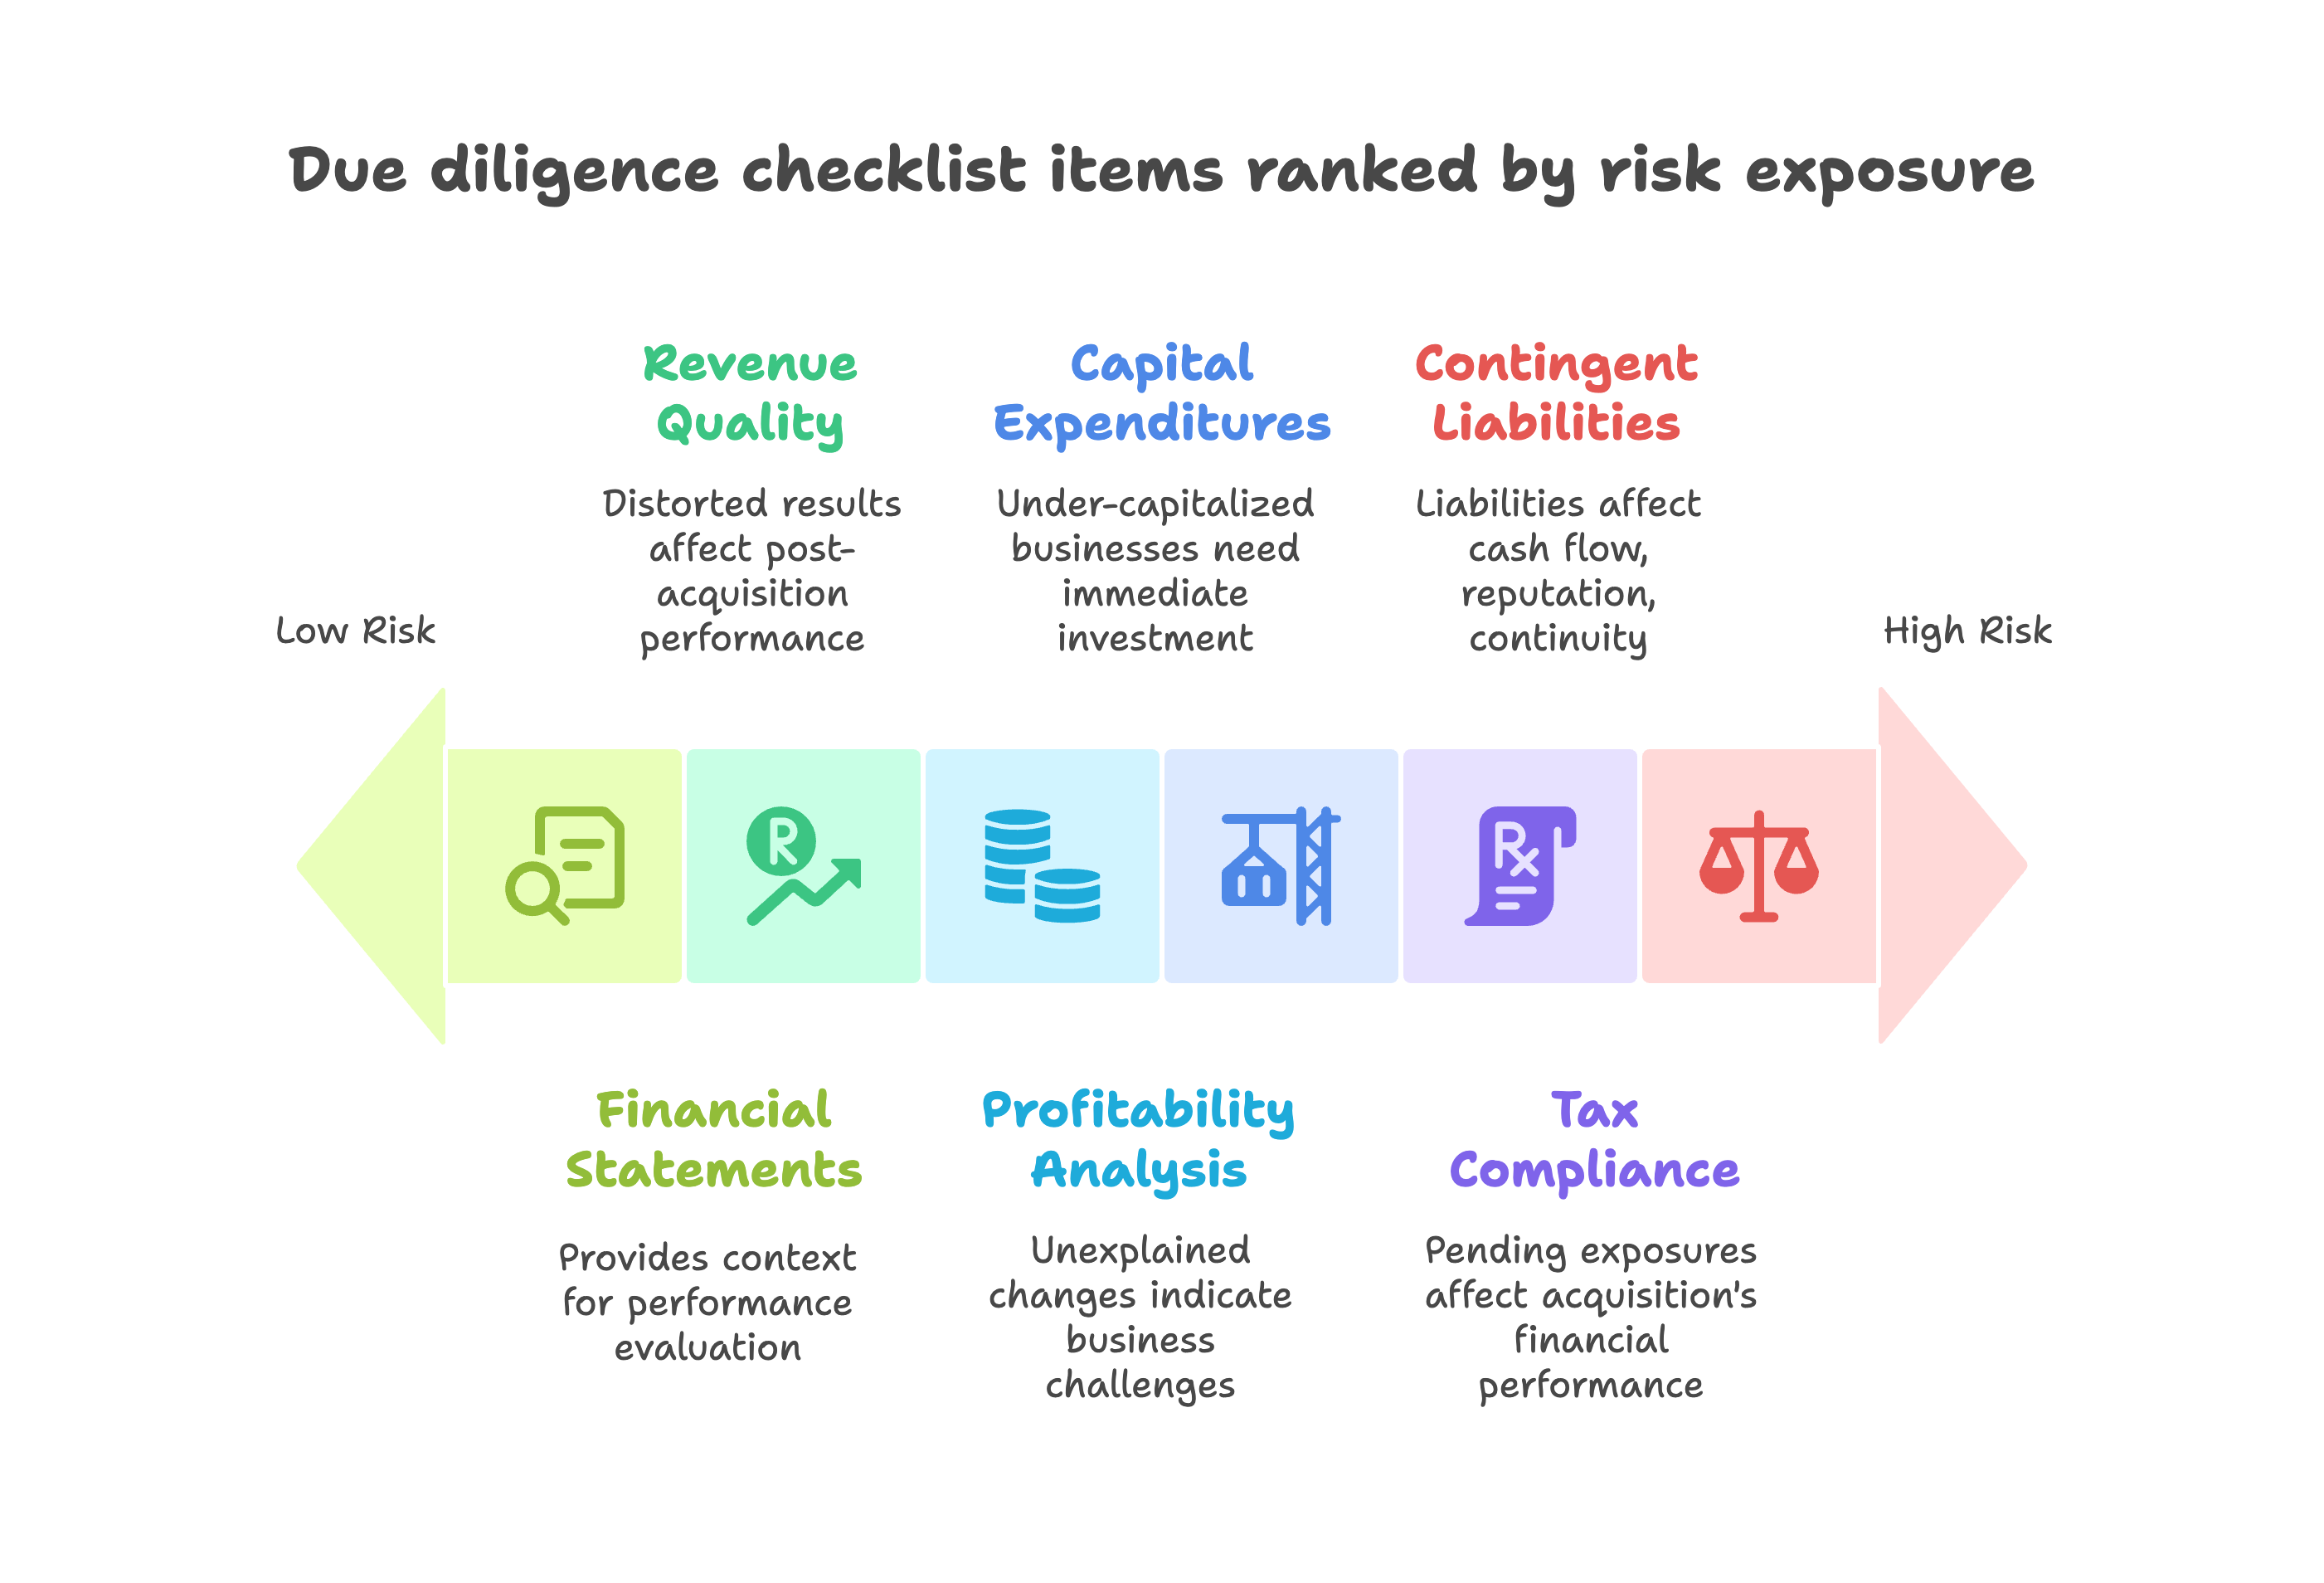
In practice, these findings often justify a price change or a specific indemnity:
What should an M&A due diligence checklist include? It should cover financial, tax, legal and operational workstreams. Each section lists the documents to request and the questions each answer should settle.
What is a quality of earnings report? A quality of earnings report restates EBITDA to show recurring, normalized profit. Buyers use the adjusted figure to set the price.
How long does M&A due diligence take? For a lower middle market company, buyers commonly plan for 45 to 90 days from signing the letter of intent. This is practitioner guidance, and the timeline depends mainly on how quickly the seller fills the data room.
Does my acquisition need an HSR filing in 2026? A filing is generally required when the transaction is valued above $133.9 million, the 2026 threshold that took effect on February 17, 2026, subject to size-of-person tests for deals up to $535.5 million. Filing fees start at $35,000. Confirm reportability with antitrust counsel.
Madras Accountancy supports buyers, sellers and CPA firms with the accounting work behind a deal, including ledger cleanup before a sale, financial analysis for diligence, tax preparation and CFO-level advisory. To talk through an upcoming transaction, contact our team.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



