



Management accounting services turn your reconciled books into a monthly set of internal reports that owners and managers use to run the business. A typical engagement covers a monthly management pack (profit and loss, balance sheet and cash view against budget), a short list of KPIs, written variance analysis and a rolling forecast.
For small and mid-size businesses, management accounting services sit between bookkeeping and a part-time CFO. The bookkeeper makes sure transactions are recorded correctly. The management accountant takes those numbers, compares them with the plan and explains to leadership what changed and what to do about it. This guide sets out what the service should include, how it differs from compliance work, what the monthly analysis looks like in practice and how to scope an engagement in 2026.
The US Bureau of Labor Statistics describes management accountants in its Occupational Outlook Handbook as people who "combine accounting and financial information to guide business decision making." It adds that the information they prepare "is intended for internal use by business managers, not for the public," and that they "often prepare budgets and evaluate performance."
That internal audience shapes everything about the work. Management accounts have no prescribed format, so they can be cut by location, product line, customer or project. They are usually produced monthly, within days of the month-end close, so leadership can act while the information is still current. They also mix financial data with operating data such as headcount, units shipped, billable hours or customer counts.
The IRS makes a related point from the record-keeping side. Publication 583 says "You need good records to monitor the progress of your business" and that records "can show whether your business is improving, which items are selling, or what changes you need to make." Management accounting is the discipline that turns those records into regular answers.
The scope varies by industry and size, but most engagements for growing businesses are built from the same six components.
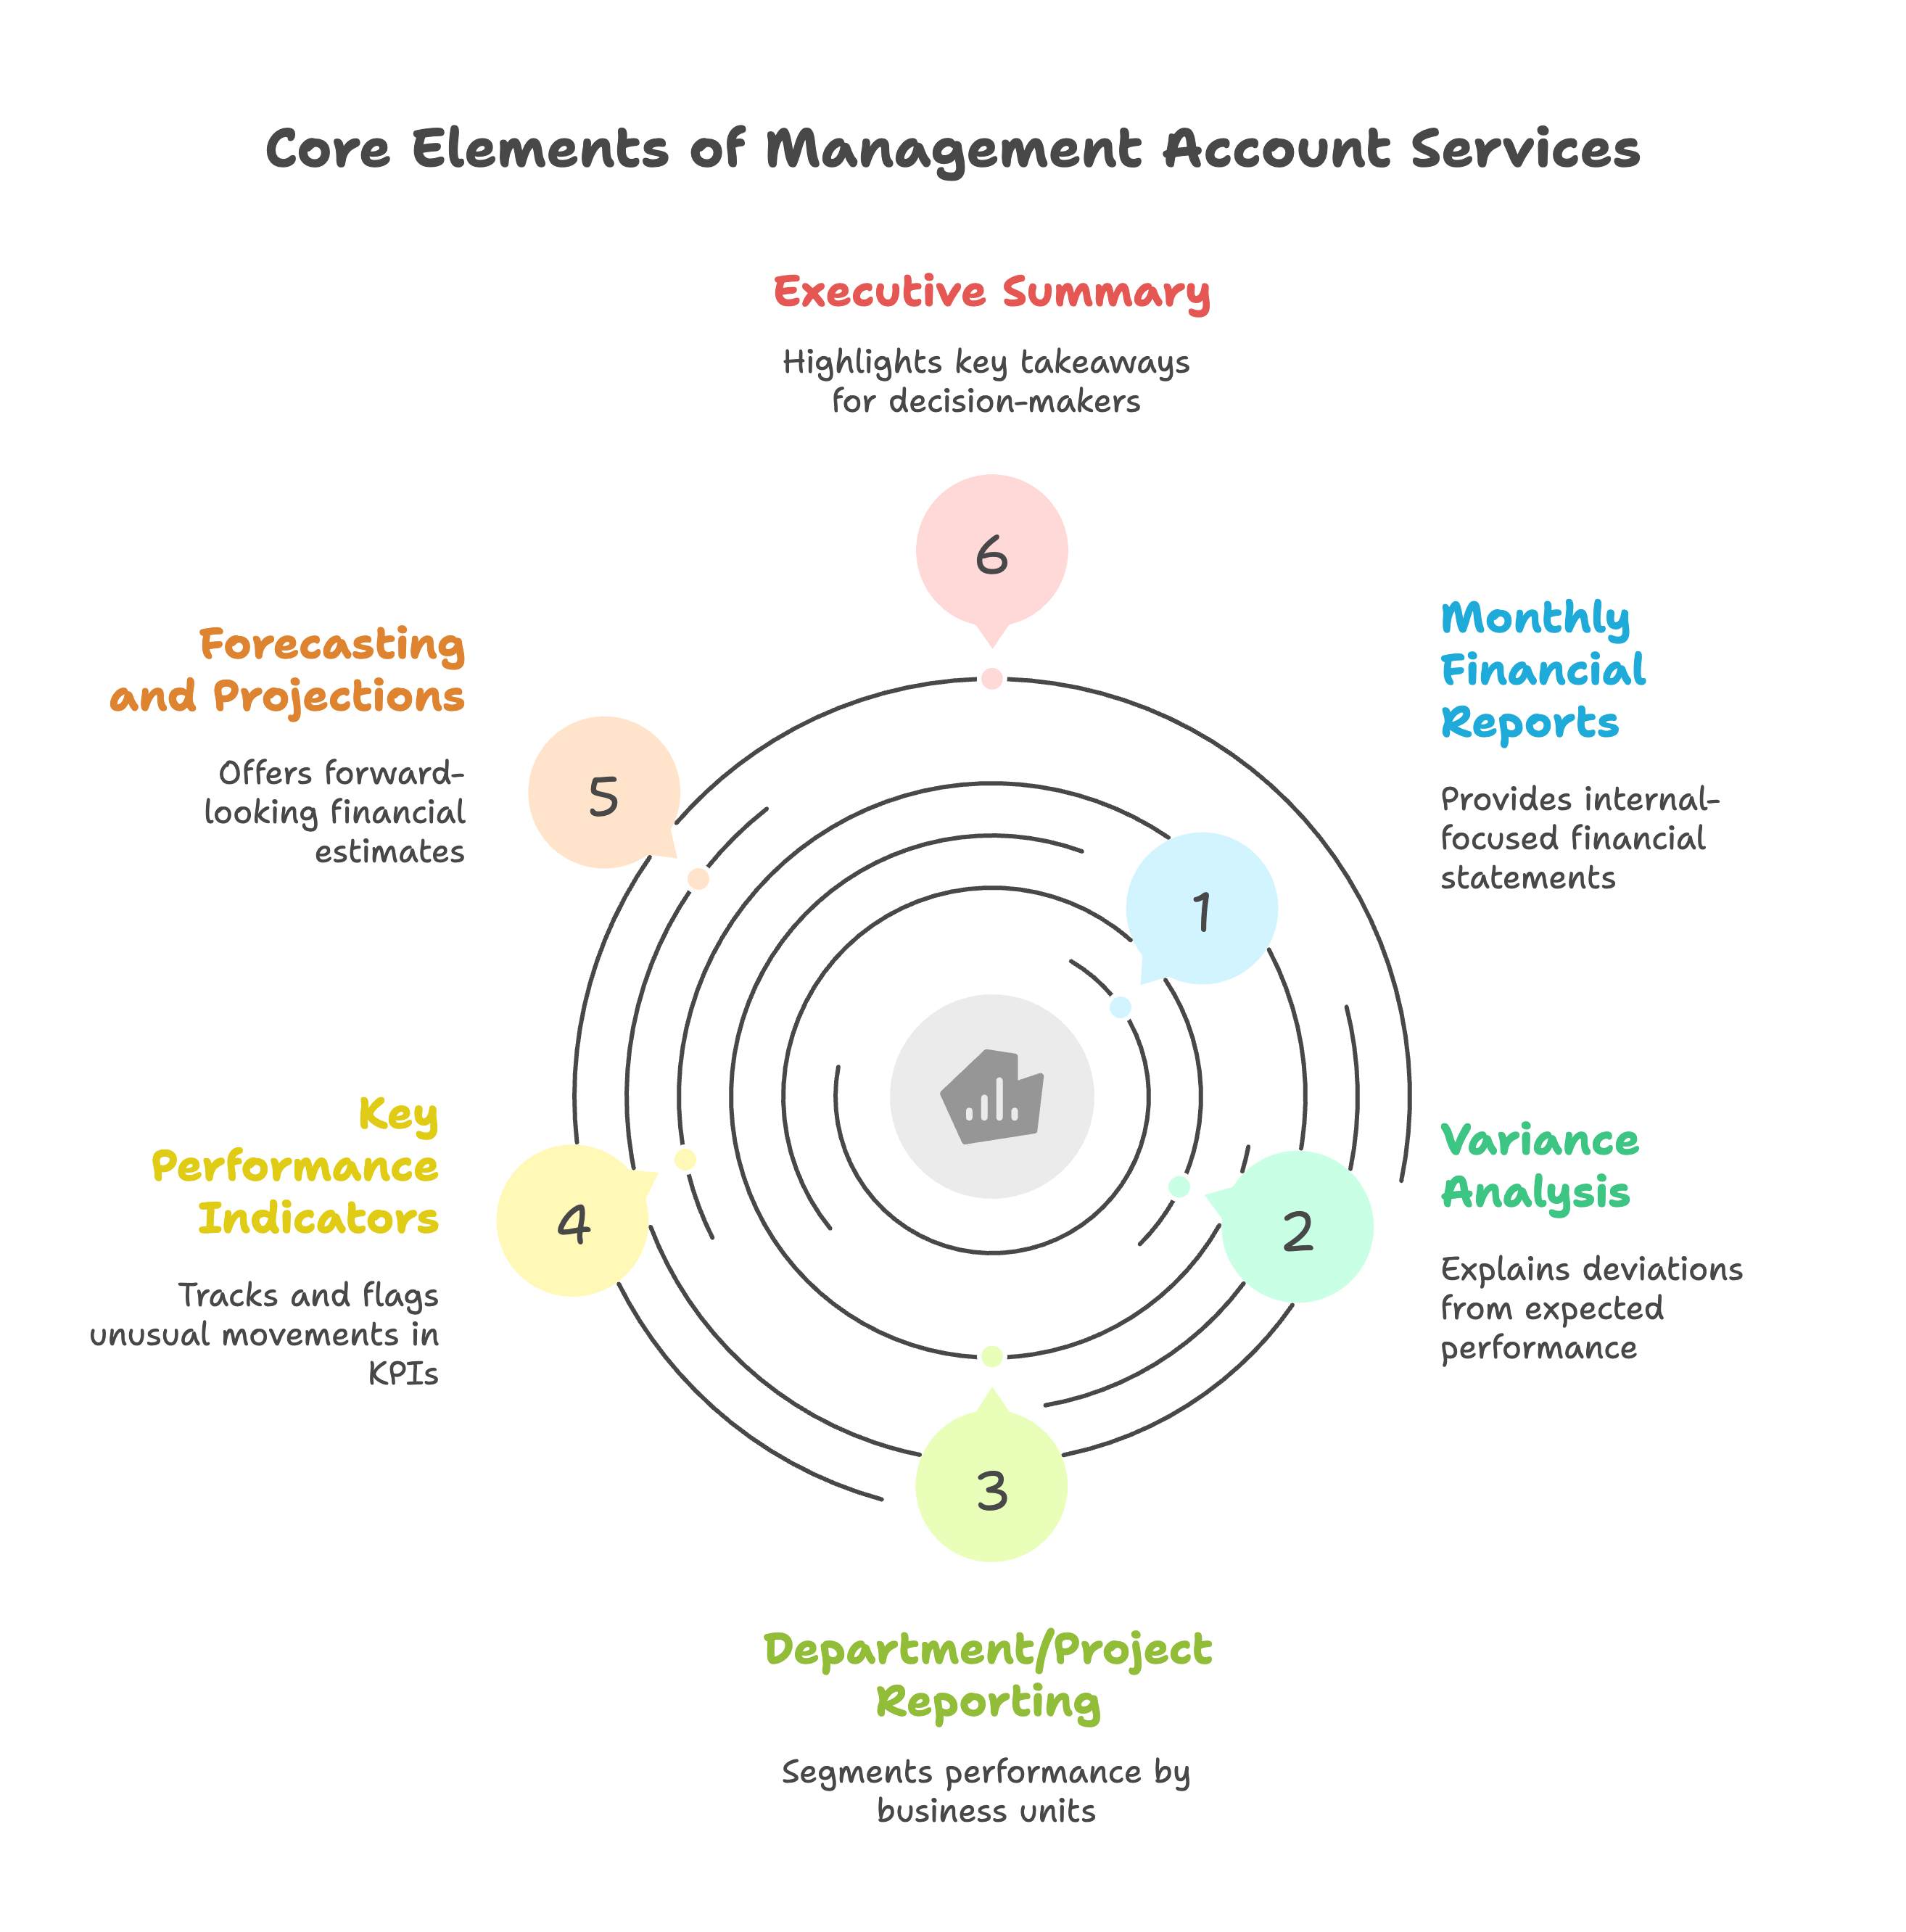
The pack is the core deliverable. It normally contains a profit and loss statement for the month and year to date, a balance sheet, a cash flow view and budget versus actual columns, with prior-year or trailing-month comparisons so trends are visible. If you want the page-by-page layout, our guide to management reporting package contents walks through each schedule. Owners who are less comfortable with the statements themselves can start with how to read financial statements.
Variance analysis explains why results differ from budget or forecast. Good commentary separates timing differences (an invoice that slipped into next month) from permanent ones (a price increase from a supplier) and quantifies each. A worked example appears below, and our article on variance analysis best practices covers thresholds and investigation methods in more depth.
Once a business has more than one location, service line or major project, a consolidated P&L hides the detail that matters. Segmented reporting shows which units carry the business and which ones need attention. Multi-unit operators in particular depend on this; our guide to outsourced accounting for franchise businesses shows how location-level reporting is typically structured.
A management accountant tracks a small set of indicators each month and flags unusual movement. Common examples for small and mid-size businesses include gross margin, operating expense as a percentage of revenue, days sales outstanding, inventory turnover, revenue per employee and cash runway. The right set depends on the business model, and our list of essential KPIs for small business financial performance gives formulas and a worked example.
Forward-looking work separates management accounting from routine reporting. The service usually maintains the annual budget and a rolling forecast that is updated each month with actual results, plus a cash forecast for the next quarter or longer. Our guide to cash flow forecasting for business covers methods for the cash side.
Each pack should open with a one-page summary in plain English: what happened in the month, the two or three variances that matter, any KPI outside its target range and the decisions leadership needs to make. Busy owners often read only this page, so it needs to stand on its own.
Management accounting depends on the other functions. It cannot start until the books are reconciled, and it uses the same ledger that feeds the year-end financial statements and tax return. The table below sets out how each function differs.
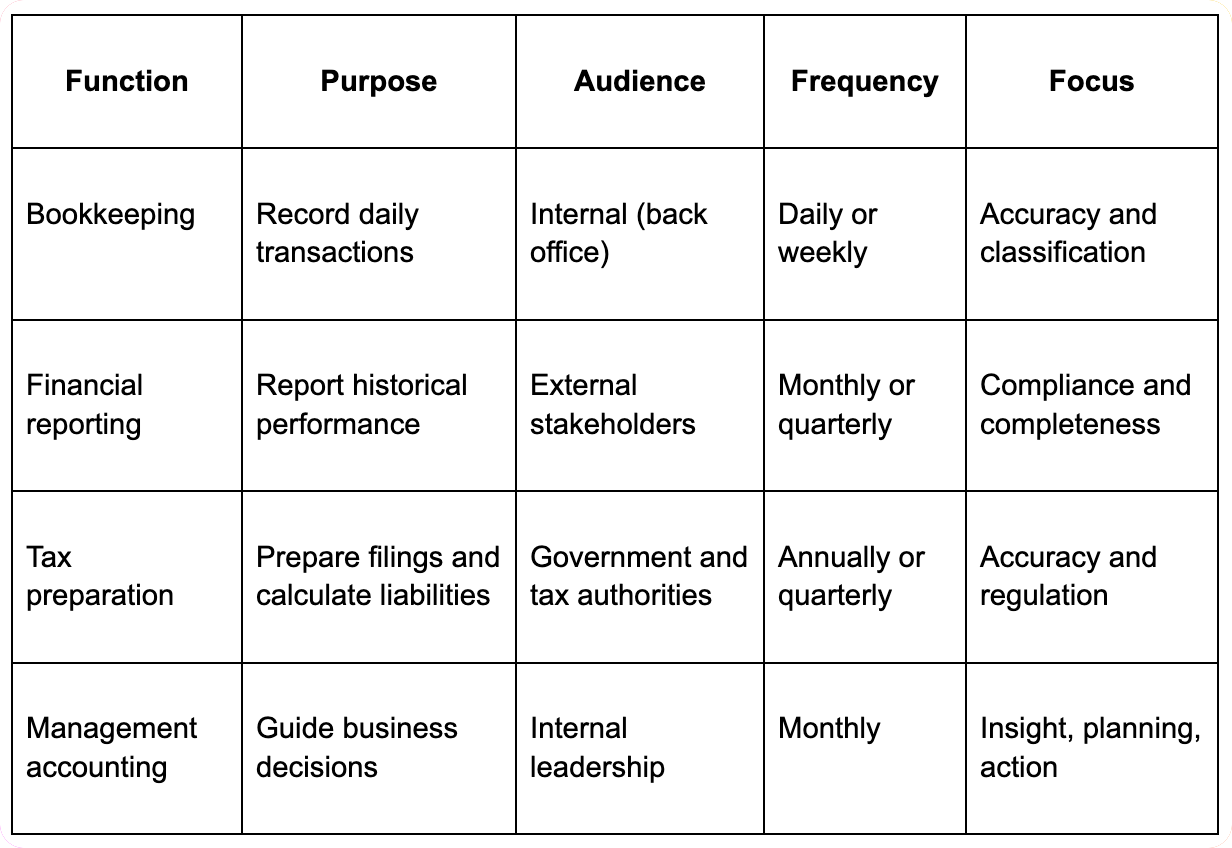
| Function | Main question | Audience | Typical frequency |
|---|---|---|---|
| Bookkeeping | Are transactions recorded and reconciled? | Internal finance staff | Daily or weekly |
| Financial reporting | What were the results under the applicable framework? | Lenders, investors, owners | Quarterly or annually |
| Tax preparation | What is owed and how is it filed? | IRS and state tax agencies | Quarterly estimates, annual returns |
| Management accounting | What changed against plan and what should we do next? | Owners, managers, board | Monthly |
Consider a distributor with a monthly revenue budget of $250,000 and a budgeted gross margin of 40%. Here is a simplified September view from its management pack.
| Line | Budget | Actual | Variance | Variance % |
|---|---|---|---|---|
| Revenue | $250,000 | $232,000 | ($18,000) | (7.2%) |
| Cost of goods sold | $150,000 | $141,520 | $8,480 lower | (5.7%) |
| Gross profit | $100,000 | $90,480 | ($9,520) | (9.5%) |
| Gross margin | 40.0% | 39.0% | (1.0 pt) | |
| Operating expenses | $70,000 | $74,300 | ($4,300) | 6.1% over |
| Operating profit | $30,000 | $16,180 | ($13,820) | (46.1%) |
A bare table says operating profit came in $13,820 below budget. The management accountant's job is to break that down so leadership knows where to act.
The pack would then link the variance to the balance sheet. If receivables at month end were $290,000 on $232,000 of monthly revenue, days sales outstanding on a 30-day month is roughly 37.5 days ($290,000 / $232,000 x 30). A rising DSO alongside falling revenue tells the owner to look at collections before cutting costs.
Management accounts are internal, but the forecast still needs to reflect tax cash flows, and the One Big Beautiful Bill Act (OBBBA) changed two items that affect capital spending and R&D plans.
Your tax adviser should confirm how each provision applies to your facts. The management accountant's role is to carry the expected effect into the cash forecast so there are no surprises when estimated payments are due. These rules are current as of October 2026.
Not every business needs a full monthly pack. The service adds the most value in these situations:
A clear scope prevents the common failure where the pack arrives late and nobody reads it. Agree the following before work starts.
The SBA's manage your finances guide, in its advice on adjusting a business's direction, puts the habit simply: "Review financials, short-term goals, and long-term goals and make appropriate adjustments." A monthly management pack is the structured way to do that.
For CPA firms, management accounting services are a natural extension of client accounting work, since the firm already maintains the ledger. Firms that add the service usually run it as a recurring monthly engagement with a standard pack template, a fixed close calendar and a partner or manager review. The main constraint is staff time during busy season, which is why many firms use an outsourced or offshore team to prepare packs while the firm keeps the client meeting. Our client accounting services guide for accounting firms covers how this fits into a wider CAS offering.
What is the difference between management accounts and financial statements? Financial statements report results to outside parties under an accounting framework, usually quarterly or annually. Management accounts are internal monthly reports with budget comparisons, KPIs and commentary, built from the same ledger but designed for decisions.
How often should a small business produce management accounts? Monthly is the norm, because it gives leadership time to correct course within the quarter. Very small businesses sometimes start quarterly and move to monthly once they have a budget to compare against.
Do management accounts need to follow GAAP? There is no rule requiring internal reports to follow GAAP, but most businesses prepare them on the same accrual basis as their year-end statements so the numbers reconcile. If lenders receive the reports, check the loan agreement for any required basis.
What do I need in place before starting management accounting services? You need books that are reconciled every month, a chart of accounts that supports the segments you want to see and, ideally, an annual budget. Without a budget, the first pack can compare against the prior year while the budget is built.
Who should prepare management accounts? In smaller businesses, an outsourced accountant or controller typically prepares the pack and a fractional CFO or the owner reviews it. Larger businesses usually have an in-house controller with FP&A support.
Madras Accountancy supports US CPA firms and their clients with bookkeeping, month-end close, management reporting, budgeting and forecasting support. To discuss what a monthly management pack for your firm or your clients would cover, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



