


This multi-state tax compliance guide for growing businesses starts from a simple fact: every state decides for itself when you owe it tax, and the triggers differ by tax type. A company can owe sales tax in a state where it owes no income tax, payroll tax where it sells nothing, and a franchise or gross receipts tax that applies even in a loss year. Exposure usually builds quietly through remote sales, a remote hire or inventory sitting in a third-party warehouse, and it surfaces at the worst time: a state notice, a lender review or buyer due diligence.
Nexus is the connection that lets a state require you to register, collect or file. There are two families of tests.
Physical presence. An office, employee, contractor working on your behalf, property, or inventory in the state. Inventory held by a fulfillment provider counts, which catches many e-commerce sellers who never chose to be in that state.
Economic presence. Since the Supreme Court's 2018 decision in South Dakota v. Wayfair, states can require out-of-state sellers to collect sales tax based on sales volume alone. Every state with a statewide sales tax now has an economic nexus rule. Many states apply similar logic to income and franchise taxes, using receipts thresholds of their own.
Nexus is tested separately for each tax. Our deeper post on economic nexus for growing businesses walks through the sales tax tests state by state.
Most states use $100,000 of sales into the state over the current or prior year. A shrinking group also counts 200 or more transactions, and several large states set a higher bar.
| State | Threshold | Notes |
|---|---|---|
| California | $500,000 of sales of tangible personal property | No transaction test; current or preceding calendar year (CDTFA) |
| Texas | $500,000 of Texas revenue | Preceding 12 calendar months; collect by the first day of the fourth month after crossing (Texas Comptroller) |
| New York | $500,000 of sales and more than 100 sales | Both tests must be met, over the preceding four sales tax quarters |
| Florida | $100,000 of taxable remote sales | Prior calendar year; no transaction test |
| Illinois | $100,000 of gross receipts | 200-transaction test eliminated from January 1, 2026 |
| Most other states | $100,000 | Some still add a 200-transaction alternative |
Thresholds change. Illinois, Utah and others have dropped transaction counts in the last two years, and states differ on whether exempt and marketplace sales count toward the total. Check each state's revenue department before relying on any table, including this one.
Marketplace sales. Every sales tax state now has a marketplace facilitator law, so Amazon, Etsy and similar platforms collect on sales they facilitate. You may still need to register if your direct sales cross the threshold, and some states count marketplace sales toward your threshold even though the platform remits the tax.
You register, collect tax from customers at the correct rate (often destination-based, which means local rates too), file returns on the schedule the state assigns, and keep exemption documentation. Taxability is where states diverge most. Prewritten software delivered electronically and SaaS are taxable in some states, such as New York and Washington, and not in others, such as California. Texas taxes SaaS as a data processing service on 80% of the charge. Our post on whether SaaS is taxable and where covers the state split.
If you sell to resellers or exempt organizations, the exemption certificate is your audit defense. A missing or expired certificate turns an exempt sale into tax you owe yourself. See managing sales tax exemptions and resale certificates.
Use tax is the other side: when your business buys taxable items without paying sales tax (an out-of-state vendor that didn't charge it), you owe use tax to your home state.
Income tax nexus follows physical presence, and in many states also economic presence based on receipts. One federal protection matters here. Public Law 86-272 bars a state from imposing a net income tax on a seller whose only in-state activity is soliciting orders for tangible personal property that are approved and shipped from outside the state. It does not cover services, SaaS or other intangibles, and it does not apply to sales tax or gross receipts taxes. States have also narrowed what counts as protected internet activity, so a website feature that does more than solicit orders can create exposure.
Some states tax the privilege of doing business regardless of profit. Texas imposes a franchise tax on margin, with an economic nexus threshold of $500,000 of Texas gross receipts. Washington's business and occupation tax and Ohio's commercial activity tax are gross receipts taxes with their own thresholds. Delaware's franchise tax applies to entities formed there even if they operate nowhere near Delaware; our guide to Delaware franchise tax requirements explains the two calculation methods.
One remote employee in a new state typically means registering for state income tax withholding and state unemployment insurance there, and sometimes paid family leave or disability programs. That employee can also create income tax nexus for the company. Watch for states such as New York that apply a "convenience of the employer" rule, taxing nonresident employees who work remotely for a New York employer by choice rather than necessity. Our post on multi-state payroll taxes and what employers need to get right covers reciprocity agreements and withholding rules, and setting up payroll and taxes for remote workers covers the registration steps.
A multistate corporation does not pay each state tax on all of its income. Each state applies a formula to take a share. Historically that formula averaged property, payroll and sales. Most states now use a single sales factor, so the share of your receipts sourced to the state drives the result.
Sourcing rules matter as much as the formula. For services and SaaS, most states now use market-based sourcing (where the customer receives the benefit), while a minority still use cost of performance (where the work is done). Two states can each claim the same receipts, which creates double taxation; the reverse can leave income taxed nowhere, and some states use throwback rules to pull it back.
A software company has $10 million of taxable income and $40 million of revenue, with $4 million of receipts sourced to State A under market-based sourcing. State A uses single sales factor apportionment, so its share is $4 million divided by $40 million, or 10%. State A taxes $1 million of income. If State A instead used cost of performance and all engineering sits in another state, its share could be close to zero. The company's revenue is identical in both cases; only the sourcing rule changed.
For S corporations and partnerships, state income tax often flows to owners, who then file nonresident returns in every state where the business has nexus. Many states allow or require composite returns or withholding on nonresident owners instead.
Most states with an income tax also offer a pass-through entity tax (PTET) election. The entity pays the state tax and deducts it federally, which the IRS accepted in Notice 2020-75. The One Big Beautiful Bill Act raised the individual SALT deduction cap to $40,000 for 2025 and $40,400 for 2026, reduced for incomes above $500,000 ($505,000 in 2026), and it left the PTET route intact. For owners above the phase-down range, PTET remains the main way to deduct state tax. Our explainer on how the pass-through entity tax turns state tax into a federal deduction covers elections and deadlines.
Register before you collect. Collecting tax without a permit creates a separate problem, because you are holding money the state has no account to receive. Typical steps:
The Streamlined Sales Tax registration system lets sellers register in all of its member states with one application, and qualifying volunteer sellers can use a certified service provider at the states' expense.
Most growing companies find at least one state where they should have registered earlier. A voluntary disclosure agreement (VDA) is usually the cleanest fix: you come forward before the state contacts you, pay tax and interest for a limited lookback period, and the state typically waives most penalties. For sales tax you didn't collect, the tax comes out of your margin, which is why earlier is cheaper. Our guide to sales tax voluntary disclosure agreements covers the process.
Automation helps with rates and filing, but it only knows what you tell it. Our comparison of sales tax automation software covers the main tools, and a small business tax compliance calendar helps track federal dates alongside state ones.
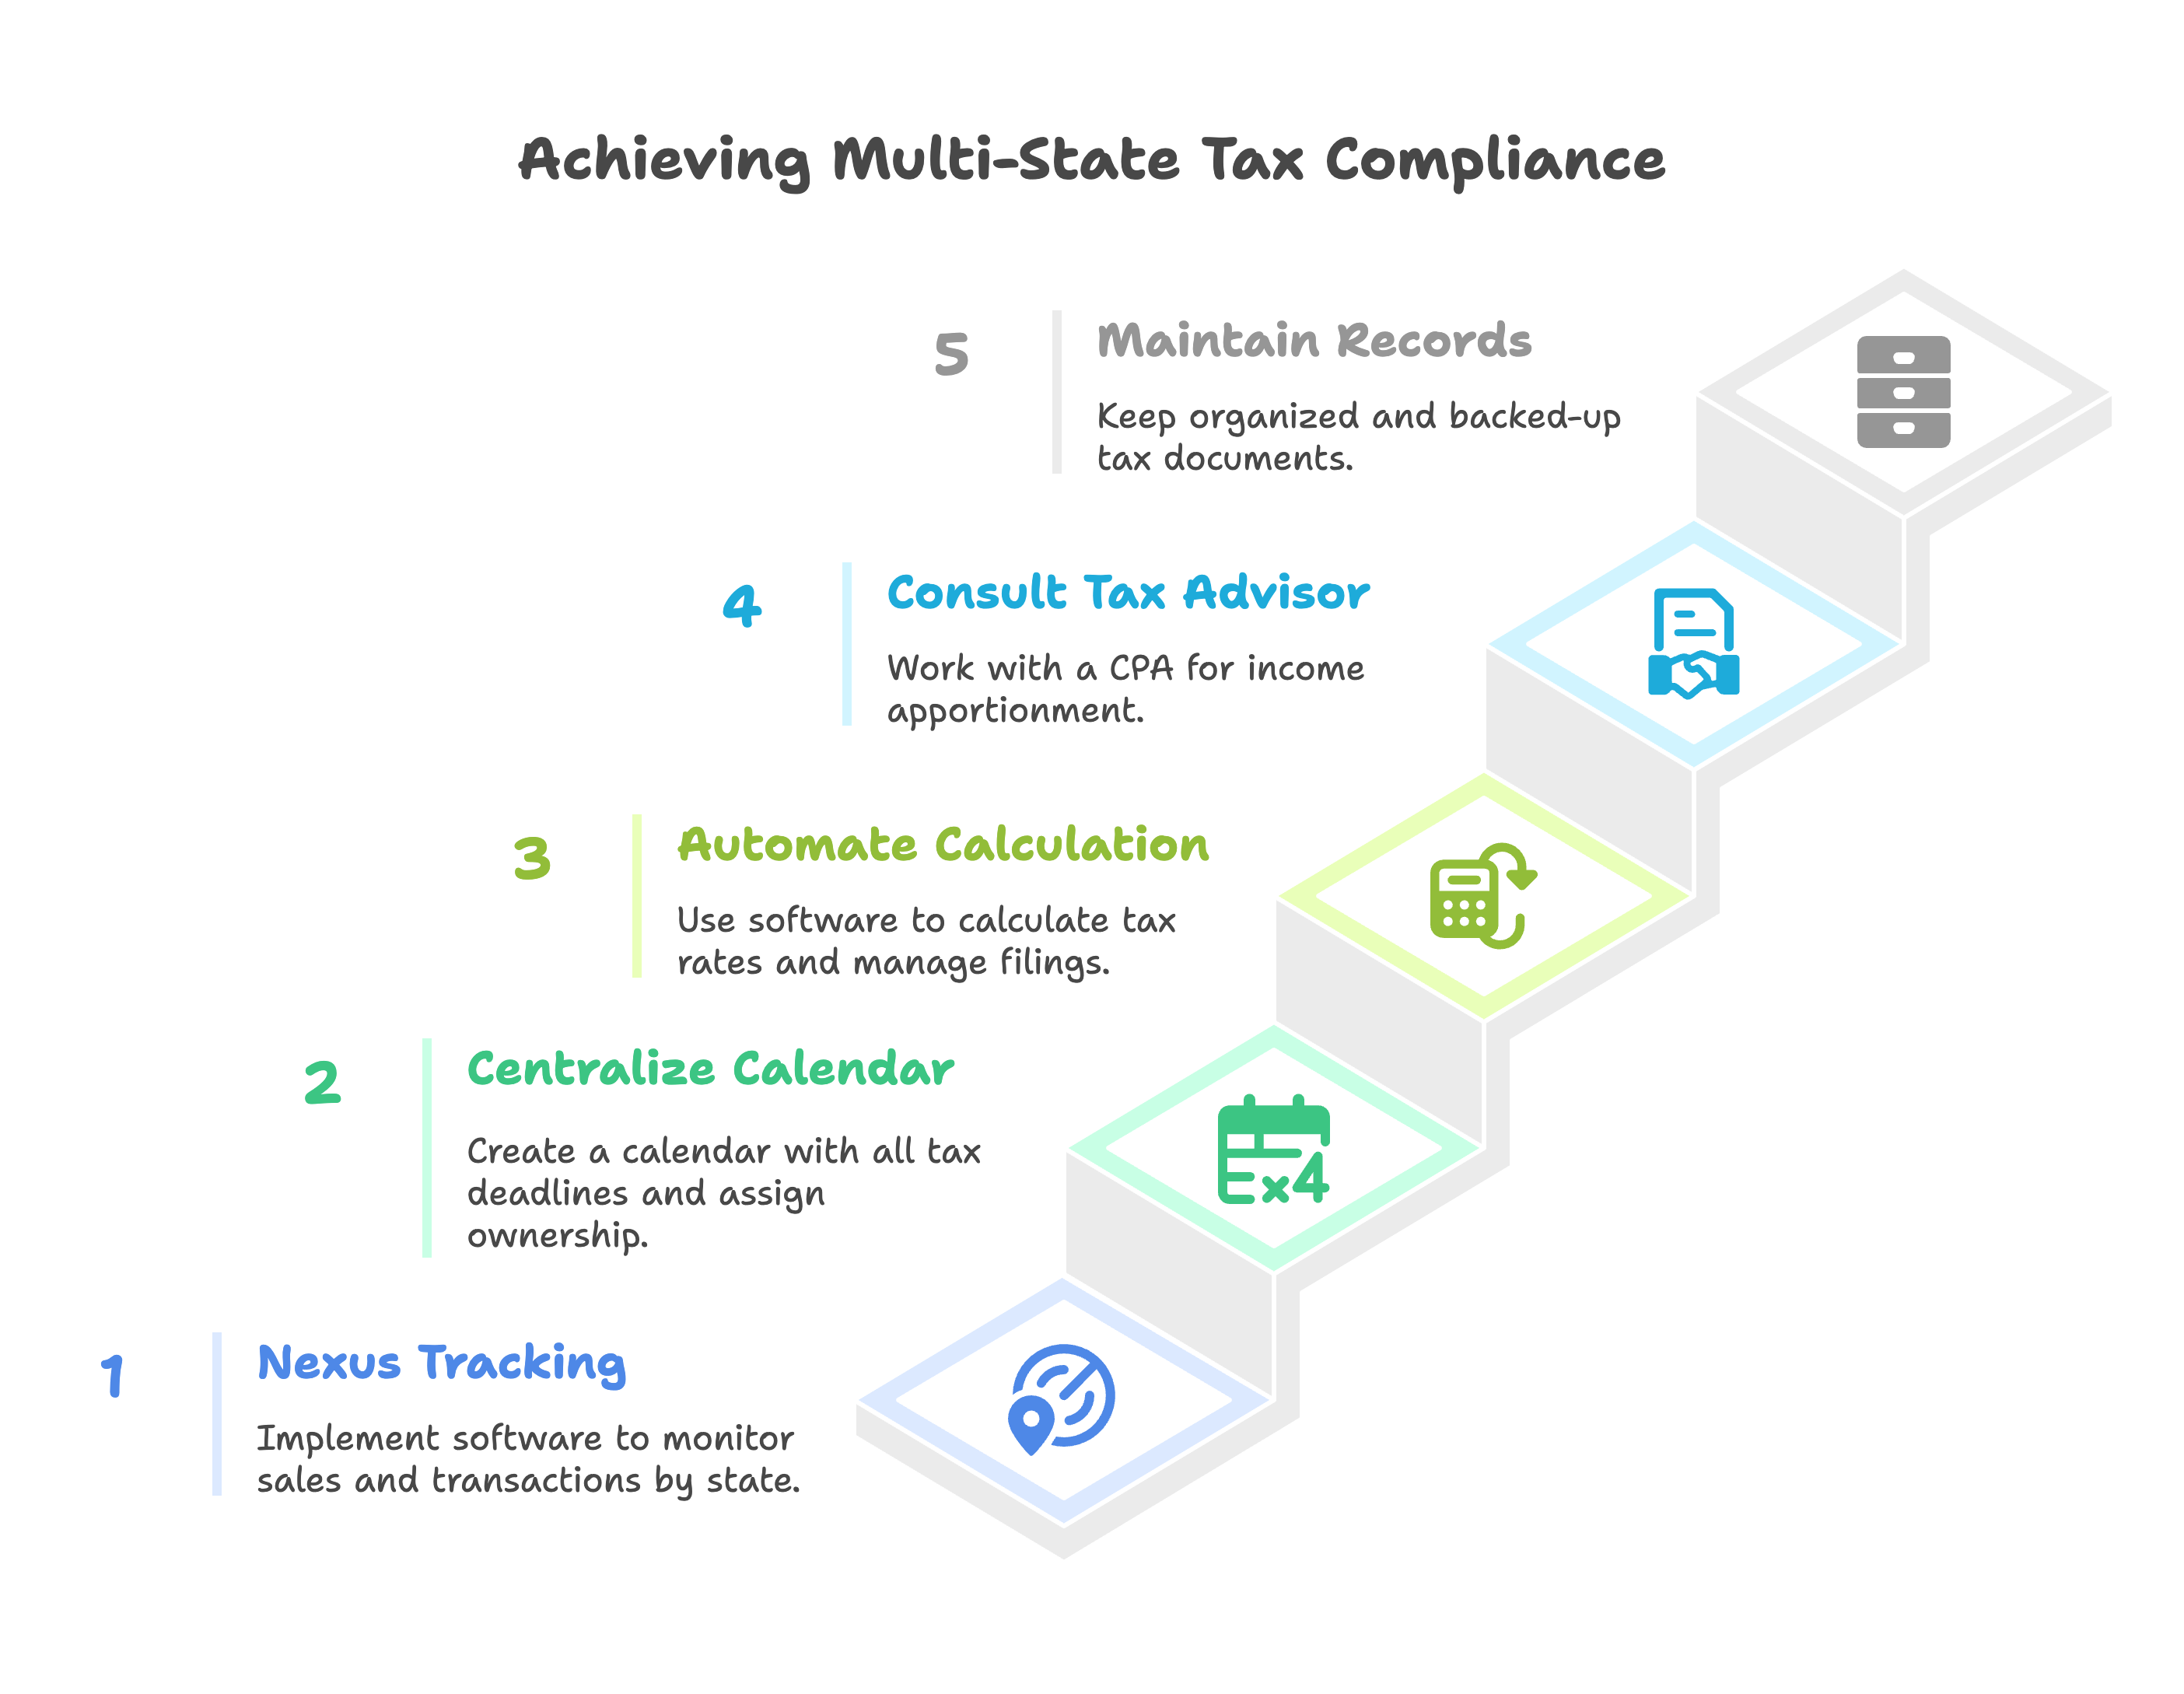
The work scales with the number of states, not with revenue. A company filing sales tax in three states might handle 36 monthly returns a year; at fifteen states, with a mix of monthly and quarterly schedules, plus nonresident owner filings and payroll accounts, the calendar becomes a full-time job. Outsourcing usually makes sense when one of these is true:
A good provider handles the routine filings and also flags changes: a new threshold, a product that becomes taxable, an employee who moved. CPA firms face the same capacity question for their clients; our post on outsourcing multi-state sales tax compliance for CPA firms covers how firms structure that work. Keep decision-making in-house even when filing is outsourced. Someone at the company should approve new registrations, VDAs and PTET elections, because each one affects owners and cash.
Give them sales by state and by product for the last three to four years, a list of where employees and contractors work, inventory locations including third-party warehouses, existing registrations and account numbers, recent state notices, and copies of exemption certificates on file. With that, a nexus study can usually be scoped quickly, and gaps show up before filings begin.
No. You collect only where you have nexus and the product is taxable. A business below every economic threshold, with no physical presence outside its home state, may collect in one state only. Track sales by state monthly so you know when that changes.
In most states, yes, because an employee working there is a physical presence. Whether it leads to income tax liability depends on the state's rules and on whether Public Law 86-272 protects your activities. Payroll registration is required either way.
If you never filed, the statute of limitations generally never started, so a state can look back indefinitely. A voluntary disclosure agreement typically limits the lookback to a set number of years, often three or four, which is its main advantage.
There is no single return for sales or income tax. Streamlined Sales Tax registration simplifies sign-up in member states, and composite returns can cover nonresident owners in some states, but each state still receives its own filings.
Madras Accountancy works with CPA firms and growing businesses on nexus reviews, state registrations, sales tax filing and multi-state return preparation. If you have added states, products or remote staff this year and want your exposure mapped before a state does it for you, contact our team.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



