



Outsourced accounting services move some or all of your finance work, from bookkeeping and payroll to month-end close, reporting and tax support, to an external team that works inside your systems. For a US business, that usually means a provider runs the ledger and delivers monthly financials while you keep approval of payments and strategic decisions. For a CPA firm, it means extra preparers and reviewers who take on client work under the firm's own quality control.
The decision is mostly about capacity, controls and cost. Below are the services you can expect, how outsourcing compares with hiring, how the transition works, and the questions that separate a reliable provider from a risky one.
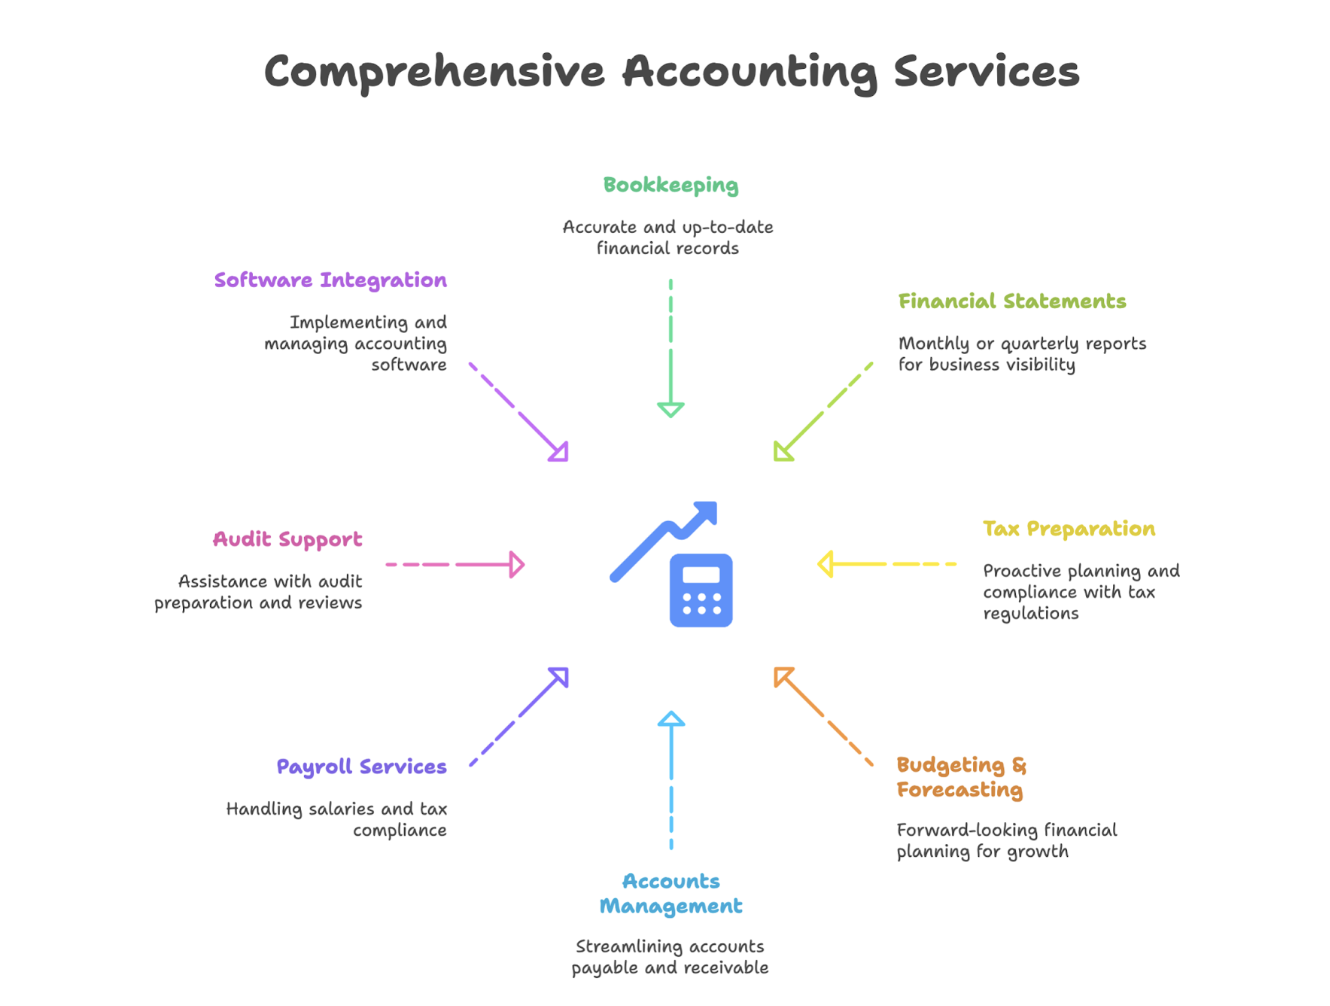
Providers package work in layers. You can buy one layer or several, and the right mix depends on transaction volume, reporting needs and whether you already have a finance lead.
| Layer | Typical deliverables | Usually suits |
|---|---|---|
| Bookkeeping | Transaction coding, bank and card reconciliations, AP and AR entry | Owner-run businesses, early-stage startups |
| Controller | Month-end close, accruals, revenue recognition, financial statements, internal controls | Companies with $2M+ revenue, lender or investor reporting |
| CFO / FP&A | Budgets, forecasts, cash planning, board packs, pricing and KPI analysis | Growth-stage companies, fundraising or acquisitions |
| Tax and compliance | Business and individual returns, sales tax, 1099s, payroll filings | Most businesses, often paired with bookkeeping |
| CPA firm support | Return preparation, bookkeeping for firm clients, audit support workpapers | Accounting firms during busy season or year-round |
Most engagements start with bookkeeping and close, then add controller or CFO work as the business grows. Our page on outsourced bookkeeping services for small businesses covers the first layer in more depth, and fractional CFO services covers the top one.
Even with a full outsourced team, keep these decisions and assets in-house:
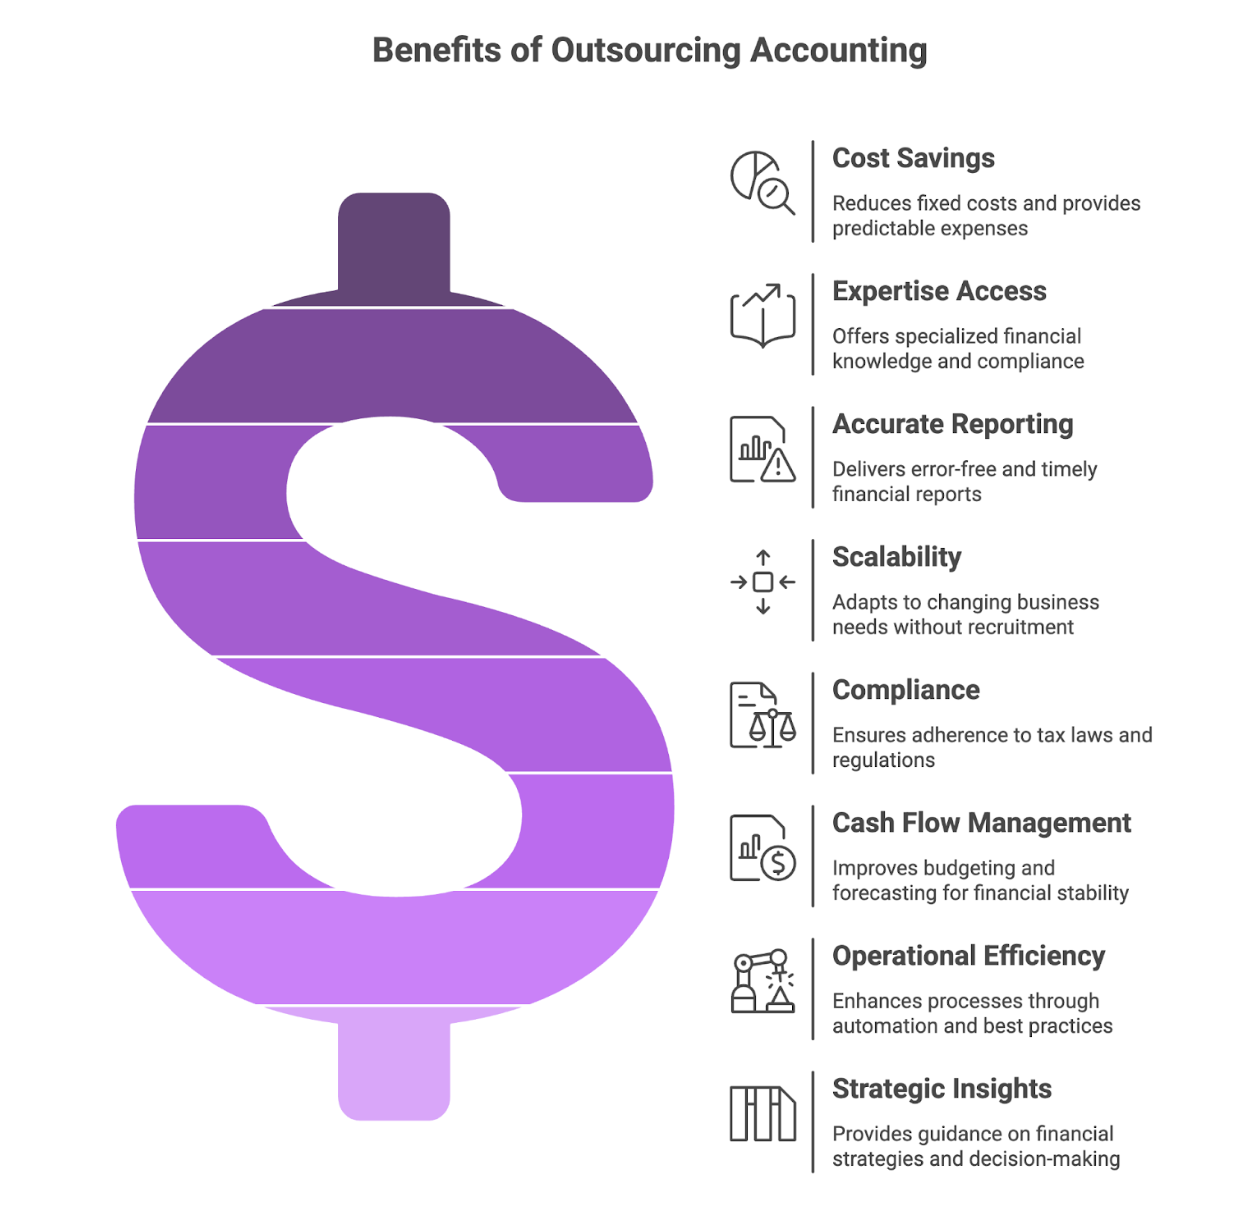
The US Bureau of Labor Statistics puts the median pay for accountants and auditors at $83,680 in May 2025. Add the employer's 7.65% share of Social Security and Medicare and one median hire costs about $90,000 before health insurance, retirement contributions, software seats, recruiting fees and the manager time spent reviewing their work.
That single hire also leaves gaps. One person cannot segregate duties, so the same employee records bills, pays them and reconciles the bank account. When they take leave or resign, the close stops. And a staff accountant rarely brings controller-level judgment on revenue recognition or CFO-level forecasting.
| Factor | One in-house hire | Outsourced team |
|---|---|---|
| Cost structure | Fixed salary plus benefits and payroll taxes | Monthly fee tied to scope and volume |
| Coverage during leave or turnover | Work stops | Team continuity built in |
| Segregation of duties | Hard with one person | Preparer and reviewer are different people |
| Skill range | One person's experience | Bookkeeper, reviewer, controller as needed |
| Ramp time | Recruiting plus training, often months | Onboarding, usually weeks |
| Control of data | Fully internal | Shared, governed by access rules and contract |
Outsourcing is not cheaper in every case. A business with steady volume and an experienced in-house controller may get better value from adding a junior hire. For a line-by-line cost model, see how much it costs to outsource accounting services and our 2026 in-house vs outsourced cost breakdown.
Two or more of these usually means the cost of not outsourcing is already showing up in late decisions, penalties or cleanup fees.
A well-run transition follows a predictable sequence. At Madras Accountancy, onboarding typically takes one to three weeks depending on how clean the existing books are.
Our first 90 days onboarding plan shows what each month of a new engagement should look like, including how preparer and reviewer roles split across time zones.
A defined close calendar is the clearest sign that a provider runs a real process. A typical monthly cycle for a small or mid-sized business looks like this:
| Business day after month-end | Deliverable |
|---|---|
| Days 1 to 3 | Bank, credit card and payment processor reconciliations |
| Days 3 to 5 | AP and AR cutoff, accruals, prepaid and depreciation entries |
| Days 5 to 8 | Balance sheet account reconciliations and reviewer sign-off |
| Days 8 to 10 | Financial statements, variance commentary and open-items list |
| Monthly call | Review of results, cash position and upcoming filings |
Smaller engagements may run on a 15-day calendar, and companies with lender covenants or investor reporting often need a tighter one. The point is that dates are agreed in advance and missed dates are visible. Our 5-day AP, AR and reconciliation SOPs show what a faster close requires from both sides.
Four pricing models are common, and each puts risk in a different place:
Ask every provider to put the scope, assumptions and change-order process in the engagement letter. Most fee disputes start with an undocumented assumption about volume or deliverables.
Handing your ledger, payroll and bank data to a third party is the biggest worry most owners raise, and it is the right one to raise first. Ask for documents you can review:
Our SOC 2 Type II guide for secure outsourcing explains how to read the report and what exceptions mean.
CPA firms use outsourced accounting services differently from businesses. The firm keeps the client relationship and signs the work, while the outsourced team prepares returns, bookkeeping or workpapers for the firm's review.
Two compliance points apply before any client data moves:
Firms building a client accounting services practice on outsourced capacity can find the operating model in our article on CAS outsourcing for CPA firms.
Price comparisons are easy. The questions that predict a good engagement are harder:
Our 30-point accounting outsourcing due diligence checklist turns these into a scoring sheet. If you are comparing offshore providers specifically, the buyer's guide to accounting outsourcing companies in India covers delivery models and pricing structures.
Loss of visibility. With a competent provider you get a close calendar, a monthly reporting pack and live access to the ledger, so you see the same numbers your accountants see.
Time zones. Offshore teams working overnight can turn around reconciliations and entries before your morning. The tradeoff is less real-time chat, which a scheduled overlap window of two or three hours usually resolves.
Quality. Ask how errors are caught before you see them. Documented checklists, a second-level review and tracked error rates are the minimum.
Disruption. Most disruption comes from messy starting books, not the handover itself. Budget for cleanup and the steady-state work tends to settle quickly.
For larger companies thinking about moving the entire finance function rather than individual tasks, see the guide to outsourcing your company's finance department.
Bookkeeping covers recording and reconciling transactions. Outsourced accounting adds the close, accrual entries, financial statements, compliance filings and analysis. Many providers sell both, with accounting priced higher because it needs more senior review.
Yes. The outsourced team keeps the books and produces year-end financials, and your CPA prepares the return from clean records. Many CPAs prefer this because it cuts their cleanup time.
It can be, if the provider has a current SOC 2 Type II report, enforces multi-factor authentication and named access, and signs a contract covering data handling and breach notification. For tax return information, Section 7216 consent must be in place before data leaves the US.
For books that are current, setup and the first close usually take a few weeks. If the books are months behind, add time for catch-up work before the regular monthly schedule begins.
Most work in mainstream cloud platforms such as QuickBooks Online, Xero and NetSuite, plus payroll and bill-pay tools. Confirm experience with any industry-specific system before signing.
Madras Accountancy provides outsourced accounting services to US businesses and CPA firms, from monthly bookkeeping and close to tax preparation support and controller work. Talk to our team about your current setup, and we will propose a scope and onboarding plan.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



