

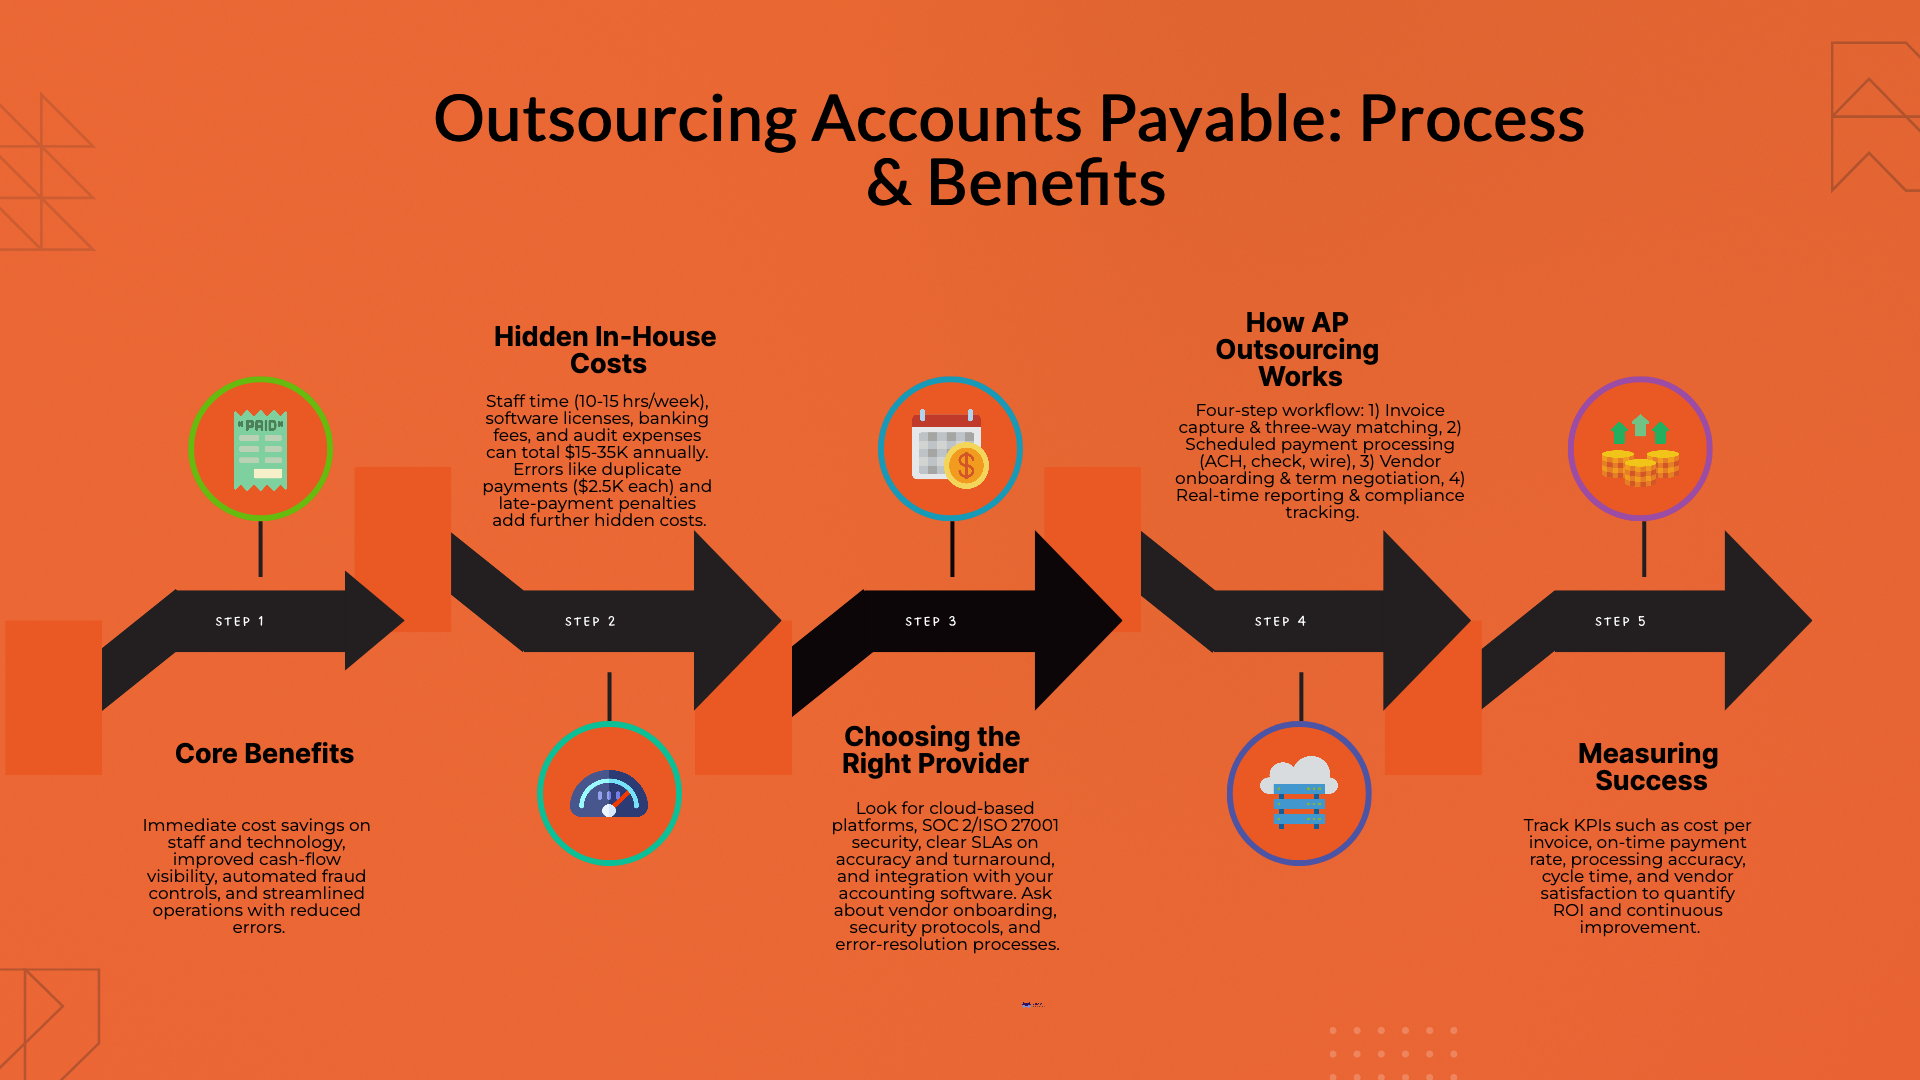

Outsourcing accounts payable means handing the routine work of paying suppliers (invoice capture, matching, approval routing, payment preparation, vendor records and year-end 1099 work) to an outside team, while your company keeps the authority to approve spending and release cash. Done well, it lowers the cost per invoice and adds a second set of eyes to a process that fraudsters target more than almost any other.
This guide explains what outsourcing accounts payable covers in practice, which controls must stay with you, what the 2026 payment fraud data shows, how to model the cost, which service levels to write into the contract, and the situations where keeping AP in house is the better call.
Most AP engagements cover the full purchase-to-pay cycle after a purchase is made. The scope below is typical; agree each line in writing before go-live.
Invoice capture. Suppliers email invoices to a dedicated inbox or upload them to a portal. The provider extracts vendor, invoice number, date, amount, tax and line detail, then codes the invoice to the general ledger and cost center. Paper invoices are scanned on receipt.
Three-way match. For purchase-order spending, the team compares the invoice to the purchase order and the receiving record. Quantity and price variances outside your tolerance (for example 2% or $100, whichever is lower) go to an exception queue for a buyer or manager to resolve. Non-PO invoices such as utilities and rent follow a two-way check against contract or prior history.
Approval routing. Coded invoices move through your approval matrix by amount, department and expense type. The provider chases late approvers; it does not approve spend on your behalf.
Payment runs. On an agreed calendar (weekly is common), the provider prepares a payment proposal that lists due invoices, available early-payment discounts and any holds. A named person at your company reviews it and releases the batch in your bank portal.
Vendor master maintenance. New vendor setup, W-9 collection, TIN validation, bank detail changes and deactivation of dormant vendors. This file is where most payment fraud starts, so it gets its own controls below.
1099 collection and filing. The team tracks reportable payments through the year and prepares Forms 1099-NEC and 1099-MISC in January. The One Big Beautiful Bill Act raised the main section 6041 reporting threshold from $600 to $2,000 "for payments made after December 31, 2025," according to IRS guidance in Internal Revenue Bulletin 2026-19. The current IRS instructions for Forms 1099-MISC and 1099-NEC tell payers to report nonemployee compensation "of $2,000 or more." The same law tied the backup withholding threshold for these payments to the new $2,000 amount, and payees who fail to furnish a TIN can be subject to backup withholding at a 24% rate under IRS Publication 1099. Our explainer on the 2026 1099 reporting threshold covers the form-by-form detail, and the 1099 outsourcing workflow walks through the January filing process step by step.
Many teams also hand over vendor statement reconciliation, supplier help-desk queries and the AP subledger tie-out at month end. If you want the close piece covered, align the AP calendar with your 5-day AP, AR and reconciliation close checklist.
| AP activity | Usually outsourced | Usually kept in house |
|---|---|---|
| Invoice receipt, data capture and GL coding | Yes | Coding rules and chart of accounts ownership |
| Three-way and two-way matching | Yes | Resolving price disputes with suppliers |
| Approval routing and reminders | Yes | Approving the spend |
| Payment proposal preparation | Yes | Releasing payments in the bank |
| Vendor setup and W-9 collection | Yes | Final approval of new vendors and bank changes |
| 1099 tracking, preparation and e-filing | Yes | Signing off the final 1099 list |
| Vendor statement reconciliation | Yes | Escalations involving contracts |
| Cash timing decisions | No | Treasury and payment priority |
The GAO's Standards for Internal Control in the Federal Government (the 2025 Green Book) states that "segregation of duties helps prevent fraud, waste, and abuse in the entity by considering the need to separate authority, custody, and accounting in the organizational structure." The same standard lists "oversight of entity business processes assigned to service organizations" as a control activity in its own right. Private companies are not bound by the Green Book, yet its logic maps neatly onto an outsourced AP setup.
In practice, the split looks like this:
Add detective controls on top: a monthly report of every vendor master change, a duplicate-invoice report (same vendor, same amount, similar invoice number), positive pay on checks and ACH debit blocks where your bank offers them. Smaller companies with one finance person can compensate with a second reviewer at the provider and random sampling by the owner. The SOX-lite internal controls guide for scale-ups shows how to document these steps, and internal controls testing for small businesses explains how to check they work.
Ask any provider for its independent controls report. Because AP affects your financial statements, a SOC 1 Type 2 report is usually the more relevant one for your auditor; our comparison of SOC 1 vs SOC 2 audits explains the difference.
The numbers explain why controls come first. The FBI's 2025 Internet Crime Report recorded $3,046,598,558 in reported business email compromise (BEC) losses for 2025, the second-largest loss category after investment fraud. BEC typically arrives as a convincing email from a real or spoofed supplier asking you to update bank details before the next payment.
The Association for Financial Professionals' 2026 Payments Fraud and Control Survey, based on 465 treasury practitioners and released on April 14, 2026, found that 76% of U.S. organizations experienced attempted or actual payments fraud in 2025 and 74% were affected by BEC. Paper checks were the most targeted payment method, cited by 58% of respondents, followed by ACH debits (30%) and wire transfers (25%).
ACH rules have tightened as well. Under Nacha's fraud monitoring rule, Phase 2, which took effect on June 19, 2026 (in practice Monday, June 22, because June 19 is a federal holiday), all remaining non-consumer originators, regardless of origination volume, must keep risk-based processes "reasonably intended to identify Entries that are suspected of being unauthorized or authorized under False Pretenses," and review them at least annually. Nacha lists BEC and vendor impersonation as examples of False Pretenses. If your outsourced team prepares ACH files, your written procedures should show how those payments are screened.
The controls that stop most of these losses are simple and should be written into the provider's procedures:
Our fraud prevention guide covers internal fraud and embezzlement patterns that apply to AP as well.
Providers usually price AP in one of three ways: a fee per invoice processed, a monthly fixed fee tied to a volume band, or a dedicated full-time resource billed monthly. Payment fees, software licenses and 1099 filing may be billed separately, so compare total annual cost rather than the headline rate.
The example below is illustrative. The salary, rates and fees are assumptions chosen to show the method, so replace them with your own payroll data and real quotes.
Illustrative company: 600 invoices a month (7,200 a year), one full-time AP specialist, a controller who reviews AP for 4 hours a week, and about 150 paper checks a month.
| Cost line (annual) | In house | Outsourced, year 1 | Outsourced, year 2 |
|---|---|---|---|
| AP specialist salary ($55,000) plus 25% benefits and payroll taxes | $68,750 | $0 | $0 |
| Provider fee at $4.50 per invoice x 7,200 | $0 | $32,400 | $32,400 |
| Provider monthly base fee ($750 x 12) | $0 | $9,000 | $9,000 |
| Controller review time at $85 per hour (4 hrs/week in house, 2 hrs/week outsourced, 50 weeks) | $17,000 | $8,500 | $8,500 |
| AP software and approval portal | $7,200 | $3,600 | $3,600 |
| Check printing and postage at $3.00 per check (150/month in house, 40/month after ACH migration) | $5,400 | $1,440 | $1,440 |
| One-time transition and vendor data cleanup | $0 | $6,000 | $0 |
| Total | $98,350 | $60,940 | $54,940 |
| Cost per invoice | $13.66 | $8.46 | $7.63 |
In this illustration, year 1 saves $37,410 (about 38% of the in-house cost) and year 2 saves $43,410 (about 44%). The saving depends entirely on the AP specialist role being eliminated or moved to other work that would otherwise require a hire. If the person stays in the same seat, the outsourced fees become an added cost. Run the same comparison against an automation-only option too; our page on automated accounts payable solutions covers ROI and implementation for software-led AP, and many companies end up combining the two.
Payment timing has its own value. A weekly payment proposal that shows due dates and discount windows feeds directly into cash flow forecasting, which helps you decide which bills to pay early and which to hold to terms.
Service levels turn a vague promise into something you can measure each month. The targets below are practitioner guidance for a mid-volume engagement, offered as a starting point for negotiation. Your own targets should reflect invoice complexity and approval speed inside your company, since the provider cannot control how fast your managers approve.
| Metric | Example target to negotiate | How to measure |
|---|---|---|
| Invoice capture and coding | Within 1 business day of receipt | Timestamp from inbox to ledger entry |
| Data entry accuracy | 99% or better on sampled invoices | Monthly sample checked by your team |
| Exception routing | Within 1 business day of identification | Exception log with dates |
| Payment proposal delivery | On the agreed weekday, every run | Calendar adherence report |
| Vendor query response | Within 2 business days | Ticket log |
| Bank change verification | 100% call-back before activation | Change log with call-back evidence |
| Month-end AP cutoff and subledger tie-out | By business day 3 | Close checklist sign-off |
| 1099 filing | Furnished and filed by the IRS deadline | Filing confirmations |
Write in the reporting format, the escalation path, service credits for repeated misses, data ownership and exit assistance. Our outsourcing contract template lists the clauses to include, and our ranking of the best outsourced accounts payable services for mid-size companies covers how to compare providers.
On 1099 deadlines, note that Form 1099-NEC has no automatic filing extension, according to IRS Publication 1099. When a deadline falls on a weekend or legal holiday, filing on the next business day counts as timely.
Outsourcing accounts payable suits companies with steady volume and settled processes. It is a weaker fit in these situations:
Very low invoice volume. If you process a few dozen invoices a month, a part-time bookkeeper or the controller can usually handle AP in a few hours, and provider minimum fees may exceed the internal cost.
No purchasing discipline yet. Without purchase orders, a written approval matrix or consistent coding rules, an outside team will spend most of its time asking questions. Fix the process first, then hand it over.
AP decisions need deep operational judgment. Construction subcontractor payments with lien waivers and retainage, or job-costed project invoices that only a site manager can validate, often work better with an in-house specialist supported by outside help for data entry.
A system migration is underway. Moving to a new ERP and a new AP provider at the same time doubles the risk of duplicate or missed payments. Stabilize one change before starting the other.
Contract or regulatory limits on data. Some government contracts and regulated industries restrict where vendor or payment data can be processed or who may access it. Check these limits before sharing data with any third party.
You cannot spare an owner for the relationship. Outsourcing moves the work, while the responsibility stays with you. Someone at your company still has to approve payments, review exception reports and meet the provider monthly. Our guide on which accounting tasks to outsource and which to keep in house offers a broader framework for this decision.
What is outsourcing accounts payable? It is the practice of hiring an outside team to process supplier invoices, match them to purchase orders, route approvals, prepare payment runs, maintain vendor records and handle 1099 reporting. Your company keeps spending approval and bank release authority.
Does an outsourced AP team have access to my bank account? It should only have permission to prepare payments. Release authority should sit with your own staff, ideally with dual approval in the bank portal.
How does the 2026 1099 threshold change outsourced AP work? For payments made after December 31, 2025, the main Form 1099-NEC and 1099-MISC reporting threshold is $2,000 instead of $600, with inflation adjustments starting in 2027. Your provider should still collect a W-9 from every vendor at setup, since payment totals are hard to predict in advance.
How long does an AP outsourcing transition take? Many transitions run four to eight weeks, covering vendor data cleanup, approval matrix setup, parallel runs and a first live payment cycle. Treat this as guidance; complex multi-entity setups can take longer.
Which provider report should my auditor ask for? For processes that affect your financial statements, auditors usually look for a SOC 1 Type 2 report. A SOC 2 report addresses security and data handling and is often requested as well.
Madras Accountancy supports US businesses with bookkeeping, accounts payable processing, 1099 preparation, month-end close, tax preparation and CFO advisory. If you are weighing whether to outsource AP, or want a second look at your current payment controls, contact our team to talk through scope.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



