


Paperless accounting means your source documents, workpapers, approvals and client files live in digital systems you can search and produce for the IRS, instead of in cabinets. For most CPA firms and finance teams the technology is the easy part. The hard parts are deciding what counts as the official record, setting retention rules, and getting staff and clients to stop printing.
The IRS accepts scanned records. Rev. Proc. 97-22 says records kept in an electronic storage system that meets its requirements count as books and records under Section 6001. The main conditions:
Section 7 of the revenue procedure lets you destroy the original paper once you've tested the system and confirmed it reproduces records correctly, and once you've put procedures in place to keep it compliant. Do that testing on paper, sign it off and keep the memo. It's the first thing an examiner will ask for if a scanned receipt is challenged.
Going paperless doesn't shorten any retention period. The IRS guidance on how long to keep records sets these minimums:
| Situation | Keep records for |
|---|---|
| Most income tax returns | 3 years from filing |
| You file a refund claim after the original return | 3 years from filing or 2 years from paying the tax, whichever is later |
| Unreported income over 25% of gross income shown | 6 years |
| Loss from worthless securities or bad debt deduction | 7 years |
| Employment tax records | At least 4 years after the tax is due or paid, whichever is later |
| No return filed, or a fraudulent return | Indefinitely |
| Property records | Until the limitations period ends for the year you dispose of the property |
Your DMS should apply these as retention labels so files can't be deleted early. State tax agencies, lenders and insurers may want longer periods, so set your firm's policy to the longest rule that applies.
Walk through a month of work and list every document that arrives or leaves on paper: client organizers, bank statements, vendor bills, receipts, signed engagement letters, payroll records and audit confirmations. Note who touches each one and where it's filed. Most firms find that a few sources (mailed bank statements, client shoeboxes, wet-ink signatures) make up most of the volume, so start there.
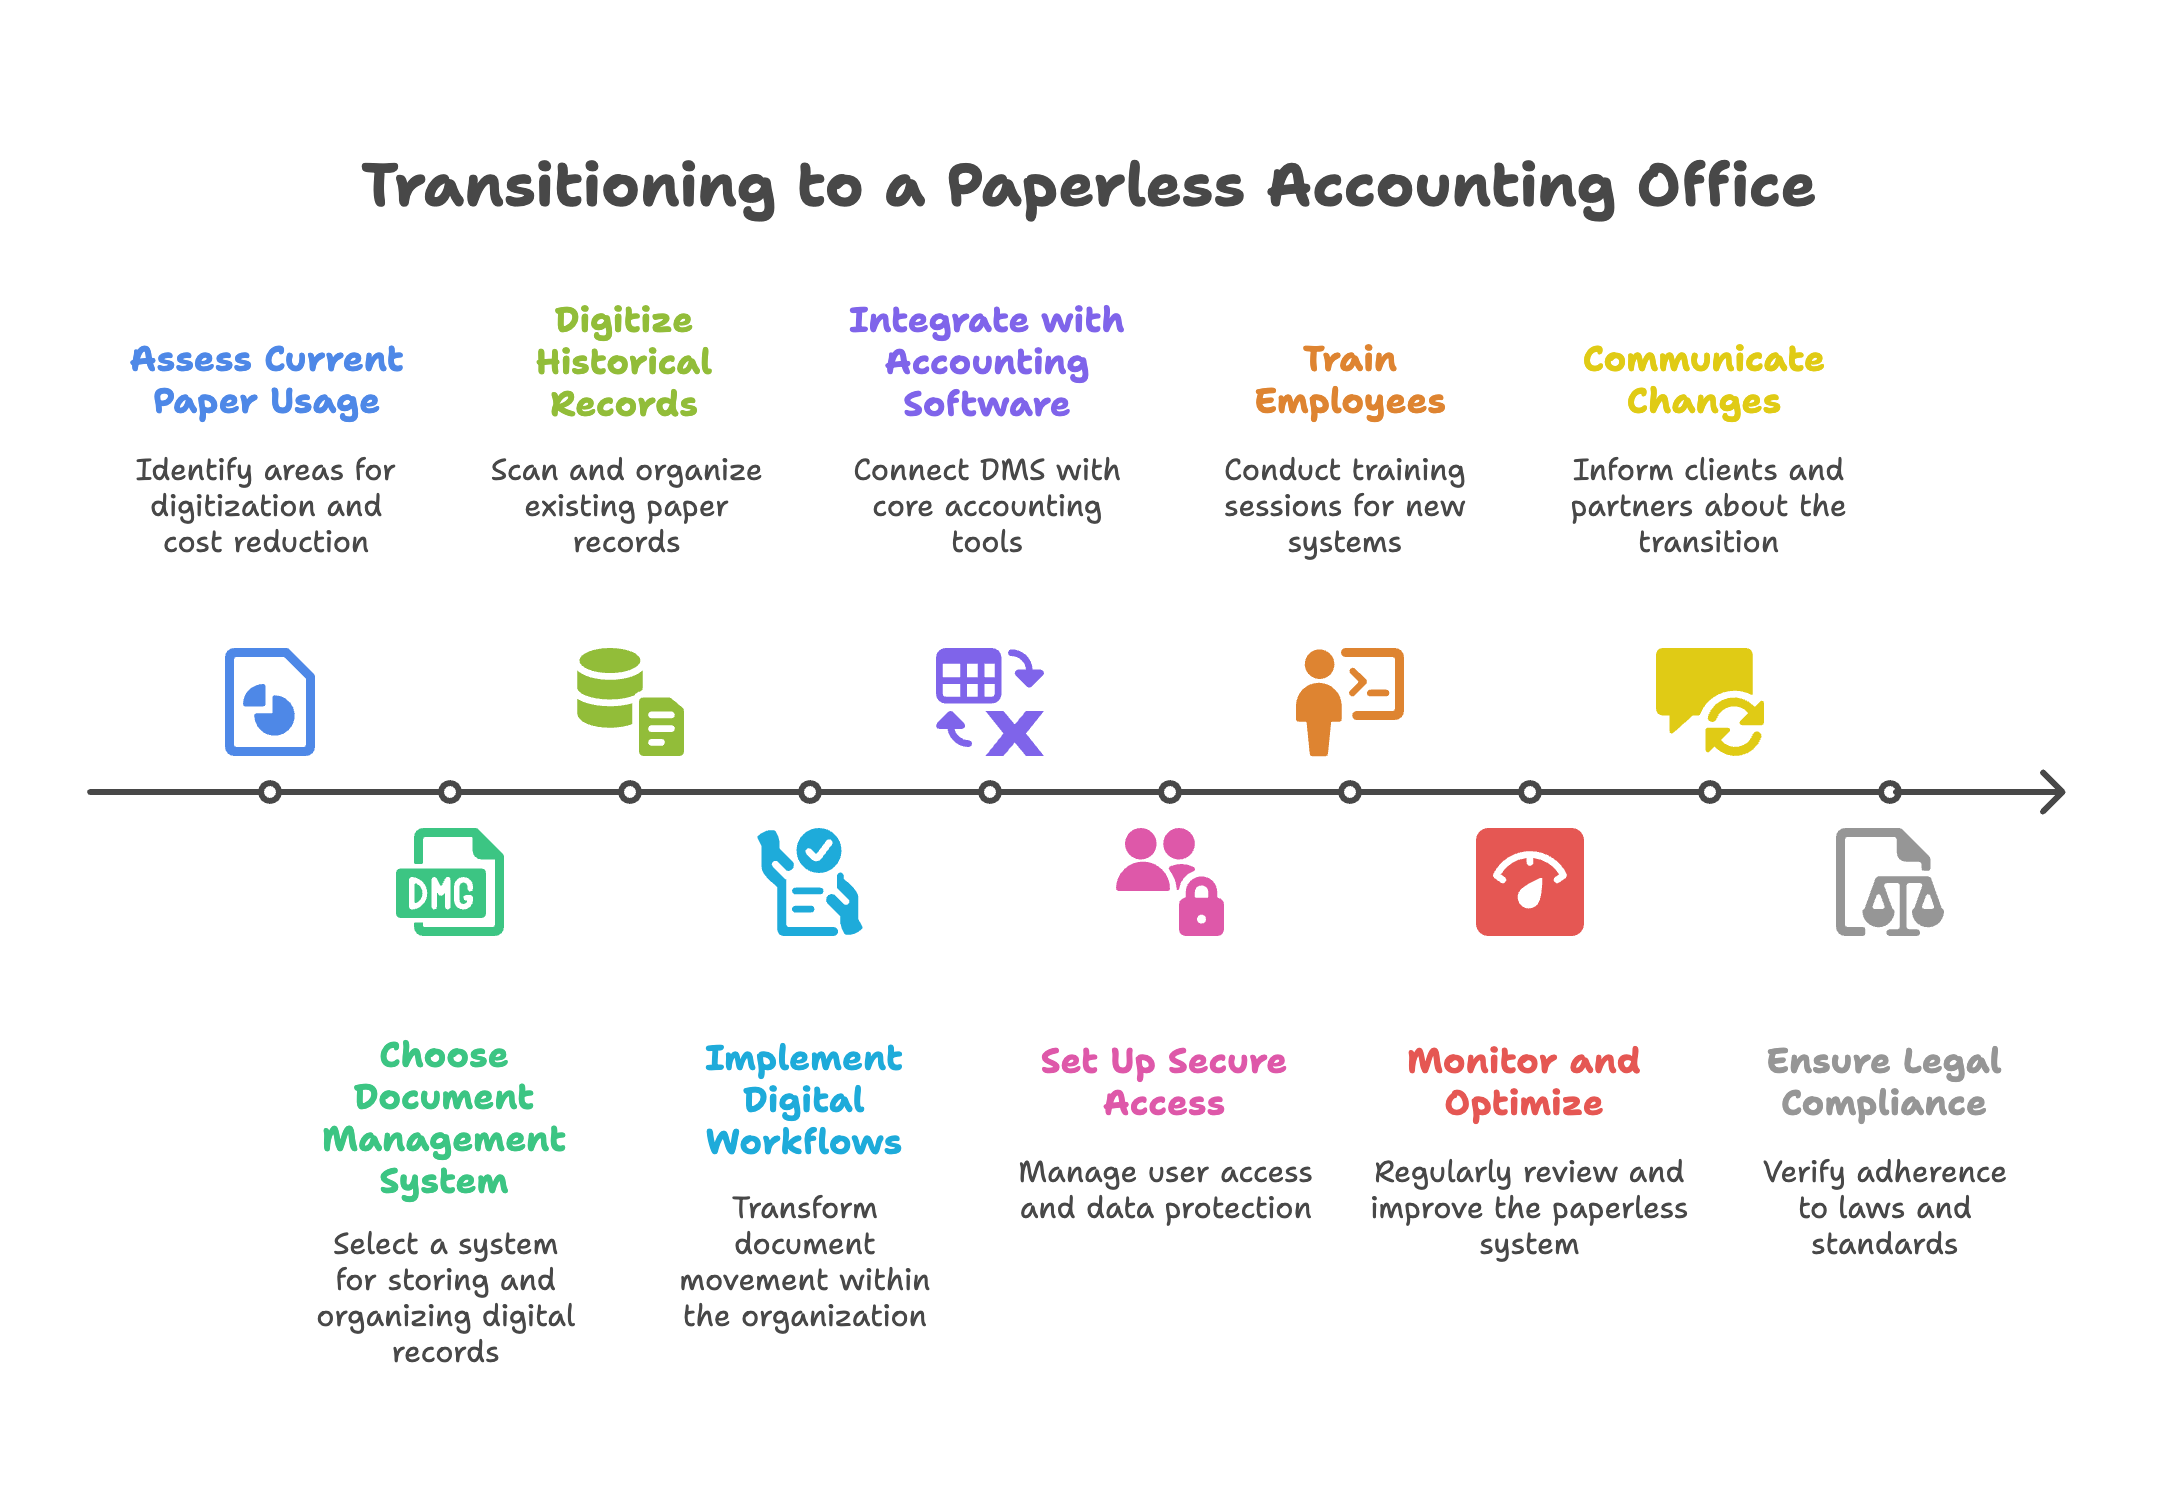
Your DMS holds the official record, so judge it on the Rev. Proc. 97-22 points above as much as on features. Look for:
Many firms use the document module inside their practice management suite; others use SharePoint and OneDrive or a dedicated product such as SmartVault. Our guide to cloud practice management software compares how those suites handle documents.
A scanned file with a name like "Scan_0045.pdf" is useless at an exam. Pick one convention and enforce it, for example ClientID_TaxYear_DocType_Date. Decide which metadata fields are mandatory and lock the folder structure so staff can't invent their own. This is also what makes the data usable later: our AI-ready accounting data checklist explains why consistent document tags matter for automation.
Scan active clients and open tax years first. Closed years past their retention period may not need scanning at all; check your policy and destroy them instead. For bulk work, use duplex scanners at 300 dpi or higher and run a quality check on a sample of every batch before you shred anything. If you don't have the staff time, outsource the backlog, but keep the testing and sign-off in-house.
Paper usually survives because of signatures. Replace wet-ink approvals with:
Every approval should leave a time-stamped record of who approved what.
IRS Publication 1345 lets EROs electronically image and store the paper records they must keep for e-file, including Forms 8879 and 8878, as long as the storage system meets Rev. Proc. 97-22 and reproduces taxpayer signatures legibly. Those forms must be available to the IRS for three years from the return due date or the IRS received date, whichever is later, and each one has to be tied to its Submission ID, either written on the form or through the saved acknowledgment.
When a client e-signs, the software must record a digital image of the signed form, the date and time, the method used to sign, and the identity verification result. Remote signings also need the taxpayer's IP address and username. Make sure your e-signature vendor stores that audit data where you can export it, and give 8879s their own retention label in the DMS.
Double entry is the most common reason paperless projects stall. Bills scanned into the DMS should flow into QuickBooks Online, Xero or your ERP with the image attached to the transaction. Tax documents should link to the return in your tax software. Where there's no native connector, an API or middleware tool can fill the gap; see API integration for accounting workflows. If a client still runs their books in spreadsheets, that's the time to move them, as explained in Excel vs accounting software.
Once client data is digital, the FTC Safeguards Rule applies directly to tax preparation firms. It requires you to:
The IRS publishes a template, Publication 5708, and reminds tax professionals that a written information security plan is a legal requirement. Note how the two-year disposal rule interacts with the IRS retention table: you keep records as long as the tax rules require, then dispose of them on schedule. For remote teams, our cloud accounting security best practices cover device and access controls.
People revert to paper when they're busy. Run short, hands-on training on the DMS, the naming convention and the portal, then make the digital path the only path: remove personal printers, stop accepting paper workpapers in review, and have managers reject files that aren't indexed. A one-page cheat sheet per role works better than a long manual. Firms that are already remote-first have an advantage here; see our remote-first CPA firm operations guide.
Tell clients when the change happens, how to upload, and who to call. Build portal setup into your client onboarding checklist so new clients never start on paper. Keep a small paper intake process for clients who can't use the portal: scan on arrival, index the same day, and return or destroy the originals under your policy.
Check a sample of files against your naming rules, review the access log for unusual downloads, confirm retention labels are being applied, and test that you can retrieve and print a record from three years ago. Record the results. That quarterly memo doubles as evidence of the "reasonable controls" and periodic checks Rev. Proc. 97-22 asks for.
Here's how the steps fit together for a single individual client. In February the client uploads W-2s, 1099s and a brokerage statement to the portal. The DMS renames each file to the firm convention (for example C1042_2025_1099B_2026-02-14), tags it by document type and applies the three-year retention label. A property closing statement arrives by mail, so the front desk scans it that day, a second person checks the scan against the original, and the paper goes back to the client.
The preparer works from the indexed files, and the return links to the client folder in the tax software. The client e-signs Form 8879 with identity verification, the firm attaches the Submission ID from the acknowledgment, and the signed form gets its own label. If an offshore reviewer touches the return, the DMS only opens that folder after the 7216 consent is on file. At the quarterly review, the manager pulls this client's file at random and confirms every document can be found and printed.
Digital files make it easy to share work with an offshore team, but tax return information carries an extra rule. Under Treasury Regulation 301.7216-3, a US preparer needs the taxpayer's consent before disclosing return information to a preparer outside the United States. For Form 1040 filers, the SSN must be masked unless it's sent with an adequate data protection safeguard and the consent says so. Build the consent into your engagement letter and set DMS permissions so offshore staff see only the clients who've signed. Our articles on data security compliance for offshore work and the tax software handoff checklist for offshore teams go further.
At Madras Accountancy we support US CPA firms during the switch with backlog scanning and indexing, DMS setup, workflow mapping, and day-to-day document handling under signed 7216 consents.
What is paperless accounting? It's running your bookkeeping, tax and audit work with digital source documents, electronic approvals and a document management system as the official record. Paper that arrives is scanned, indexed and then destroyed under a written policy. The goal is records you can search and produce quickly, with access controls a filing cabinet can't offer.
Is a scanned receipt as good as the original for the IRS? Yes, if your system meets Rev. Proc. 97-22. That means accurate, legible reproductions, an indexing system, reasonable controls and the ability to retrieve and print records at an exam. Test the system before you destroy originals.
How long should a paperless office keep client files? Use the IRS periods as a floor: three years for most returns, six years if income was underreported by more than 25%, seven years for bad debt or worthless securities claims, and at least four years for employment tax records. Then check state and contractual requirements and apply the longest.
Do small accounting firms need a written information security plan? Yes. The FTC Safeguards Rule covers tax preparation firms regardless of size, and the IRS says a written plan is a legal requirement. IRS Publication 5708 is a free template sized for small practices.
What software do I need for paperless accounting? At minimum: a document management system or practice management suite with document storage, a client portal, an e-signature tool that meets IRS identity rules for Forms 8879 and 8878, and cloud accounting software that stores document images with transactions. A good scanner covers the remaining paper.
Pick one document stream, usually vendor bills or client tax documents, and run it fully digital for one month before expanding. If you'd like help scanning a backlog or setting up the workflow, contact our team.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



