

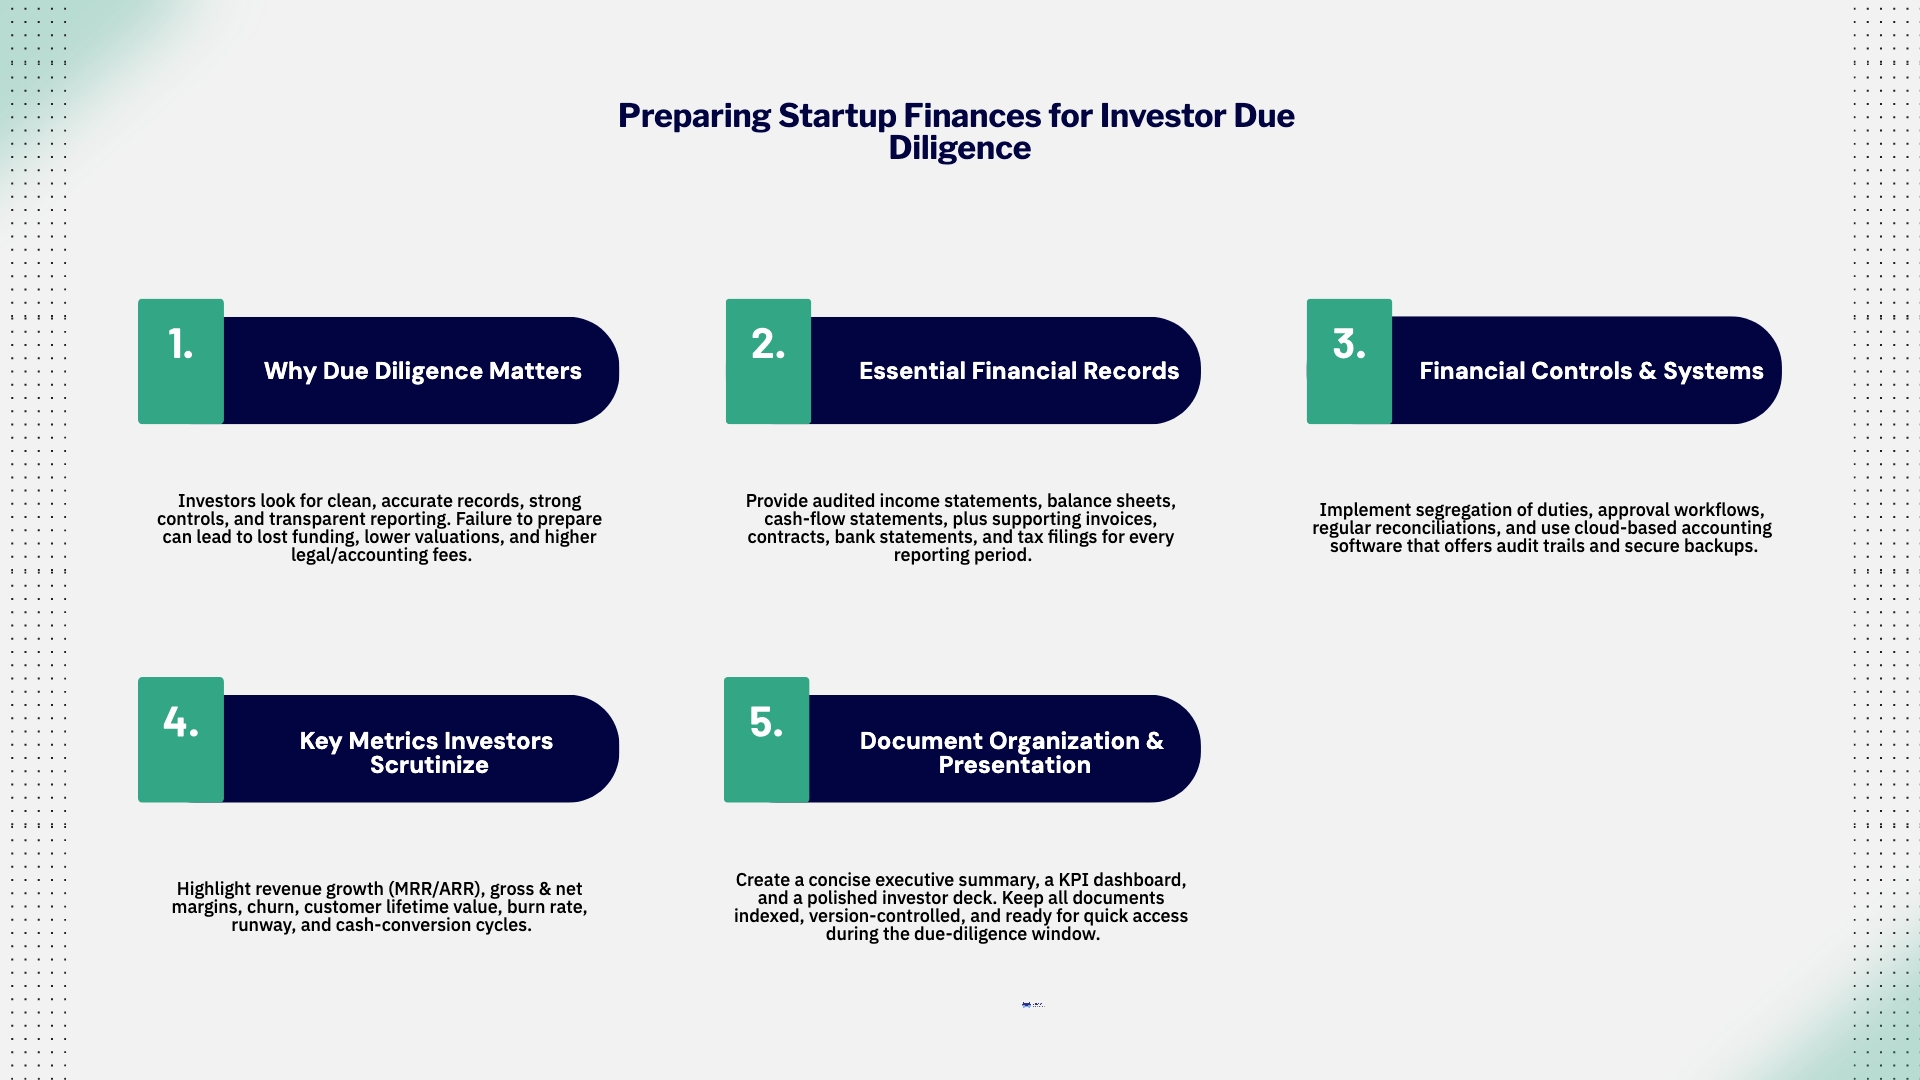

A financial due diligence checklist for startups is the list of records an investor's team will ask to see before a priced round closes: monthly GAAP financial statements, a reconciled cap table, a current 409A valuation, revenue contracts tied to your revenue schedule, tax filings and state compliance records. When those files are complete and consistent before the term sheet arrives, diligence takes weeks instead of months and fewer issues reach the negotiation over terms.
This guide walks through the financial due diligence checklist for startups in the order most investor teams work through it, with the October 2026 tax rules that affect it, including the One Big Beautiful Bill Act (OBBBA) changes to the qualified small business stock exclusion. It is written for founders preparing a data room and for the CPA firms that support them.
Investor diligence at the seed stage leans on the team and the market, because there is little financial history to test. From Series A onward, the review gets specific. An investor's finance team or outside accountants will try to rebuild your reported numbers from source records.
The review areas are consistent across rounds:
Later-stage buyers run a deeper version of the same exercise. The M&A due diligence checklist covers that acquisition-level review, including quality of earnings work.
A data room is a shared, permissioned folder for the investor's team, best built before you start pitching. The table below lists the financial items most investors request and the issue each one usually exposes.
| Data room folder | Documents to include | What reviewers look for |
|---|---|---|
| Financial statements | Monthly income statement, balance sheet and cash flow statement for the last 24 months (or since inception); annual statements; any reviewed or audited statements | GAAP basis, consistent monthly close, reconciled cash |
| Revenue | Customer contracts, order forms, revenue schedule, deferred revenue rollforward, ARR or MRR bridge | Revenue recognized per ASC 606, deck metrics tied to the ledger |
| Cap table and equity | Fully diluted cap table, stock ledger, option plan, board consents, 409A reports, SAFEs and convertible notes, 83(b) elections | Clean ownership, grants priced at fair market value |
| Tax | Federal and state income tax returns, payroll filings, sales tax registrations and returns, R&D credit studies | Unfiled returns, nexus exposure, payroll liabilities |
| State compliance | Delaware annual franchise tax reports and receipts, foreign qualification filings in each operating state | Good standing, unpaid franchise tax |
| Banking and debt | Bank and card statements, loan agreements, venture debt covenants | Undisclosed obligations, covenant breaches |
| Forecast | Three-statement model, budget versus actual, hiring plan, runway calculation | Assumptions consistent with history |
| Controls | Close checklist, approval workflow, list of system users and admin rights | Segregation of duties, audit trail |
If you are still setting up the basics, the startup accounting checklist for first-time founders covers the systems that feed these folders.
Many early startups keep cash-basis books because the bookkeeping is simpler and taxes are filed that way. Investors usually expect accrual statements prepared under US GAAP, because cash-basis books hide deferred revenue, accrued expenses and prepaid contracts.
Tax method and book method are separate decisions. For federal tax, IRS Publication 538 states that "the following entities generally cannot use the cash method", and the list includes "a corporation (other than an S corporation)", subject to an exception for corporations that meet the gross receipts test (IRS Publication 538). A venture-backed C corporation that qualifies for that exception can still file on the cash method while keeping accrual GAAP books for investors and the board. The difference becomes a reconciling item between book and taxable income.
Before diligence, convert to accrual if you have not already, and restate at least the last 12 to 24 months. Book the entries that most often go missing: deferred revenue, accrued payroll and bonuses, accrued vendor bills, prepaid software and insurance, and depreciation on capitalized equipment.
Some lead investors require reviewed or audited statements as a condition of the round or after closing. Founders weighing that cost can read how much audited financial statements cost for startups before the term sheet sets a deadline.
The cap table is often where diligence finds its most expensive problems. Reviewers compare the cap table against the stock ledger, board consents, signed grant agreements and every SAFE or convertible note. They want the fully diluted share count to match each document, and they want to see that option grants were priced correctly.
Under Section 409A, a stock option escapes treatment as deferred compensation only if the exercise price is set at fair market value. The regulation describes a nonstatutory option that qualifies as one where "the exercise price may never be less than the fair market value of the underlying stock" on the grant date (26 CFR 1.409A-1, Cornell LII). An option priced below fair market value can trigger additional tax and penalties for the employee, which becomes a liability the investor will price in.
The regulation also gives private companies a safe harbor. A value is presumed reasonable if it is "determined by an independent appraisal" that meets the regulation's requirements, "as of a date that is no more than 12 months before the relevant transaction to which the valuation is applied" (26 CFR 1.409A-1). In practice, startups refresh the 409A at least every 12 months and after any material event, such as a priced round. Put every report in the data room and confirm each grant date falls inside a valid report's window.
Investors also ask whether founders and early employees who received restricted stock filed 83(b) elections within the deadline. A missing election can create ordinary income as shares vest. The background is in our guide to the 83(b) election for startup founders.
Revenue is the number investors test hardest. ASC 606 sets the core principle that an entity shall "recognize revenue to depict the transfer of promised goods or services to customers in an amount that reflects the consideration to which the entity expects to be entitled in exchange for those goods or services" (ASC 606-10-10-2, reproduced in Deloitte DART). The standard applies that principle in five steps: identify the contract, identify the performance obligations, determine the transaction price, allocate the price to those obligations, and recognize revenue as each obligation is satisfied.
For a startup, the practical diligence issues are usually these:
Prepare a revenue schedule by customer that ties to the general ledger each month, with a deferred revenue rollforward. Then bridge your ARR or MRR figure to recognized revenue so a reviewer can see why the two differ. Software companies can follow the step-by-step approach in SaaS revenue recognition under ASC 606, and the definitions behind common investor metrics are set out in SaaS financial metrics for finance teams.
Many investors ask whether the company's stock qualifies as qualified small business stock (QSBS), because the Section 1202 exclusion can remove most or all federal tax on a gain at exit. The OBBBA, signed on 4 July 2025, changed several of the rules from that date. The full rules are covered in our guide to QSBS in 2026. For diligence, these are the points that matter.
| Rule | On or before 4 July 2025 | After 4 July 2025 |
|---|---|---|
| Minimum holding period (by acquisition date) | More than 5 years | At least 3 years |
| Exclusion (by acquisition date) | 100% for stock acquired after 27 Sept 2010 (earlier stock: 50% or 75%) | 50% at 3 years, 75% at 4 years, 100% at 5 years or more |
| Per-issuer dollar cap (by acquisition date) | $10 million | $15 million, indexed for inflation for tax years beginning after 2026 |
| Gross assets limit (by issuance date) | $50 million for stock issued on or before 4 July 2025 | $75 million for stock issued after 4 July 2025, indexed for inflation for tax years beginning after 2026 |
The statute now reads that the exclusion applies to "the applicable percentage of any gain from the sale or exchange of qualified small business stock acquired after the applicable date and held for at least 3 years", and its table sets "3 years 50% 4 years 75% 5 years or more 100%" (26 U.S.C. 1202, Cornell LII). For a company to issue QSBS, it must be a C corporation whose aggregate gross assets immediately after the issuance "do not exceed $75,000,000" for stock issued after the OBBBA (26 U.S.C. 1202(d)).
Worked example. A founder acquired shares at original issue in September 2025 with a $500,000 basis and sells them four years later for a $20 million gain. The per-issuer cap is the greater of $15 million or 10 times basis ($5 million), so $15 million. At four years the applicable percentage is 75%, so $11.25 million of gain is excluded and $8.75 million remains taxable. Held to five years, the full $15 million would be excluded.
To support QSBS claims, keep in the data room a record of gross assets at each issuance date, proof that the company has been a C corporation since issuance, and documents showing an active qualified business.
Most venture-backed startups are Delaware C corporations, and unpaid franchise tax is a common diligence finding. The Delaware Division of Corporations states that "Taxes and Annual Reports are to be received no later than March 1st of each year" (Delaware Division of Corporations). The same page says "the penalty for not filing a completed Annual Report on or before March 1st is $200.00" and "interest at 1.5% per month is applied to any unpaid tax balance." A company that falls out of good standing can delay a closing, because most financing documents require a current good standing certificate.
Delaware calculates the tax two ways and lets the company "use the method that results in the lesser tax" (Delaware franchise tax calculation). Startups with millions of authorized shares at a tiny par value usually owe far less under the assumed par value capital method.
Worked example (as of October 2026 rates). A startup has 10,000,000 authorized shares at $0.0001 par, 8,000,000 issued shares, and $3,000,000 of total gross assets on its federal Form 1120, Schedule L. Under the authorized shares method the tax is $250 for the first 10,000 shares plus 999 blocks of 10,000 shares at $85 each, or $85,165. Under the assumed par value capital method, assumed par is $3,000,000 / 8,000,000 = $0.375, so assumed par value capital is 10,000,000 x $0.375 = $3,750,000, rounded up to $4,000,000 and taxed at $400 per million, or $1,600.
The company pays $1,600 in tax plus the annual report filing fee, which Delaware sets at $50 for non-exempt domestic corporations. To use the second method, Delaware requires figures "for all issued shares (including treasury shares) and total gross assets." Keep each year's filed report and payment confirmation in the data room. For filing mechanics and other entity types, see our guide to Delaware franchise tax requirements.
Beyond the franchise tax, reviewers check that federal returns are filed for every year since incorporation, including loss years, and that payroll filings match the payroll register. Sales tax is a growing issue for software companies that sell into many states, because each state with economic nexus may expect registration.
The OBBBA also changed the treatment of research costs. Domestic research and experimental expenditures can again be deducted for tax years beginning after 2024, which affects the tax provision and any amended returns a startup chooses to file. The details are in our article on Section 174 after the One Big Beautiful Bill Act.
The forecast should start from actual results, carry the same revenue definitions used in the books, and show monthly cash through the end of the runway. Reviewers often compare the prior year's budget with actual results, so retain each prior budget.
Investors also look at who runs finance. A founder doing the books at night is a common seed-stage arrangement, but by Series A most investors expect a consistent month-end close, documented approvals and someone accountable for reporting. Many startups bring in part-time finance leadership for the raise itself. Our article on fractional CFOs and fundraising explains how that support usually works.
How far back do investors review a startup's financials? Most investors ask for monthly statements for the last 24 months or since inception, plus the current year to date. Later-stage investors may also ask for prior annual statements that were reviewed or audited.
Do investors require audited financial statements before a seed or Series A round? Many seed and Series A investors accept unaudited GAAP statements prepared by a qualified accountant. Some lead investors require an audit after closing, and venture lenders often require one, so check the term sheet and any loan covenants.
How often should a startup update its 409A valuation? The independent appraisal safe harbor covers a valuation dated no more than 12 months before the grant. Most startups refresh the 409A at least once a year and after any priced round or other material event.
What QSBS records should a startup keep for investors? Keep a record of gross assets immediately after each stock issuance, proof of C corporation status since issuance, and evidence of an active qualified business. Under the OBBBA, the gross assets limit is $75 million for stock issued after 4 July 2025 and $50 million for earlier issuances.
Can unpaid Delaware franchise tax delay a funding round? Delaware charges a $200 penalty for a late annual report and 1.5% interest per month on unpaid tax. The company can lose good standing, which can hold up a financing until the tax is paid and the status restored.
Madras Accountancy supports US startups and the CPA firms that serve them with bookkeeping, accrual conversion, monthly close, revenue schedules, tax preparation and finance support during fundraising. To discuss getting your records ready for investor review, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



