


Project accounting for architecture firms means every hour, consultant invoice and reimbursable expense lands on a project and a phase, so the partners can see which jobs make money while there is still time to act. A firm-wide P&L tells you the year was thin. Project-level books tell you the clinic renovation burned 40% of its fee in schematic design and the school addition is carrying it.
Most small and mid-size studios already have the raw data in timesheets and invoices. The gap is structure: consistent codes, a monthly budget-versus-actual review, and a handful of ratios that everyone reads the same way.
General ledger accounting answers "how did the firm do?" Project accounting answers "how did this project, in this phase, do against what we priced?" Each transaction carries a project number and a phase or task code in addition to its GL account.
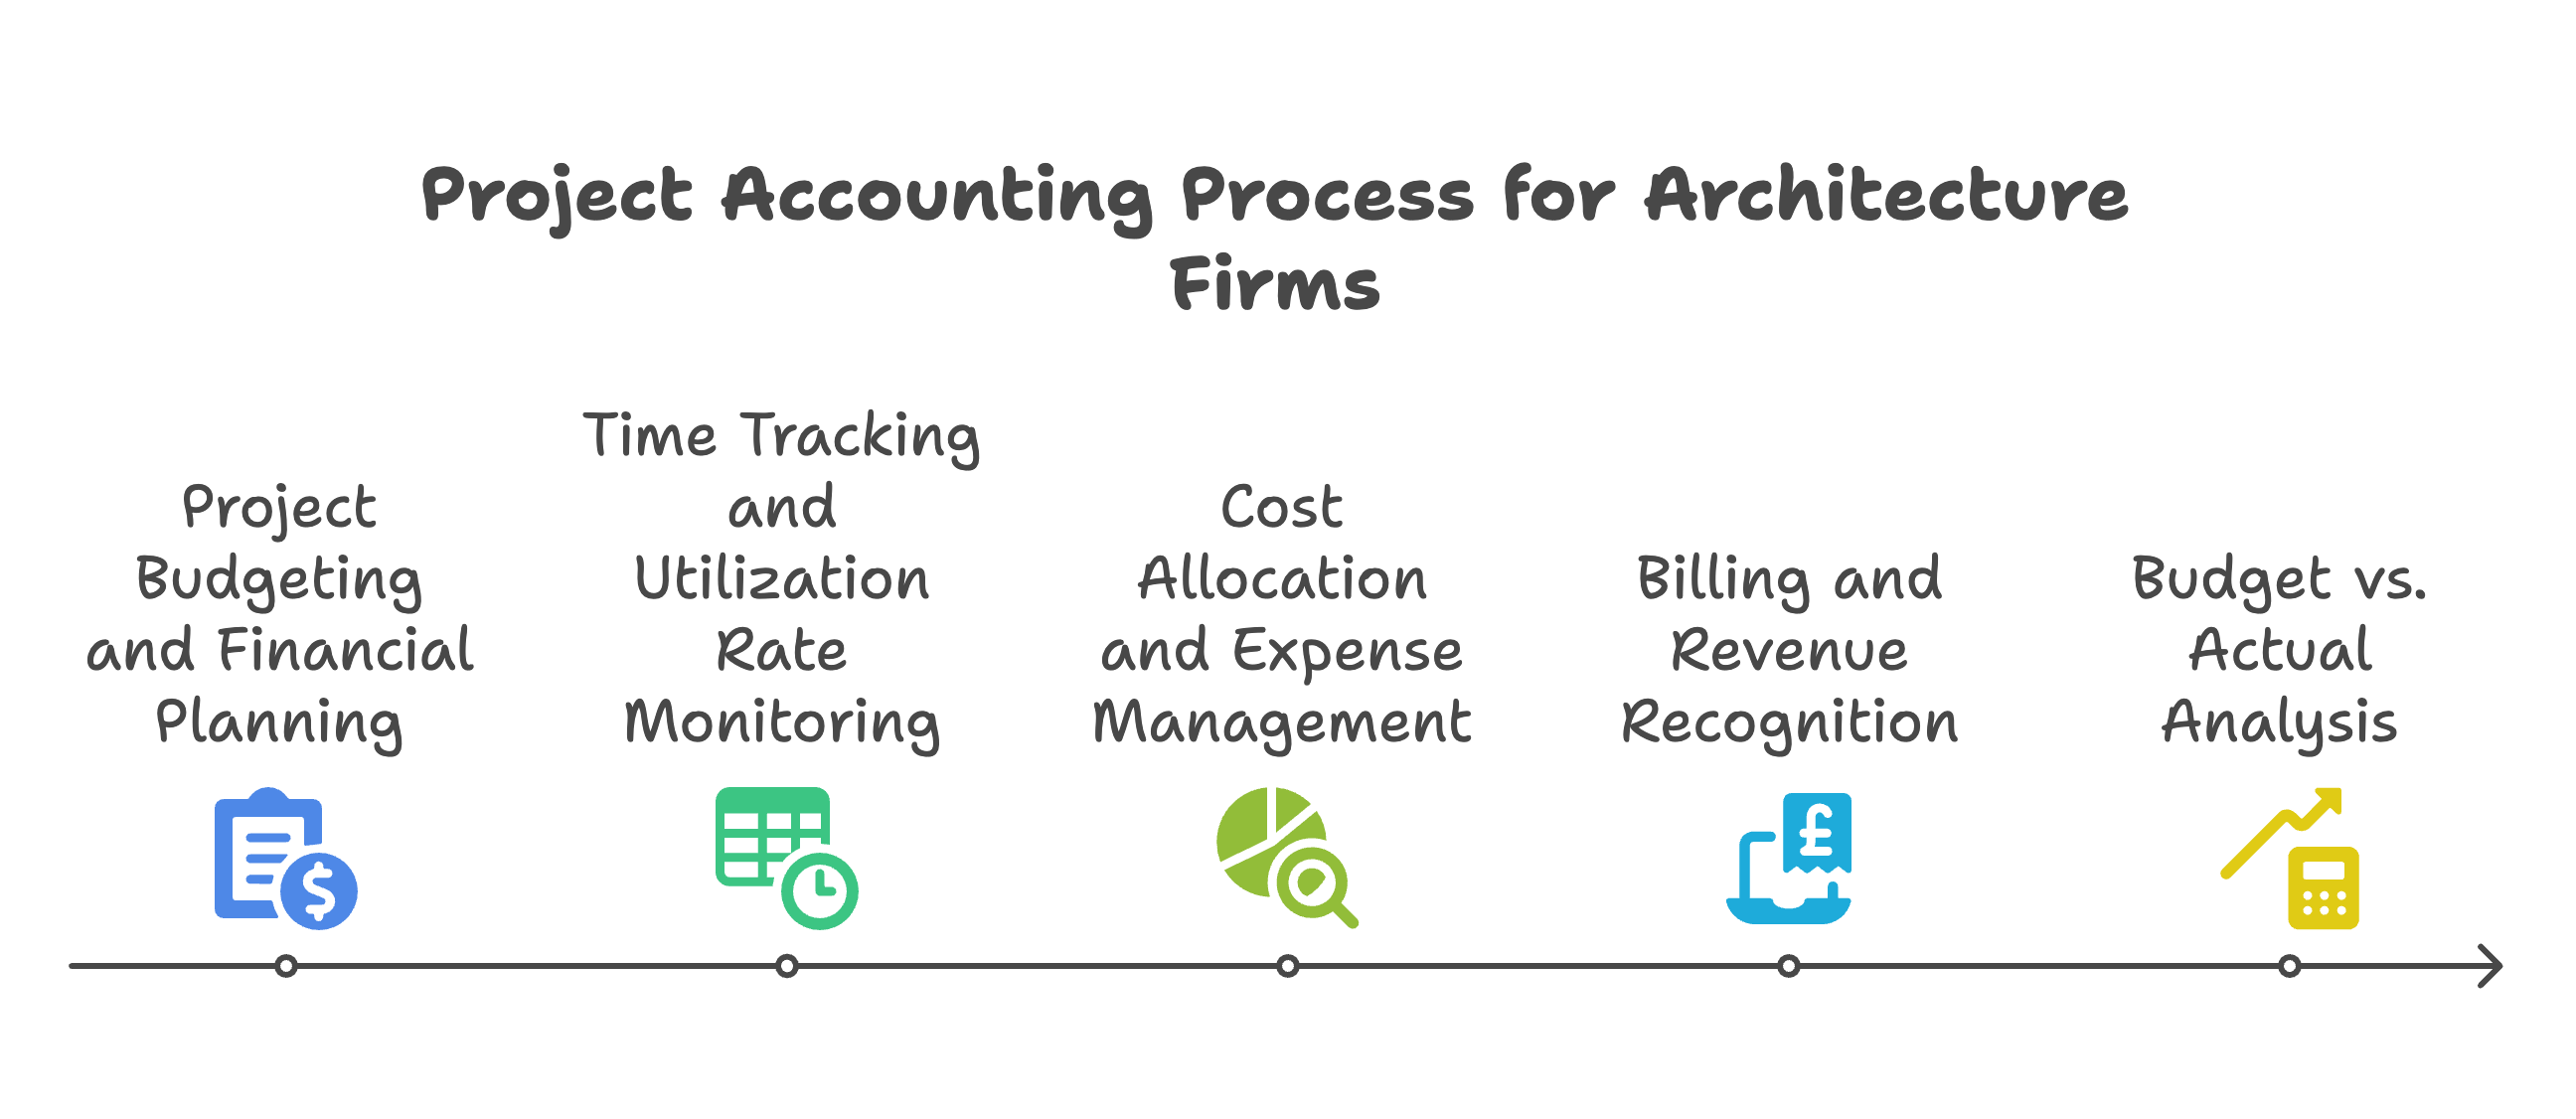
Most firms build phases around the owner-architect agreement. The AIA's B101-2017 owner-architect agreement splits basic services into five phases (schematic design, design development, construction documents, procurement and construction) and separates supplemental and additional services. Matching your phase codes to the contract makes billing, fee tracking and change management line up with what the client signed.
Keep the GL lean and push detail into project and phase dimensions. A well-built chart of accounts separates three kinds of cost that architecture firms often mix together:
A simple coding scheme looks like this:
| Element | Example | Purpose |
|---|---|---|
| Project number | 2026-014 | One per signed contract |
| Phase | 02-DD | Matches contract phase and fee split |
| Task (optional) | 02-DD-REN | Renderings, permits, coordination |
| Labor category | Project Architect | Rate and cost tracking |
| Billing type | Fixed fee / Hourly / Reimbursable | Drives invoicing and revenue recognition |
| Additional service flag | ASR-03 | Separates approved extra work |
Two rules prevent most cleanup work later. No timesheet line without a phase code, and no consultant invoice posted until it is tied to a project and marked billable or non-billable.
Architecture firms measure profit against net revenue, meaning fees earned minus consultant and reimbursable costs. Consultant fees flow through your books but are not your work, so leaving them in revenue makes margins look better than they are.
| Metric | Formula | What it tells you |
|---|---|---|
| Net revenue | Total fees earned minus consultants and reimbursables | The revenue your own staff produced |
| Utilization rate | Billable hours ÷ total paid hours | How much staff time reaches projects |
| Net multiplier | Net revenue ÷ direct labor cost | Revenue earned per $1 of project salary |
| Overhead rate | Total overhead (incl. indirect labor) ÷ direct labor cost | Overhead carried per $1 of project salary |
| Breakeven multiplier | 1 + overhead rate | Multiplier needed just to cover costs |
| Project profit | Net revenue minus (direct labor × breakeven multiplier) | Profit after a fair share of overhead |
A firm signs a $240,000 fixed fee for a medical office building, with $60,000 of that fee going to subconsultants. Net revenue is $180,000. The team budgets $60,000 of direct labor cost, so the planned net multiplier is 3.0.
The firm's overhead rate for the year is 160%, which makes the breakeven multiplier 2.6. At budget, project cost is $60,000 × 2.6 = $156,000, and profit is $24,000.
By the end of construction documents the team has spent $72,000 of direct labor on a job with no approved fee increase. The achieved multiplier falls to $180,000 ÷ $72,000 = 2.5, below breakeven. Fully loaded cost is $72,000 × 2.6 = $187,200, so the project loses $7,200. Twelve thousand dollars of extra salary cost turned a $24,000 profit into a loss because every labor dollar also carries $1.60 of overhead.
That multiplication effect is why the monthly review matters more than the year-end tax return. Firms that also run a CPA practice and want the partner-level view of their own accounting firm profitability should use the measures in these accounting firm KPIs for managing partners, which work differently from design-firm multipliers.
Spread the net fee across phases at signing, then convert each phase fee into a labor budget by dividing by your target multiplier. If design development carries $36,000 of net fee and the target multiplier is 3.0, the DD labor budget is $12,000 of salary cost.
Each month, compare three numbers for each open phase:
When spent runs ahead of complete (say 70% spent, 50% complete), the phase is heading over budget, and the project manager should either recover hours, document the scope that drove the overrun, or request an additional service. Waiting until the phase closes removes all three options.
For a reporting format partners will actually read, our post on KPI reporting for professional services firms shows how to lay out a one-page monthly pack.
Architecture contracts usually fall into four billing types:
For GAAP financial statements, design services are generally recognized over time under ASC 606 because the client controls the work as it is produced and the firm usually has an enforceable right to payment for work to date. Most firms measure progress with an input method such as labor cost incurred against total estimated labor cost. When billing runs ahead of earned revenue, the excess is a contract liability, which works like the deferred revenue any service business records. When earned revenue runs ahead of billing, you carry unbilled receivables, and a growing unbilled balance usually means invoices are late.
Tax reporting can differ from book reporting. IRS Publication 538 lists architecture among the fields that can make a corporation a qualified personal service corporation, and qualified PSCs can generally use the cash method regardless of size. Many firms keep accrual books for management and lenders while filing on the cash method. Our comparison of cash vs accrual accounting covers when that split makes sense.
The B101 framework separates basic services from additional services for a reason. Extra meetings, redesigns after owner program changes, added renderings and extended construction administration are all common sources of unpaid hours.
A workable process:
The unapproved hours report is often the single most useful page in the monthly pack, because it shows labor the firm has already spent and has not yet asked to be paid for.
Architecture firms carry heavy receivables because invoices go out monthly, owners review them against progress, and payment often follows a lender or board approval cycle.
Practical controls that shorten the cycle:
A rolling 13-week cash flow forecast built from the billing schedule and payroll calendar shows a shortfall weeks before it happens. If collections are the bottleneck, outsourced accounts receivable support can take the follow-up work off project managers.
Two federal rules matter for design firms in 2026.
Section 199A. Architecture and engineering are carved out of the specified service trade or business list, so owners of pass-through architecture firms can generally claim the qualified business income deduction above the income level where doctors, lawyers and accountants lose it. The One Big Beautiful Bill Act made the deduction permanent. See our Section 199A deduction guide for the wage and property limits.
Section 179D. The energy efficient commercial buildings deduction can be allocated to the designer of qualifying systems in buildings owned by government entities and other specified tax-exempt organizations, as explained on the IRS 179D page. The One Big Beautiful Bill Act ends the deduction for property whose construction begins after June 30, 2026. Firms that designed qualifying public or nonprofit buildings that started construction by that date should confirm with the owner whether an allocation is still available, and keep the energy model and certification on the project file.
Architecture-specific platforms such as Deltek Ajera, BQE Core and Monograph combine timesheets, phase budgets and billing. Smaller studios often pair QuickBooks Online with a time tracking tool like Harvest. When comparing tools, check that they can:
Many of the same selection criteria apply to contractors; our review of project cost tracking software walks through integration and reporting questions to ask vendors.
Firm-level levers such as pricing, staffing mix and overhead are covered in our post on profit margin improvement strategies. Firms without a finance lead often add a fractional CFO for professional services firms to run the monthly review and pricing analysis.
It depends on your overhead rate. Calculate your breakeven multiplier first (1 plus overhead rate), then set a target that covers your profit goal on top of it. A firm with a 150% overhead rate breaks even at 2.5, so a 2.8 target leaves roughly 11% of net revenue as profit.
No. Principals and marketing staff spend more time on business development and management, while production staff should carry most billable hours. Set targets by role and review them alongside the multiplier, since high utilization on underpriced projects still loses money.
Most design firms allocate overhead in proportion to direct labor cost, which is what the overhead rate and breakeven multiplier do. Recalculate the rate at least quarterly from actual results, because a new lease or a hiring round can move it several points.
Record them as a project cost and exclude them from net revenue when measuring your own team's performance. Track consultant budgets by phase as well, since a consultant overrun on a fixed fee comes straight out of your margin.
Contractors track materials, equipment and subcontractor costs against a construction budget, and labor is one cost among several. Architecture firms sell staff time, so direct labor and the overhead it carries drive almost all of the margin. That is why design firms manage to a multiplier, while contractors manage to gross profit percentage on each job.
Usually when project managers are spending evenings on billing, or when monthly reports arrive too late to change outcomes. An outsourced accounting team can handle coding, billing runs and project reports while your partners keep pricing and client decisions.
Madras Accountancy sets up and runs project accounting for architecture and engineering firms and for the CPA firms that serve them: phase coding, monthly billing, WIP and project profitability reports. Contact our team to scope a monthly package for your practice.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



