



R&D tax credit documentation requirements come down to one rule in the Treasury regulations: you must keep records detailed enough to prove that every dollar you claim meets the statutory definition of qualified research. In practice that means records organized by business component, showing the four-part test, the people and costs behind each project, and a credit computation that ties back to your ledger.
Refund claims on amended returns now need specific information at filing, Form 6765 has a business component section that becomes mandatory for tax years beginning after 2025, and the One Big Beautiful Bill Act (P.L. 119-21) changed how research costs are deducted. This guide covers the R&D tax credit documentation requirements that apply to 2026 returns, with a worked credit computation at the end.
The core documentation rule sits in Treas. Reg. § 1.41-4(d): "A taxpayer claiming a credit under section 41 must retain records in sufficiently usable form and detail to substantiate that the expenditures claimed are eligible for the credit." The regulation then points to the general recordkeeping rules in § 1.6001-1.
The regulation does not prescribe a format. What matters is that an examiner can follow each claimed dollar to a specific project and from that project to the statutory test. For how teams capture this evidence week to week, see our guide to the R&D documentation process and time tracking.
Every claim starts with IRC § 41(d). Qualified research must meet all four parts, and the statute says the test "shall be applied separately with respect to each business component of the taxpayer." A business component is "any product, process, computer software, technique, formula, or invention" held for sale, lease or license, or used in your own trade or business.
| Part of the test | What the statute requires | Documents that usually prove it |
|---|---|---|
| Section 174A expenditures | Costs are "treated as domestic research or experimental expenditures under section 174A" | General ledger detail, cost center mapping, Section 174A workpapers |
| Technological in nature | Research undertaken to discover information that is technological in nature | Engineering specs, technical design documents, reliance on engineering, physics, chemistry, biology or computer science |
| Business component (permitted purpose) | Information intended to develop a new or improved business component, relating to function, performance, reliability or quality | Project charters, product requirements, defined performance targets |
| Process of experimentation | "Substantially all of the activities" are elements of a process of experimentation | Test plans, iteration logs, failed prototypes, alternatives evaluated, results |
Among other exclusions, section 41(d)(4) rules out research after commercial production begins, adapting an existing product to a particular customer's need, duplicating an existing component, routine quality control testing and market research. Your project files should show why each claimed activity falls outside these exclusions.
The regulation does not use the word "contemporaneous." As practitioner guidance, records created while the work happens carry far more weight in an examination than estimates assembled years later. A sprint ticket dated March 2026 describing a failed approach is stronger evidence than an interview summary written in 2028.
The most useful records are the ones engineers already produce, such as version control history, design reviews and test logs. The work is mapping that material to business components and capturing time allocation for people whose wages you claim. A good starting point is the chart of accounts and cost center setup for funded startups, so research costs are separable in the ledger from day one.
Section 41(b) defines qualified research expenses (QREs) as in-house research expenses plus contract research expenses. Each category needs its own support.
Officer wages need extra care, because line 38 of Form 6765 asks for the total officer wages included in wage QREs.
Amended return claims face their own R&D tax credit documentation requirements. The IRS research credit amended return FAQs list the "five items of information" a claim must contain at filing to be considered valid:
Effective June 18, 2024, the IRS waived items 3 and 4 at filing, while noting "this information may be requested if a refund claim involving the Research Credit is selected for examination." Items 1, 2 and 5 are still required. The 45-day window to perfect a deficient claim has been extended "through Jan. 10, 2027." After that date, a deficient claim risks rejection without a chance to cure it.
The Form 6765 instructions name the e-file attachments "Form6765ClaimInformation.pdf" and, if you submit a credit study, "Form6765Study.pdf," with the exact pages identified. Refund claims are also bound by the limitation period. The IRS recordkeeping guidance says to keep records "for 3 years from the date you filed your original return or 2 years from the date you paid the tax, whichever is later" when you file a claim for credit or refund. Our explainer on how far back the IRS can audit you covers the longer periods that can apply.
The December 2025 instructions add reporting to the form itself. Section E asks for the number of business components, officer wages, acquisitions and new expense categories. Section G collects data by business component.
On timing, the instructions state: "For tax years beginning before 2026, Section G will be optional for all filers." Then: "For tax years beginning after 2025, Section G will be required." For a calendar-year company, that means the 2026 return filed in 2027.
When Section G applies, you must report "a minimum of 80% of total QREs or a maximum of 50 business components," listed in descending order of QREs, with the rest grouped as "Aggregate Business Components." Section G is not required if either of these applies:
The second exception does not cover amended returns, so a small company filing a refund claim may still need Section G. For how the credit then flows to your return, see our guide to Form 3800 and the general business credit.
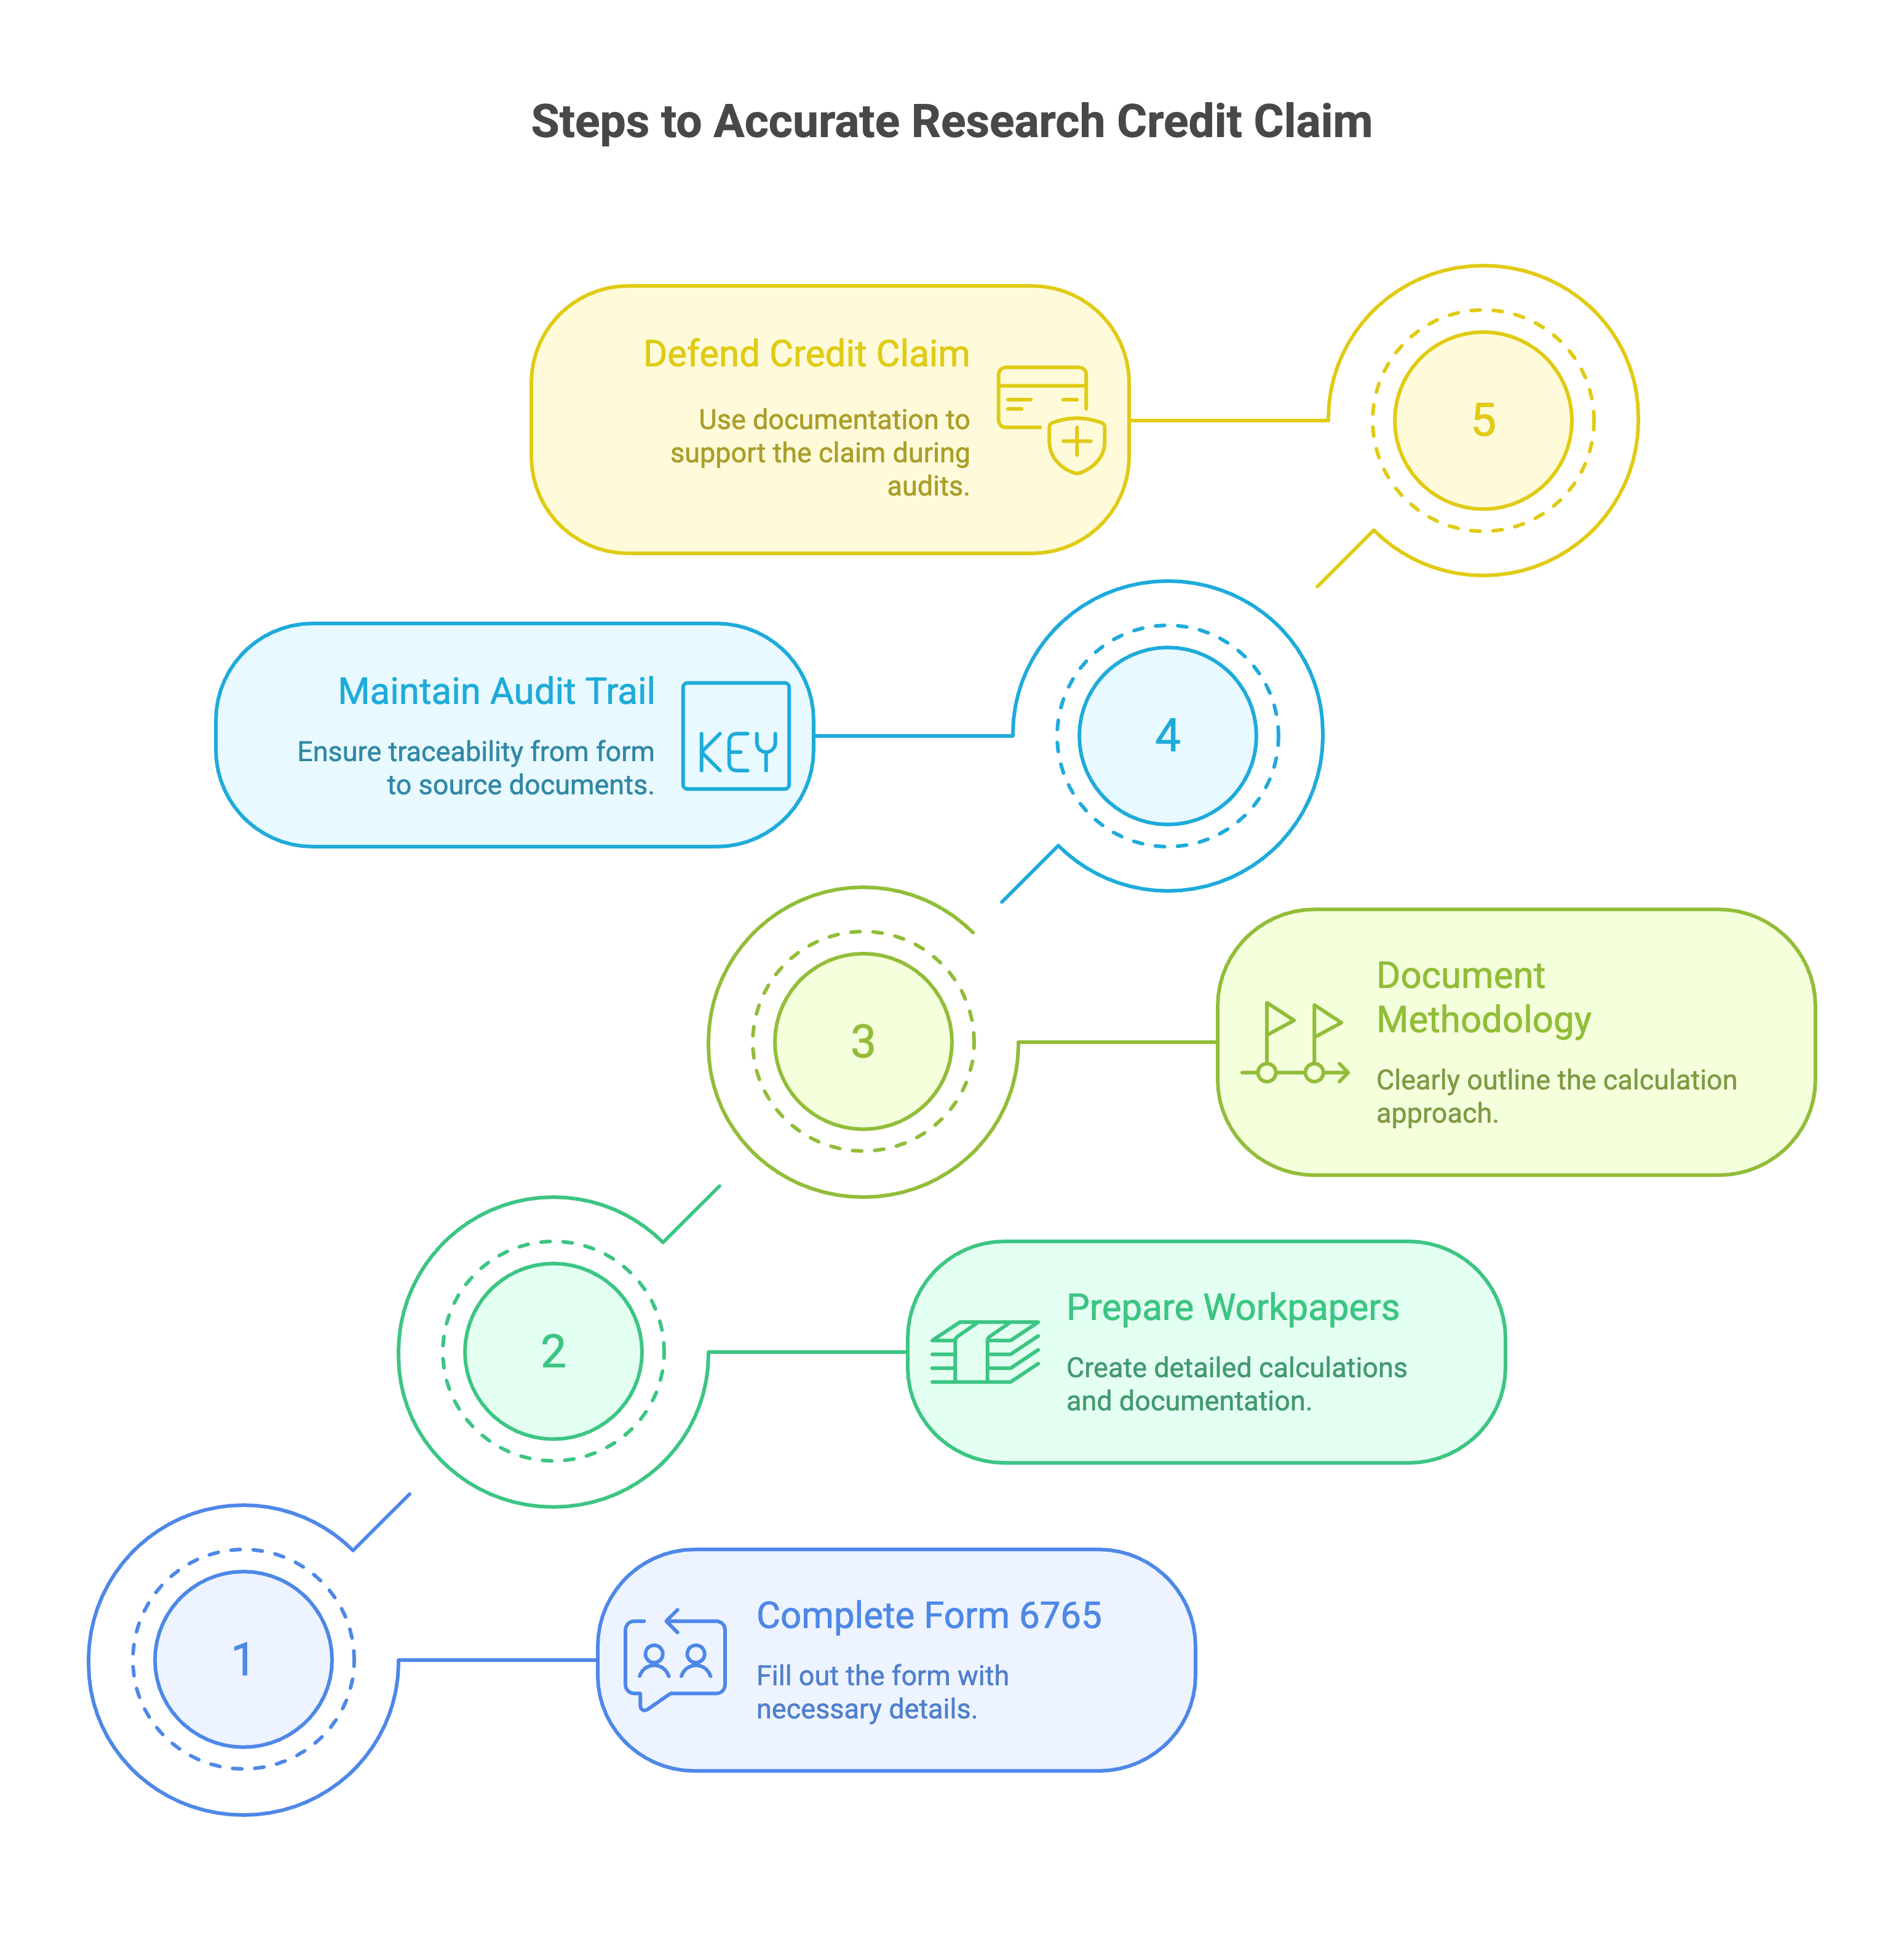
The statute's first test ties qualified research to Section 174A, so your deduction records and credit records must agree. The Form 6765 instructions confirm that P.L. 119-21 "added new section 174A" and that it "allows taxpayers to deduct amounts paid or incurred for domestic research and experimental expenditures in tax years beginning after December 31, 2024." Taxpayers may instead elect to capitalize and amortize domestic costs over "not less than 60 months." Foreign research stays outside Section 174A.
Rev. Proc. 2025-28 in Internal Revenue Bulletin 2025-38 explains the transition. Taxpayers with unamortized 2022 to 2024 domestic costs could deduct the balance "in full in the first taxable year beginning after December 31, 2024," or over two years. Small businesses meeting the section 448(c) test ($31,000,000 for 2025) had a retroactive election, which had to be made by July 6, 2026. That deadline has passed, so 2026 planning is about current-year treatment. Our Section 174 and OBBBA explainer covers the transition elections.
The law also restored the coordination rule in IRC § 280C(c). Your Section 174A expenditures are "reduced by the amount of the credit allowed," unless you elect a reduced credit on a timely filed original return. The election is irrevocable. Keep the computation showing which approach you used. If you also report R&D for GAAP, our article on ASC 730 treatment of R&D costs explains why book R&D and tax QREs rarely match.
Startups with little income tax liability can apply part of the credit against payroll taxes. Under the Form 6765 instructions, a qualified small business has "gross receipts of less than $5 million for the tax year" and "no gross receipts for any tax year before the 5-tax-year period ending with the tax year." The elected amount cannot exceed $500,000.
Documentation for this election goes beyond the credit study:
Our guide to a virtual CFO for startups shows how the payroll offset fits into runway planning.
The IRS says research credit refund claims "are currently examined in a substantial number of cases". As practitioner guidance based on what Form 6765 asks, these patterns draw attention:
Our list of common IRS audit triggers covers return-wide risks. If an examination does start, an organized IRS audit response pack with indexed exhibits by business component speeds the information document request stage.
Illustrative example: a calendar-year C corporation has these 2026 research costs:
| QRE category | Amount paid | Counted | QRE |
|---|---|---|---|
| Wages for qualified services | $900,000 | 100% | $900,000 |
| Supplies consumed in testing | $60,000 | 100% | $60,000 |
| Cloud computing for test environments | $40,000 | 100% | $40,000 |
| Contract research | $200,000 | 65% | $130,000 |
| Total 2026 QREs | $1,130,000 |
Under section 41(c)(4), the alternative simplified credit equals "14 percent of so much of the qualified research expenses for the taxable year as exceeds 50 percent of the average qualified research expenses for the 3 taxable years preceding." Prior QREs were $700,000 (2023), $820,000 (2024) and $960,000 (2025).
Without the election, the company keeps the $100,333.33 credit but reduces its Section 174A deduction by the same amount. At the 21% corporate rate, that costs $21,070 in tax, so the net benefit is the same $79,263.33 when the company is taxable. If the company had no QREs in any one of the three prior years, the statute sets the ASC at 6% of current QREs.
With QREs under $1.5 million, this company could skip Section G on a 2026 original return if its average gross receipts are $50 million or less. Our guide on how small businesses can maximize R&D tax credits covers choosing between the ASC and the regular credit.
What are the R&D tax credit documentation requirements in one sentence? Treas. Reg. § 1.41-4(d) requires records "in sufficiently usable form and detail" to show each claimed expense is eligible. In practice that means project evidence of the four-part test by business component, plus payroll, invoice and contract support for each QRE.
Is Form 6765 Section G mandatory for 2026? Yes, for tax years beginning after 2025, unless an exception applies. The exceptions cover qualified small businesses electing the payroll credit, and original-return filers with QREs of $1.5 million or less and average gross receipts of $50 million or less.
What must an amended return research credit claim include? You must identify all business components, the research activities for each, and the total wage, supply and contract research QREs. The names of individuals and the information they sought are waived at filing but may be requested in an examination.
Do I need timesheets to claim wage QREs? The regulations do not require a specific format. As practitioner guidance, use a reasoned allocation supported by project records made during the year.
How long should I keep R&D credit records? Keep them at least through the limitation period for the return and any refund claim. As practitioner guidance, keep files for carried-forward credits until the last carryforward year closes.
Can a startup use the credit against payroll taxes? Yes, if it is a qualified small business with gross receipts under $5 million and no receipts before the five-year window. The election, capped at $500,000, must be made on a timely filed original return.
Madras Accountancy supports US businesses and CPA firms with bookkeeping that separates research costs by project, tax preparation including Form 6765 and Form 8974, CFO and advisory support, and audit support during IRS examinations. To set up records that meet the IRS requirements before your 2026 return, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



