


SaaS revenue recognition under ASC 606 comes down to one question asked five different ways: what did you promise the customer, and when did they get it? For a plain subscription, you recognize the fee evenly over the term. The trouble starts with everything bolted onto the subscription: setup fees, discounted renewals, usage overages, multi-year prepayments and the sales commissions paid to land the deal. Several FASB updates issued in 2025 also touch software companies, taking effect for calendar-year companies between 2026 and 2028.
ASC 606, Revenue from Contracts with Customers, was issued by the FASB in ASU 2014-09 and replaced the software-specific rules in ASC 985-605, including the VSOE requirement. Public companies adopted it for annual periods beginning after December 15, 2017, private companies a year later (with one more year of deferral under ASU 2020-05). A seed-stage startup that only files tax returns isn't required to follow it, but once a lender or Series A investor asks for reviewed or audited GAAP financials, you are. Our note on what an audit of startup financial statements costs explains when investors typically start requiring one.
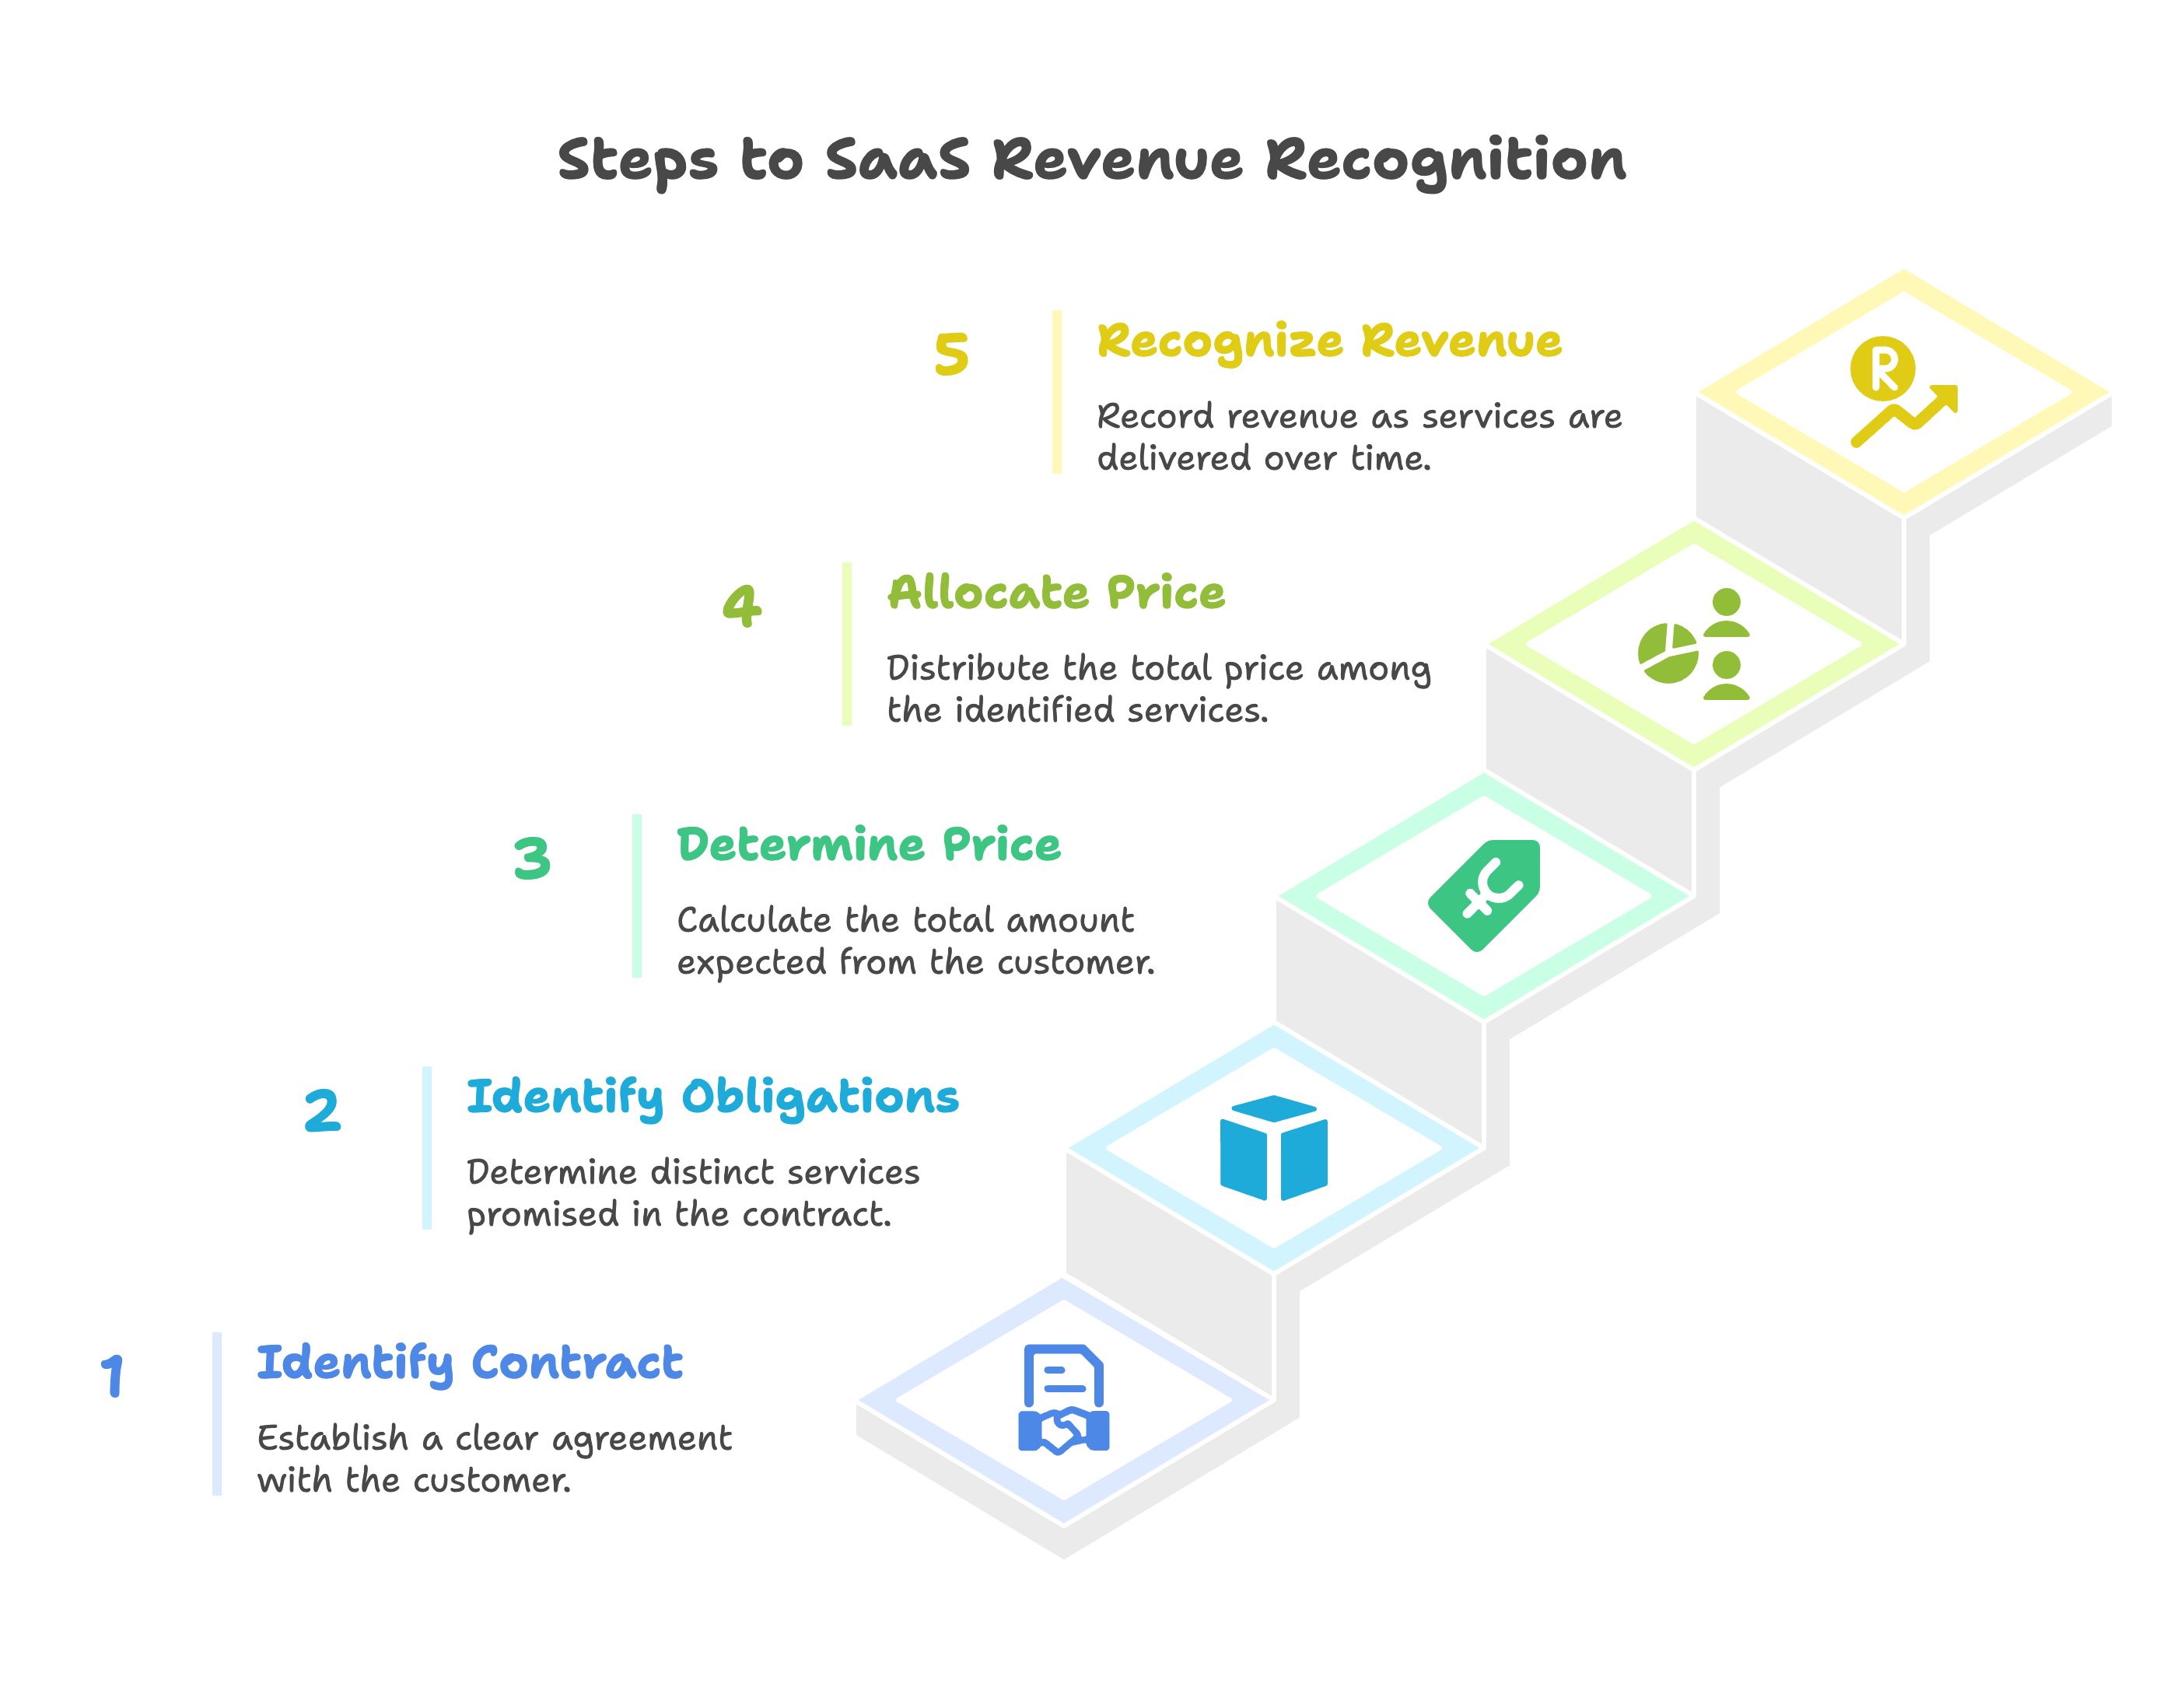
| Step | What the standard asks | The SaaS question you're really answering |
|---|---|---|
| 1. Identify the contract | Is there an enforceable agreement with commercial substance and probable collection? | How long is the enforceable term once cancellation rights are considered? |
| 2. Identify performance obligations | Which promised goods or services are distinct? | Is setup, training or premium support separate from the subscription? |
| 3. Determine the transaction price | What consideration do you expect, including variable amounts? | How do usage fees, SLA credits, discounts and prepayments change the price? |
| 4. Allocate the price | Split the price by relative standalone selling price (SSP). | What would each piece sell for on its own? |
| 5. Recognize revenue | Recognize when or as each obligation is satisfied. | Ratably over the term, as usage occurs, or at a point in time? |
A clickwrap order form, a signed MSA or terms accepted at checkout can all create a contract. The SaaS issue is term: ASC 606 looks at the period during which both parties have enforceable rights, so a "12-month" agreement the customer can cancel any month without a substantive penalty is month-to-month for accounting purposes.
If the customer can't take possession of the software without a significant penalty and run it on its own hardware, you have a service. If it can, you may have a license recognized at a point in time. For a true SaaS subscription, access, hosting, bug fixes, uptime and when-and-if-available updates are typically one stand-ready obligation satisfied over time, treated as a series of distinct daily or monthly service periods. Implementation, training, premium support and custom development each need a distinctness test under ASC 606-10-25-19: can the customer benefit from the item on its own or with readily available resources, and is it separately identifiable from the other promises?
The transaction price is what you expect to be entitled to, not just the fixed fee on the order form. The adjustments that come up most in SaaS:
Allocation follows relative standalone selling price. Observed prices are the best evidence; otherwise estimate using adjusted market assessment or expected cost plus margin.
Example: a customer pays $1,200 for a one-year subscription plus a live training package. The training is distinct because third-party consultants sell the same training. Standalone prices are $1,000 for the subscription and $500 for training.
The invoice may show $1,200 for the subscription and "free" training. The invoice doesn't drive the allocation.
A stand-ready subscription is satisfied evenly over the term, so straight-line recognition is the norm. A $12,000 annual subscription billed upfront on January 1 becomes $1,000 of revenue each month, with the unearned balance sitting as a contract liability. Our guide to deferred revenue as a liability shows the journal entries and the roll-forward auditors expect.
Revenue starts when the customer has access, which may be later than the signature date. Free trials generate no revenue.
This is the most common correction we make in SaaS revenue schedules. The Deloitte guidance on implementation services in hosted software arrangements lists the factors that point toward distinctness: other providers offer the same services, the software works reasonably well without them, and the services don't significantly customize the platform. Simple account setup, data migration into your own system and user provisioning usually fail that test.
When the fee isn't distinct, it's treated as an advance payment for the subscription.
Example. A customer signs a one-year contract: $24,000 subscription plus a $6,000 nonrefundable implementation fee. Implementation takes the first month and isn't distinct.
If implementation is genuinely distinct (a complex integration a systems integrator could also perform), it's a separate obligation recognized as the work is performed.
An option to buy additional services is a separate performance obligation only if it gives the customer a material right they wouldn't get without entering the contract. Common SaaS examples are renewal prices locked well below list (beyond what comparable customers get), free months on renewal, the setup-fee waiver above, and add-on modules discounted only for this customer.
Part of the transaction price goes to the material right and is recognized when the option is exercised or expires. A renewal at normal SSP isn't one. PwC's analysis of activation fees and material rights shows how the size of the fee relative to ongoing pricing drives the conclusion, so document the judgment contract by contract.
Usage pricing is variable consideration, but most SaaS companies don't need to forecast it. Two provisions do the work.
The variable consideration allocation exception (ASC 606-10-32-40). Because the subscription is a series of distinct service periods, usage fees that relate to a period can be allocated entirely to that period. Example: a $2,000 monthly platform fee plus $0.02 per API call above 100,000 calls. In a month with 400,000 calls, revenue is $2,000 + (300,000 × $0.02) = $8,000.
The "right to invoice" practical expedient (ASC 606-10-55-18). If the amount you can bill corresponds directly with the value delivered to date, you recognize revenue in that amount. Pure pay-as-you-go pricing usually qualifies. Tiered rates that drop sharply after a threshold, or large upfront fees, may break the "corresponds directly" condition. Prepaid credits and breakage. Expiring credits are recognized as consumed, with expected breakage recognized in proportion to usage if you can reasonably estimate it, or once use becomes remote if you can't.
ASC 340-40 requires you to capitalize the incremental costs of obtaining a contract that you expect to recover. Sales commissions are the main one, along with the payroll taxes on them and manager commissions that wouldn't be paid without the deal. Base salary and marketing spend aren't incremental.
The asset is amortized consistently with the transfer of the related services, which can include anticipated renewals. Immediate expensing is allowed only when the amortization period would be one year or less, so it often doesn't apply even to one-year SaaS contracts.
Example. An account executive earns 10% on a new $60,000 annual contract ($6,000). Renewals pay 2% ($1,200). Because the renewal commission isn't commensurate, the $6,000 relates to more than year one. Over a four-year expected customer life, straight-line amortization is $125 per month. A common alternative amortizes the commensurate portion ($1,200) over the initial 12 months and the remaining $4,800 over the expected life. Either method needs consistent application and retention data to support it.
Book capitalization doesn't drive the tax treatment. Our plain-English guide to ASC 740 income tax accounting covers how the difference becomes a deferred tax item.
Upsells are also where ARR and GAAP revenue drift apart. ARR annualizes the current run rate; GAAP revenue is what was earned in the period. Our article on SaaS metrics for finance teams explains how to reconcile the two for board reporting.
The FASB's post-implementation review in late 2024 found ASC 606 working as intended. Since then, these updates matter to software companies:
| Update | What it does for SaaS companies | Effective (all entities unless noted) |
|---|---|---|
| ASU 2025-04 (Topics 718 and 606) | Clarifies accounting for warrants or shares issued to customers. Purchase-based vesting targets are performance conditions, the 606 variable consideration constraint doesn't apply, and forfeitures must be estimated. | Annual periods beginning after Dec. 15, 2026 |
| ASU 2025-05 (Topic 326) | Practical expedient for estimating credit losses on current receivables and contract assets from ASC 606 contracts. | Annual periods beginning after Dec. 15, 2025 (calendar 2026) |
| ASU 2025-06 (Subtopic 350-40) | Replaces the "project stage" model for internal-use software, which includes a SaaS company's own hosted platform, with a management-authorization and probable-to-complete threshold. | Annual periods beginning after Dec. 15, 2027; early adoption permitted |
| ASU 2025-07 (Topics 815 and 606) | Equity received from a customer as payment stays under ASC 606 until the right to it becomes unconditional. | Annual periods beginning after Dec. 15, 2026 |
Equity given to customers under ASU 2025-04 follows ASC 718 measurement rules, covered in our ASC 718 stock compensation guide. ASU 2025-05 simplifies the expected-loss model in our CECL guide, which applies to SaaS receivables and unbilled contract assets. And if you're acquiring a SaaS company, ASU 2021-08 has the acquirer measure acquired deferred revenue under ASC 606 rather than at fair value; see our ASC 805 business combinations guide for the rest of the purchase accounting.
Auditors treat revenue as a presumed fraud risk. Have these ready before fieldwork:
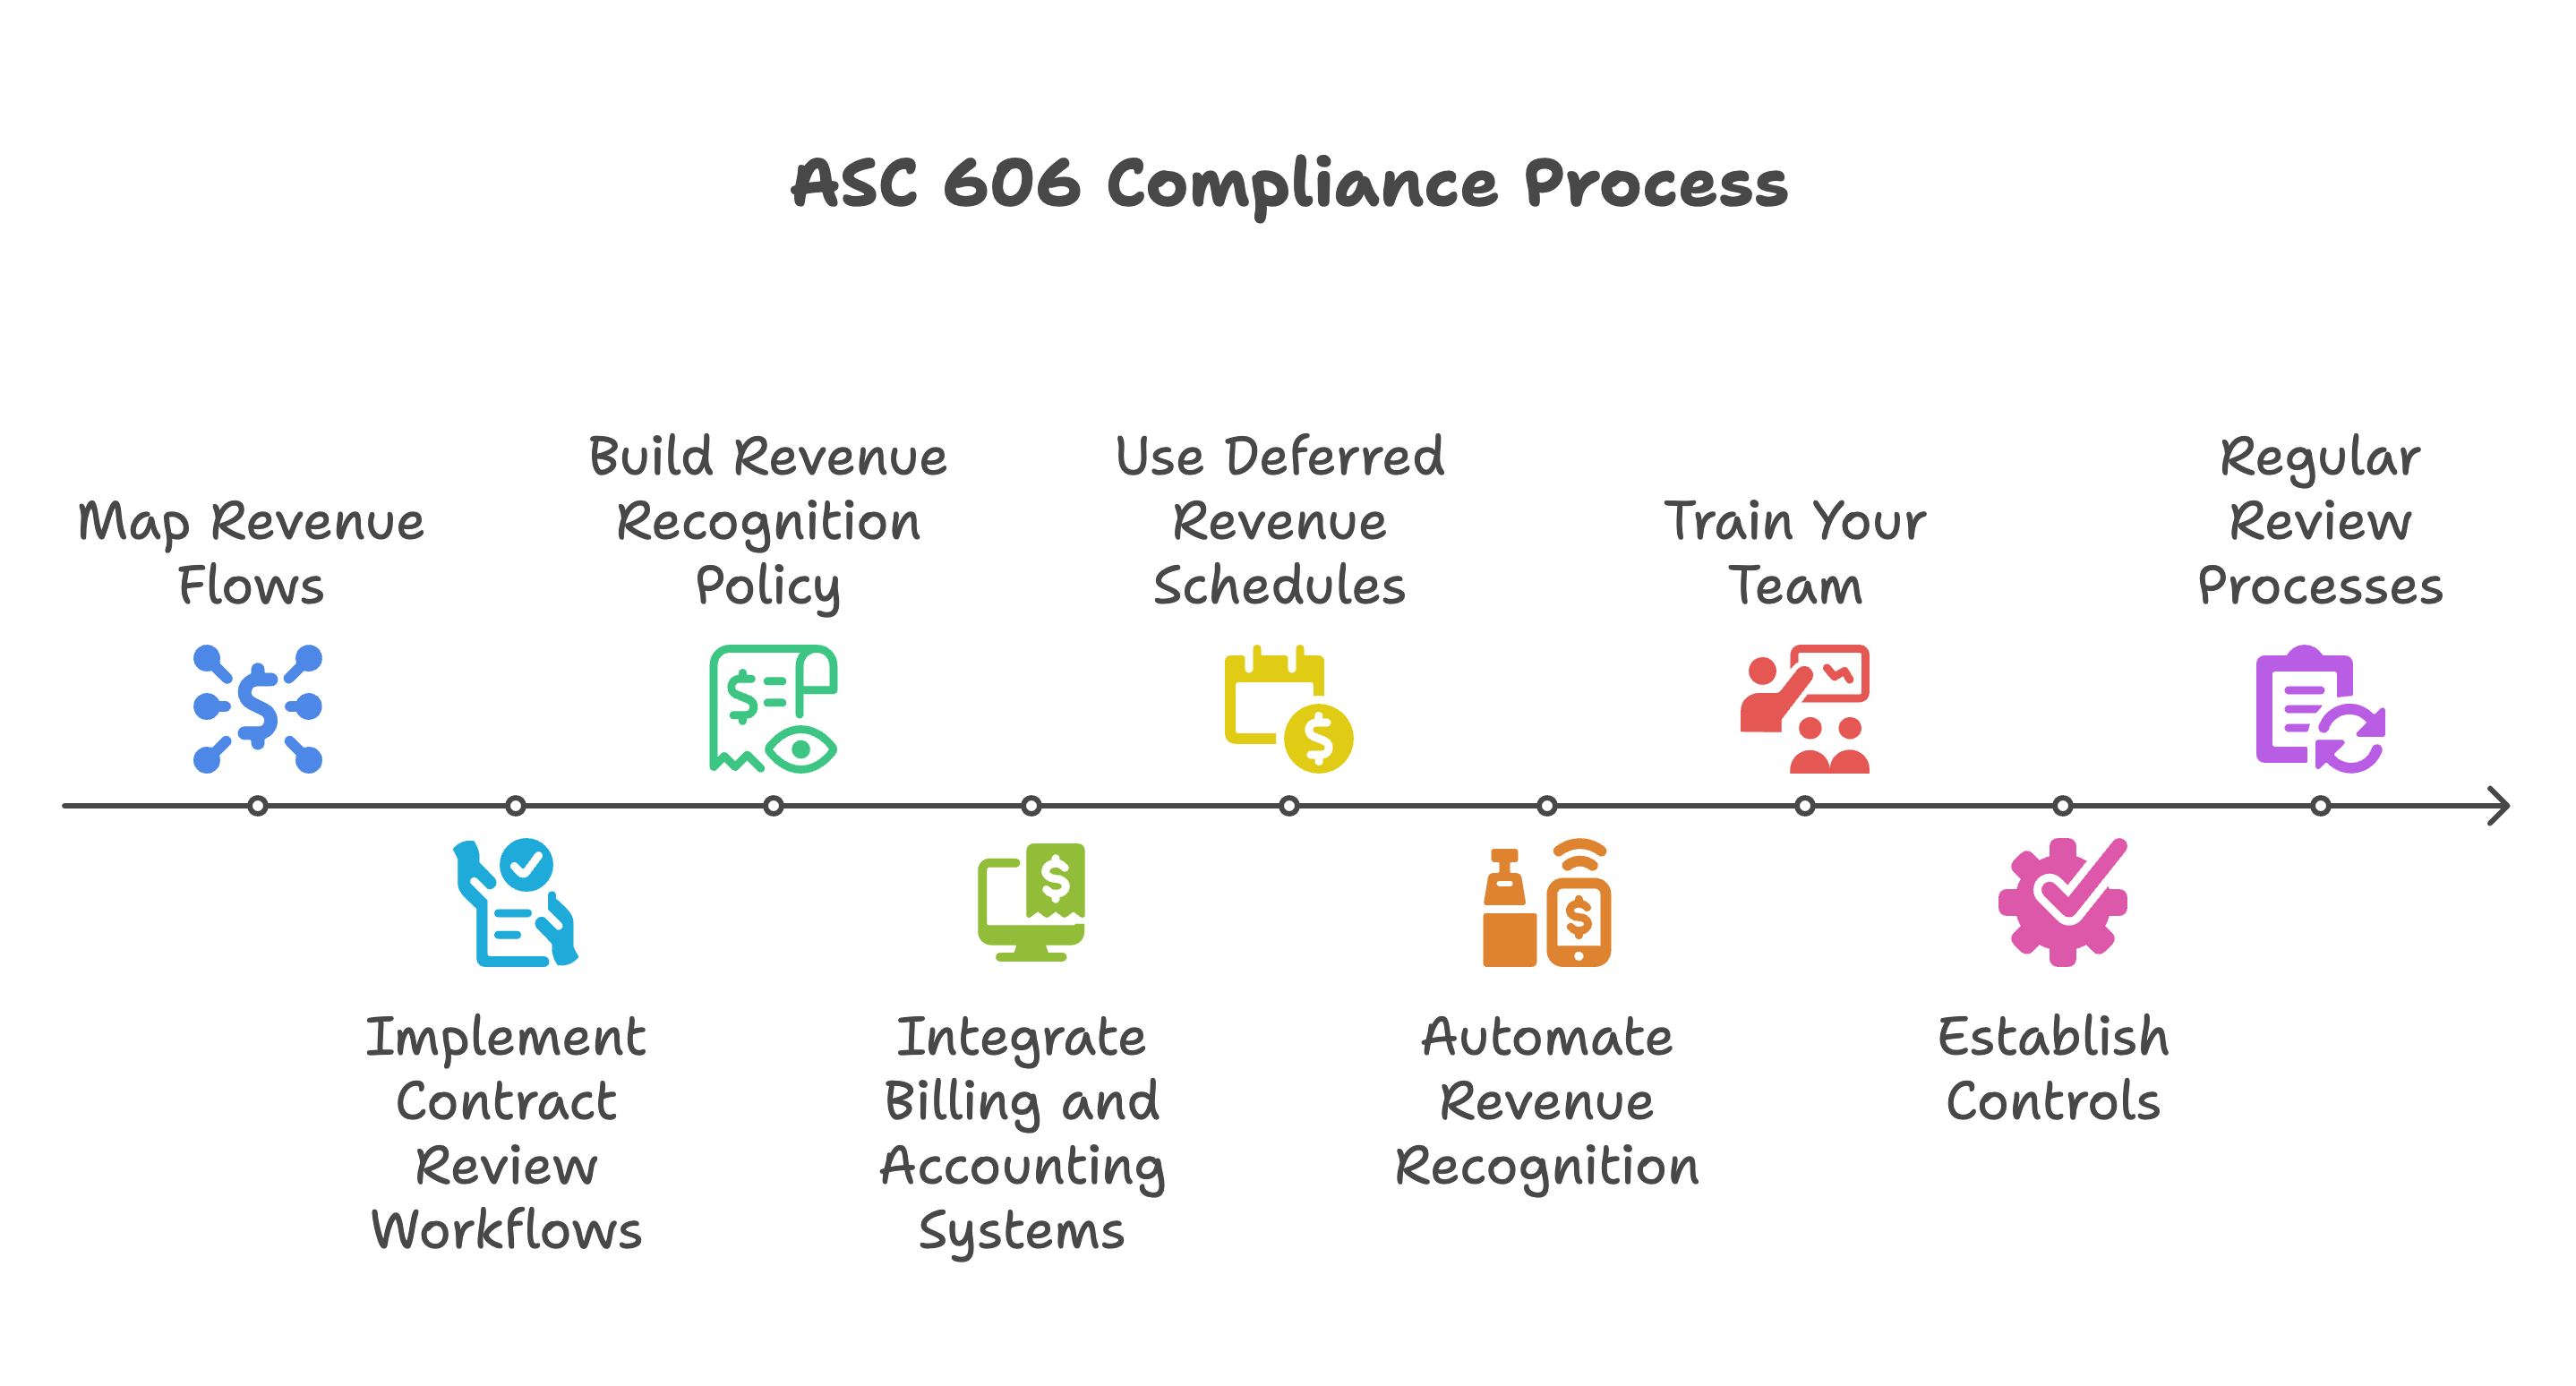
Most revenue errors we find trace back to the close, such as billing changes that never reach the revenue schedule. A disciplined month-end close checklist for startups catches those early, and our PBC request list for first-time audits shows what the auditor will ask for. For more worked scenarios, see ASC 606 SaaS examples and common pitfalls.
A hosted subscription is almost always recognized over time, because the customer benefits from access continuously. Point-in-time recognition applies to a software license the customer can download and run without significant penalty, or to distinct one-time deliverables such as a training session.
Yes, when commissions are incremental and expected to be recovered. Immediate expensing is allowed only if the amortization period would be one year or less, and because SaaS commissions often benefit expected renewals, many companies amortize them over several years.
In most SaaS contracts, overage revenue lands in the month the usage happens, because each period's usage fees can be allocated to that period. Pure pay-as-you-go contracts can often use the right-to-invoice expedient instead.
No. ARR annualizes the current recurring run rate and ignores timing, setup fees and usage. GAAP revenue is what was earned in the period, so the two differ whenever there are upsells, churn or one-time fees.
If your revenue schedule lives in a spreadsheet nobody outside finance can follow, put a written policy and a monthly reconciliation in place a quarter or two before your first audit. Madras Accountancy works with SaaS companies and the CPA firms that serve them on revenue schedules, commission capitalization and audit preparation. See how our outsourced accounting for SaaS companies works, or talk to our team about your ASC 606 setup.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



