


Sales tax in San Jose is 10.00% for most addresses in the city as of October 2026. That figure is the California statewide base of 7.25%, plus 2.50% in Santa Clara County district taxes, plus San Jose's own 0.25% city district tax. If your system still shows 9.375%, that rate ended on March 31, 2026.
The increase came from Santa Clara County's 0.625% general district tax (Measure A), approved by voters in a November 2025 special election and effective April 1, 2026. Every taxable sale or purchase delivered to a San Jose address picked up the extra 0.625% on that date.
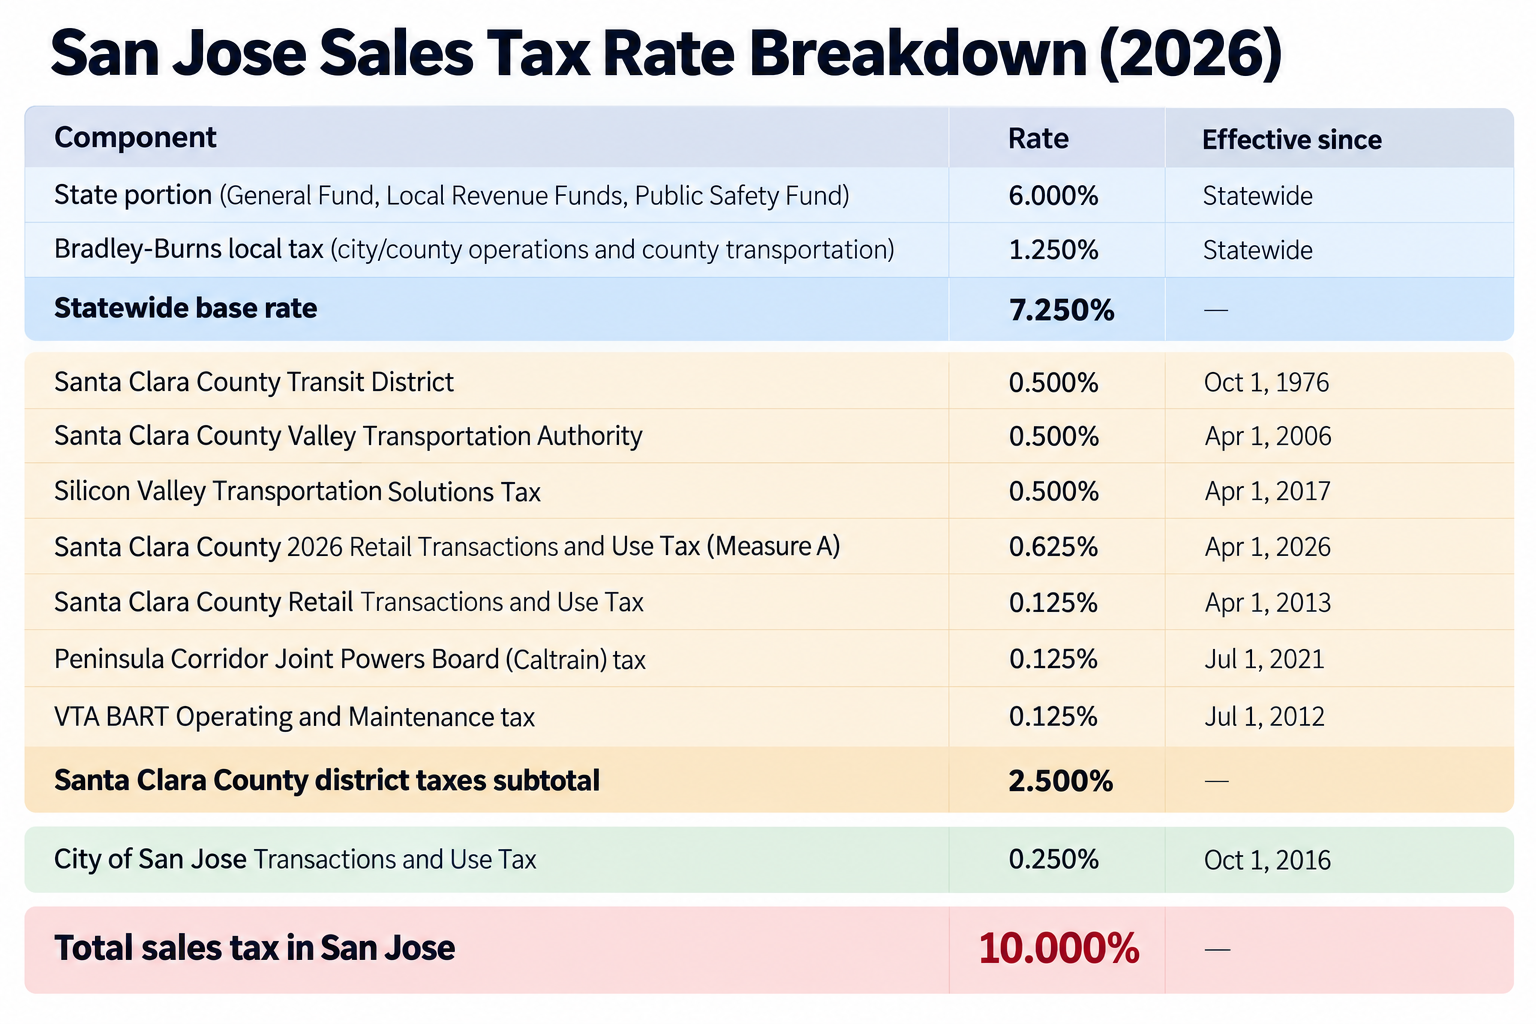
On a $2,000 laptop sold at a San Jose store, that's $200 in tax, against $187.50 under the old 9.375% rate. A retailer that didn't update its POS on April 1 has under-collected on every ticket since, and CDTFA assesses the shortfall against the seller.
People searching "city of san jose tax rate" usually want either the sales tax rate (10.00%) or the City's own Business Tax. Different agencies administer them.
Sales tax is reported to CDTFA on your state return, including San Jose's 0.25% city tax. There is no separate city sales tax filing.
San Jose Business Tax is a city tax administered by the City's Finance Department. Anyone doing business in San Jose must register for a Business Tax Certificate within 90 days of starting, and the tax renews annually. The City sets the amounts; check the City of San José business tax page for your category.
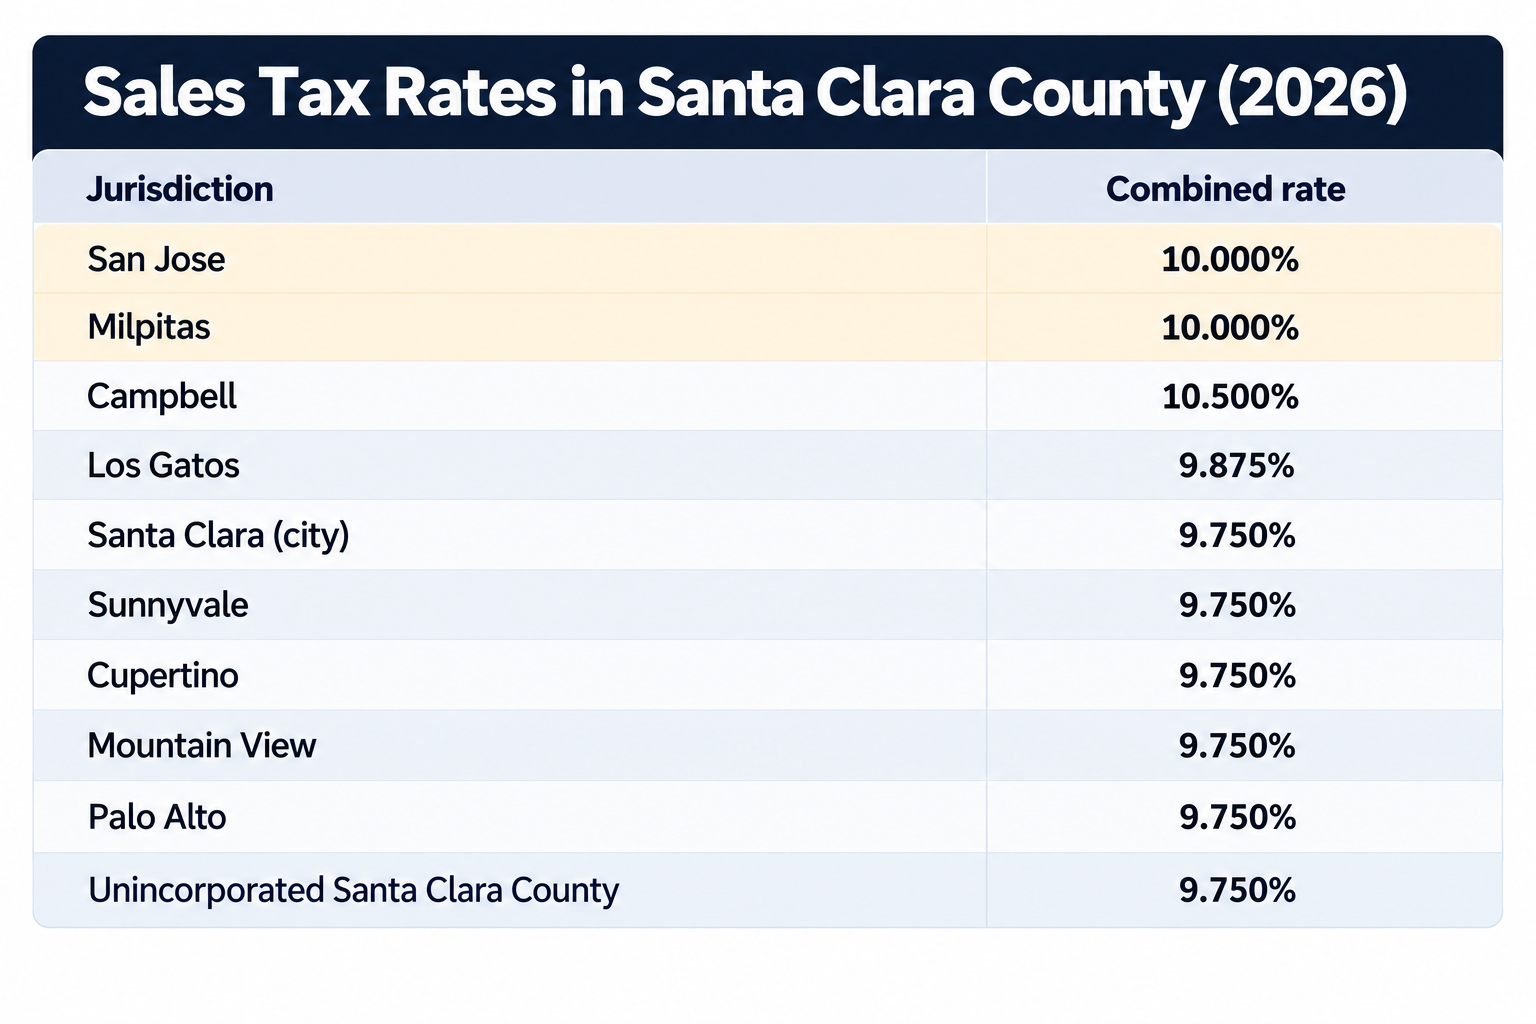
Also check the address itself. A "San Jose" mailing address doesn't guarantee San Jose city limits; several local ZIP codes mix in addresses in Campbell, the city of Santa Clara or unincorporated county land. Nearby rates from CDTFA's table effective October 1, 2026:
For deliveries, use CDTFA's address-level lookup, not the ZIP code. Our explainer on destination-based vs. origin-based sourcing rules covers which district rate applies when you ship.
For other California markets, our Sacramento sales tax guide, Orange County sales tax guide and San Diego sales tax guide break down those local rates.
A San Jose storefront, office, warehouse or employee gives you physical presence in California, and you collect from day one.
Out-of-state sellers fall under California's economic nexus rule. Per CDTFA's guidance on remote sellers, you must register and collect once your total combined sales of tangible personal property for delivery into California, counting your related entities, exceed $500,000 in the preceding or current calendar year. There's no transaction-count test. Once you cross the line, you collect on every taxable California sale, not just those shipped to San Jose.
Marketplace facilitators such as Amazon collect and remit on sales through their platforms, but you still track your direct website sales. Our guide to economic nexus for growing businesses walks through how to monitor thresholds across states.
You register once with the California Department of Tax and Fee Administration (CDTFA) for a seller's permit covering every California location you report. You don't register with San Jose for sales tax.
What you'll need for the online application:
The permit is free, though CDTFA can require a security deposit from higher-risk applicants, often new businesses. Out-of-state sellers who meet the economic nexus test register for a Certificate of Registration, Use Tax instead of a seller's permit.
With a permit, you can accept resale certificates from customers and issue them to suppliers. For how the two differ, see our post on resale certificates vs. sales tax permits.
California taxes the retail sale of tangible personal property unless an exemption applies. Most services are not taxed.
Groceries vs. prepared food. Unprepared food for home consumption is exempt. Hot food, meals served at your premises and most restaurant sales are taxable at the full 10%.
Shipping charges. Under Regulation 1628, a separately stated charge for shipping by common carrier, USPS or an independent contractor is excluded from the taxable amount, up to your actual shipping cost. Any markup above actual cost is taxable. A charge labeled only "handling" is taxable, and on "shipping and handling" only the postage or freight portion is excluded. If you deliver in your own vehicle, the charge is generally taxable unless the sale is complete before delivery begins.
Use tax. When your business buys equipment or supplies from a vendor that doesn't charge California tax, you owe use tax at your local rate (10% in San Jose) and report it on your sales tax return. A $50,000 server rack bought from an out-of-state reseller with no California tax means $5,000 of use tax.
Through December 31, 2026: Prewritten software sold on physical media (disc, USB) is taxable. The same software delivered by download, with no tangible media, is not taxable. SaaS is not taxable. Custom software is not taxable.
From January 1, 2027: Senate Bill 122 (Stats. 2026, ch. 23), signed June 29, 2026, adds "digital products" to the definition of tangible personal property. According to CDTFA Special Notice L-1036, a digital product is prewritten software transferred on media, transferred electronically or accessed remotely. That brings downloaded software and SaaS into the tax base. A $1,200 annual SaaS subscription sold to a San Jose customer would carry $120 in tax.
CDTFA lists digital books, music, video, video games, cryptocurrency and "digital infrastructure" (cloud platforms where customers build and run their own applications) as not digital products. Exemptions include custom software, digital products transferred with reproduction and distribution rights, products bought solely for use outside California, and digital products representing a service (which specifically does not cover SaaS).
Other points from the notice:
CDTFA's regulations were still in draft as of October 2026, with open questions on usage-based pricing and the SaaS/digital infrastructure line. Software sellers should review contracts, billing and customer address data now. For the multistate picture, see our guide on whether SaaS is taxable and where.
Resale. Buy inventory tax-free with a valid California resale certificate. Anything you later pull from inventory for your own use is subject to use tax. Our guide to managing sales tax exemptions and resale certificates covers documentation and expiry checks.
Manufacturing and R&D partial exemption. Under Regulation 1525.4, qualified manufacturers and certain research and development businesses get a 3.9375% exemption (state portion only) on qualifying equipment through June 30, 2030. District and local taxes still apply, so a San Jose manufacturer pays 6.0625% instead of 10%, after giving the seller a partial exemption certificate. On a $400,000 production line, that saves $15,750.
Sales for use outside California. Goods shipped by you to an out-of-state customer are generally not subject to California tax. Keep the shipping documents.
CDTFA assigns your filing frequency based on reported tax. The common bases:
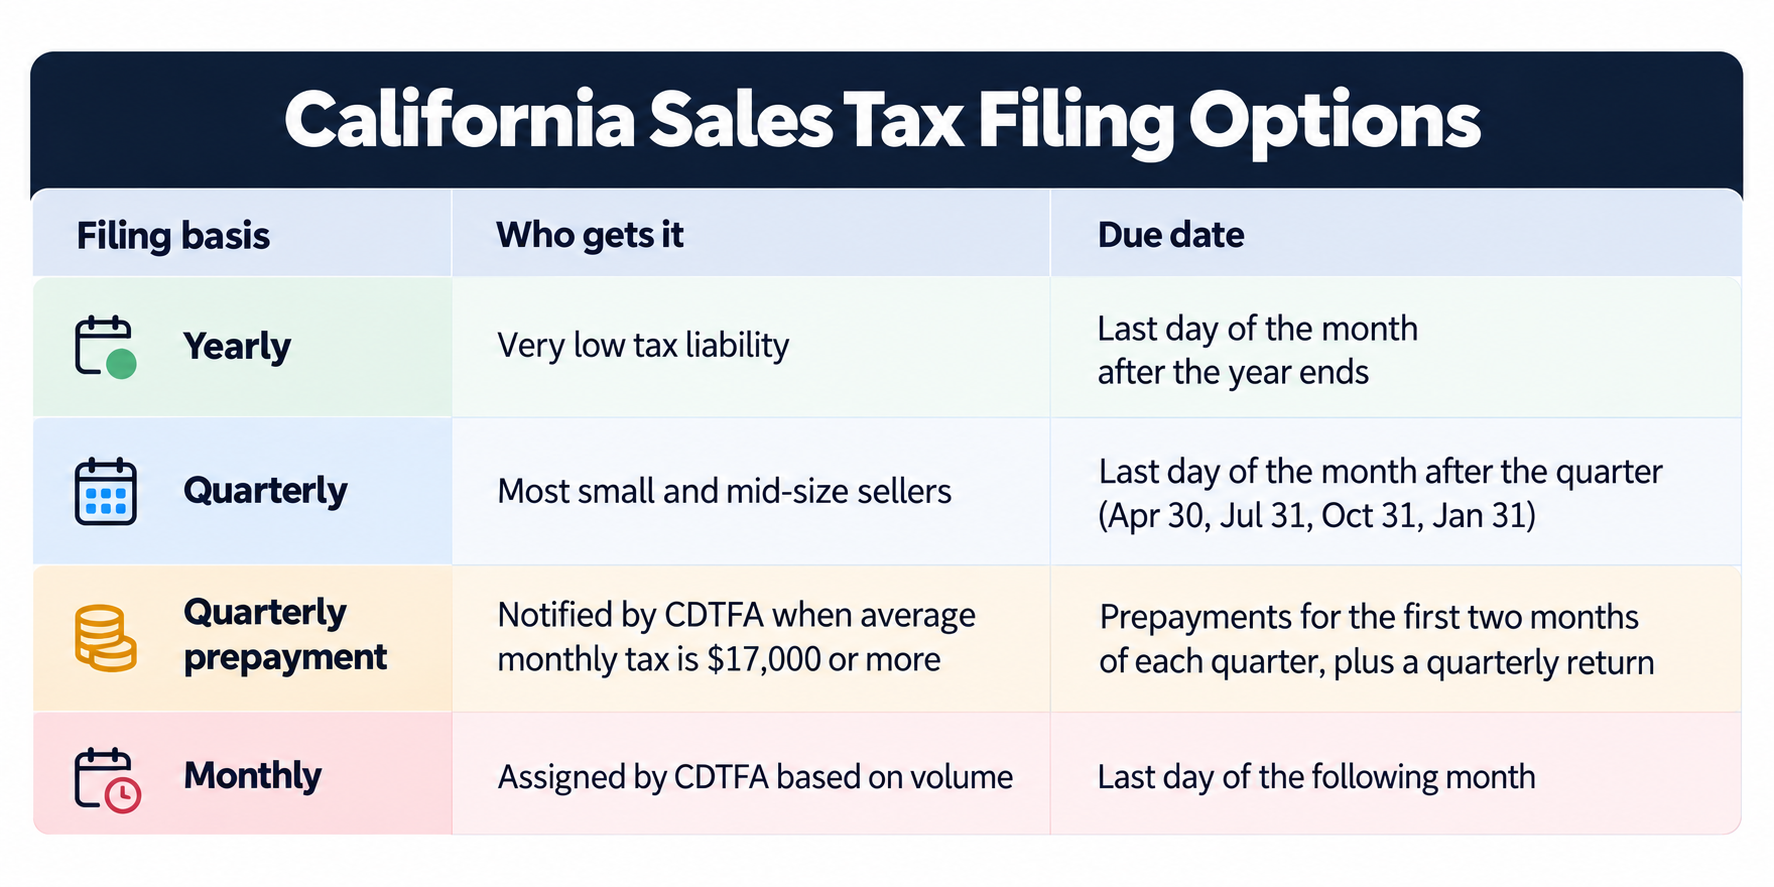
Weekend or state holiday due dates move to the next business day. You file online and report sales by location; CDTFA distributes the local and district shares.
Late filing or late payment carries a 10% penalty, capped at 10% of the tax on any one return, plus interest. CDTFA can waive the penalty for reasonable cause if you file a statement under penalty of perjury.
If you've been under-collecting (still charging 9.375% after April 1, say), amend the affected periods before CDTFA finds it. Our guide on how to handle a sales tax audit explains what auditors test first.
California district rates change on January 1, April 1, July 1 and October 1, and one ballot measure, like Santa Clara County's, can move every address in a county. Build a quarterly check into your close: download CDTFA's rate table, compare it to your POS and e-commerce settings, and test a few real addresses.
Sellers with multi-state volume usually use rate software that updates automatically. Our comparison of sales tax automation software covers the main options. For a contrast, our Oklahoma sales tax guide shows a different state-administered local tax system.
If your systems still charge 9.375%, or you sell software that becomes taxable in January, fix rates first, then plan 2027 billing. Madras Accountancy handles CDTFA registration, return preparation and rate reviews for California businesses and the CPA firms that serve them. Talk to our sales tax team.
What is the sales tax in San Jose in 2026? 10.00% for addresses inside San Jose city limits, effective April 1, 2026. Before that date it was 9.375%. The 0.625% increase came from Santa Clara County's Measure A district tax.
Why does my receipt from a "San Jose" address show 10.5% or 9.75%? The address is probably outside San Jose city limits. Campbell is 10.5%, while the city of Santa Clara and unincorporated Santa Clara County are 9.75%. Rates follow jurisdiction boundaries, not mailing addresses or ZIP codes.
Do I need a separate San Jose sales tax permit? No. Your CDTFA seller's permit covers San Jose. You do need a separate San Jose Business Tax Certificate from the City's Finance Department, which is a different tax.
Is SaaS taxable in San Jose? Not in 2026. Starting January 1, 2027, SB 122 makes SaaS and electronically delivered prewritten software taxable in California, so SaaS sold to a San Jose customer will carry 10% tax unless an exemption applies.
Is the use tax rate in San Jose the same as the sales tax rate? Yes, 10%. Businesses report it on the CDTFA return; consumers without a seller's permit can report it on their California income tax return.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



