

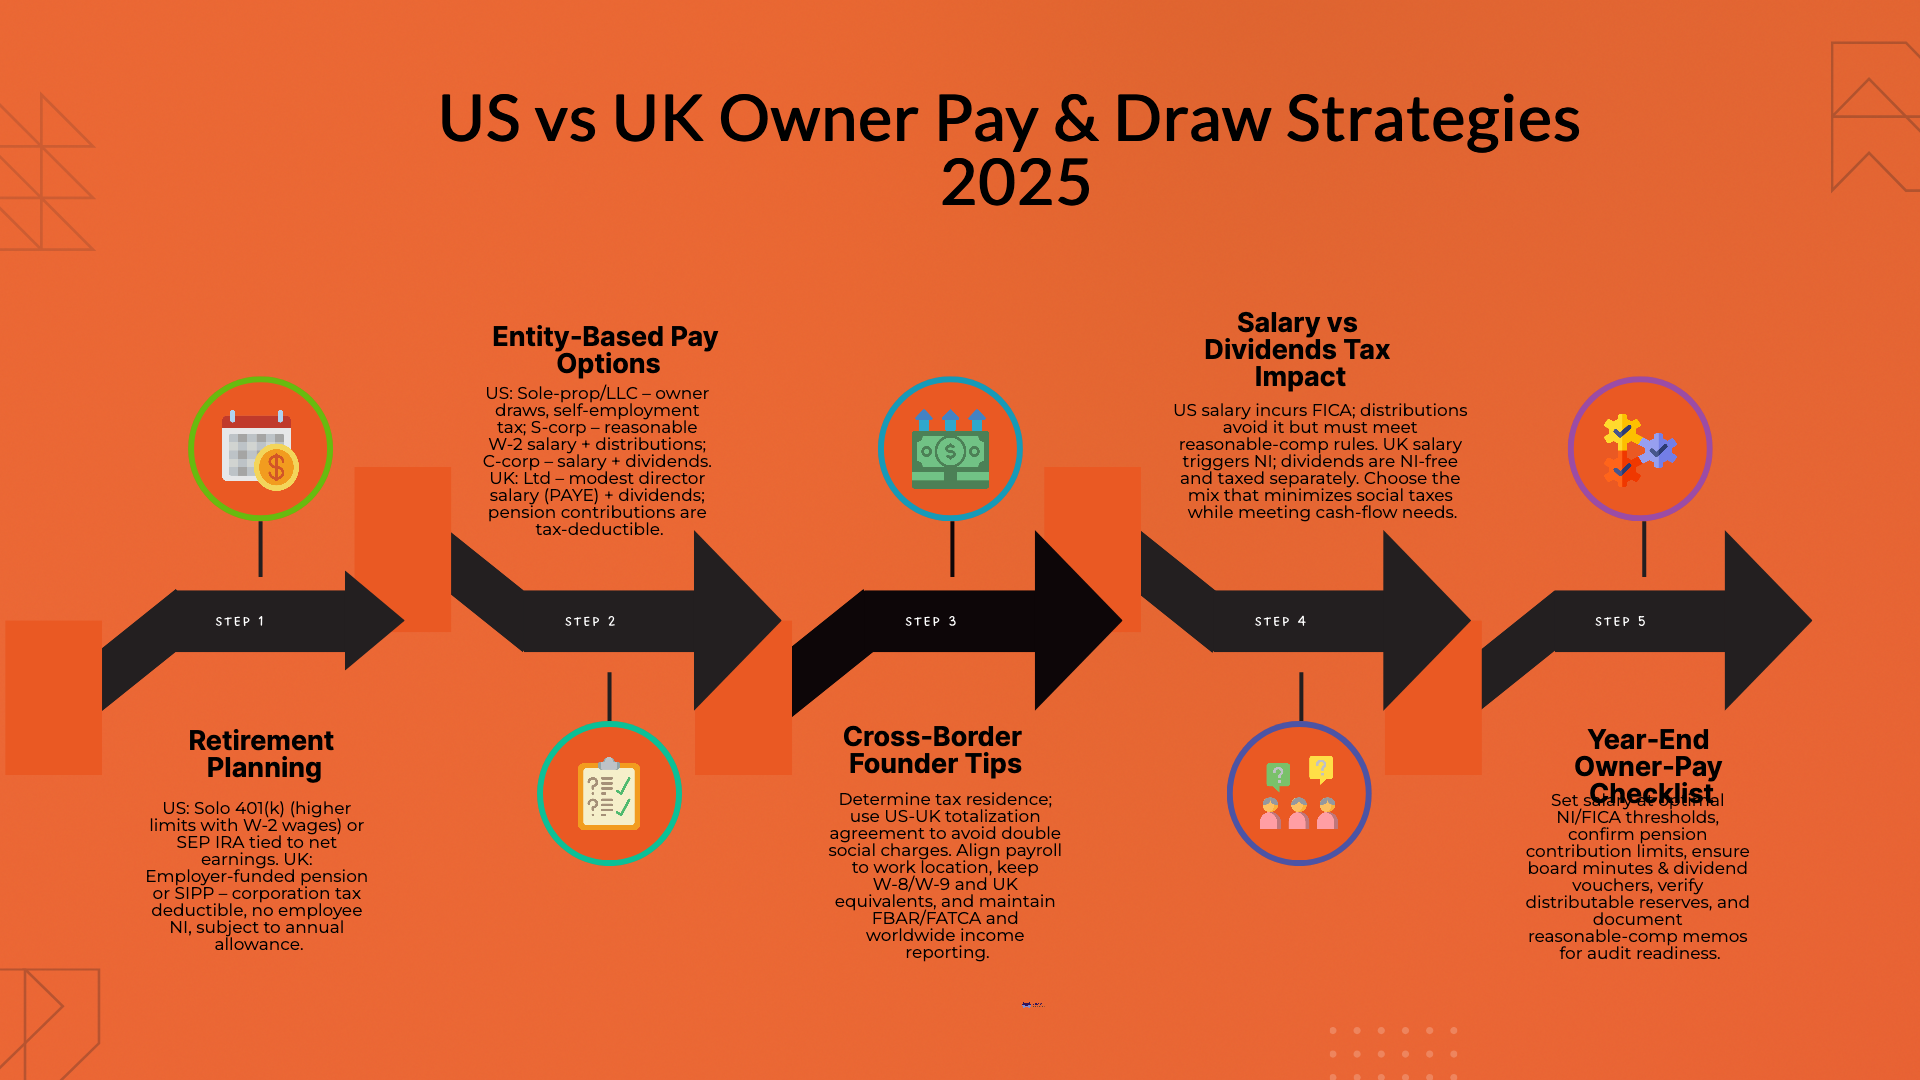

The salary vs dividends US vs UK decision comes down to one difference in design. In the US, an S corporation owner who works in the business must take reasonable wages first, and only profit paid out beyond that escapes payroll tax. In the UK, a limited company director usually takes a small salary near the National Insurance thresholds and draws the rest as dividends, which carry no National Insurance at all.
This guide compares salary vs dividends US vs UK for owner-managed companies using 2026 US figures and the UK 2026/27 rates published on GOV.UK, as of October 2026. The UK Budget is due on 28 October 2026, so treat every UK number below as current until the Budget says otherwise, and recheck before you act.
The way an owner takes money out depends first on the legal and tax form of the business. The table summarises the common setups.
| Jurisdiction | Entity | How owners usually take money | Social tax exposure |
|---|---|---|---|
| US | Sole proprietorship or single-member LLC (default) | Owner draws; no W-2 salary | Self-employment tax on net profit, whether drawn or left in the business |
| US | LLC or corporation taxed as an S corp | W-2 salary plus distributions | FICA on salary; none on distributions beyond reasonable pay |
| US | C corporation | W-2 salary plus dividends | FICA on salary; dividends taxed at corporate and shareholder level |
| UK | Private limited company | Director salary plus dividends | Class 1 NIC on salary; no NIC on dividends |
| UK | Sole trader | Drawings from profit | Income tax and self-employed NIC on profit |
An owner's draw from a US sole proprietorship is a movement of cash, so it does not change the tax bill. Tax follows the profit. If you are still weighing the US structures, our comparison of sole proprietorships and S corps covers the setup trade-offs, and the guide to making an S corp election on Form 2553 covers the filing itself.
A sole proprietor or default single-member LLC pays self-employment (SE) tax on net earnings. The IRS states that "the self-employment tax rate is 15.3%", made up of 12.4% for Social Security and 2.9% for Medicare. You owe it once net earnings reach $400, and you can deduct the employer-equivalent half when working out adjusted gross income.
The Social Security part stops at the annual wage base. For 2026, the IRS sets that base at $184,500 in Tax Topic 751. Medicare has no cap, and an extra 0.9% Additional Medicare Tax applies above $200,000 of wages or SE income for single filers and $250,000 for joint filers.
Before applying the rates, net profit is reduced by half of the combined SE tax rate under 26 U.S.C. 1402(a)(12). Half of 15.3% is 7.65%, so SE tax applies to 92.35% of net profit.
An S corporation changes the picture because the owner becomes an employee. The IRS says plainly that "S corporations must pay reasonable compensation to a shareholder-employee in return for services" before making non-wage distributions. Wages carry FICA at 7.65% for the employee and 7.65% for the company, up to the same $184,500 Social Security base. Distributions above reasonable pay are not wages, so no FICA applies to them, though all S corp profit still flows through to the owner's income tax return.
The IRS lists the factors used to judge whether pay is reasonable, including training and experience, duties and responsibilities, time and effort devoted to the business, what comparable businesses pay for similar services, and the use of a formula to set pay. Our detailed guide to reasonable compensation for S corp owners walks through how to document a figure that will hold up.
Two practical points sit next to the salary decision. Health insurance premiums the S corp pays for a more-than-2% shareholder are deductible by the company and reported as W-2 wages, but they are not subject to Social Security or Medicare tax when provided under a plan for employees. Distributions also reduce your stock basis, which you track on Form 7203 for S corp shareholder basis.
C corporation dividends come out of profit already taxed at the corporate level and are then taxed again to the shareholder. That double layer is why most small US owner-managers who want a salary and dividend split choose S corp status. A C corp can still make sense when profits are being reinvested.
All UK figures in this section are the 2026/27 rates (6 April 2026 to 5 April 2027) as published on GOV.UK, as of October 2026, before the 28 October 2026 Budget.
The income tax rates page sets the personal allowance at £12,570, the basic rate of 20% on £12,571 to £50,270, the higher rate of 40% on £50,271 to £125,140 and the additional rate of 45% above that. The allowance falls by £1 for every £2 of adjusted net income above £100,000. Scotland uses different income tax bands.
HMRC's 2026 to 2027 rates and thresholds for employers give these Class 1 figures:
| Class 1 NIC item (2026/27) | Annual figure | Rate |
|---|---|---|
| Lower earnings limit | £6,708 | 0% (builds State Pension entitlement) |
| Secondary threshold (employer) | £5,000 | Employer pays 15% above it |
| Primary threshold (employee) | £12,570 | Employee pays 8% above it |
| Upper earnings limit | £50,270 | Employee rate drops to 2% above it |
The low £5,000 secondary threshold means a director salary at the £12,570 personal allowance now triggers employer NIC. Employment Allowance, which can cut the employer bill by up to £10,500, does not help most one-person companies, because GOV.UK's eligibility guidance states: "If your company has only one director, they must not be the only employee liable for secondary Class 1 National Insurance."
Dividends are paid from profit after corporation tax. Per GOV.UK's tax on dividends page, each person has a £500 dividend allowance, and dividends above it are taxed at 10.75% in the basic rate band, 35.75% in the higher rate band and 39.35% in the additional rate band for 2026/27. Dividends sit on top of salary when working out which band they fall into, and they attract no National Insurance.
Corporation tax runs at 19% on profits of £50,000 or less and 25% on profits above £250,000, with marginal relief in between. A company also needs enough distributable reserves to pay a dividend, so keep board minutes and dividend vouchers for every payment.
The table pulls the two systems together for a profitable owner-managed company.
| Question | US (S corp) | UK (limited company) |
|---|---|---|
| Must the owner take a salary? | Yes, reasonable compensation for services | No legal minimum; usually a small salary for NIC records |
| Payroll tax on salary | FICA 15.3% combined up to $184,500, then 2.9% Medicare | Employer 15% above £5,000; employee 8% above £12,570, 2% above £50,270 |
| Payroll tax on profit taken beyond salary | None on distributions | None on dividends |
| Income tax on profit taken beyond salary | Ordinary rates on pass-through profit | Dividend rates of 10.75%, 35.75% or 39.35% after a £500 allowance |
| Company-level tax first | None for federal purposes (pass-through) | Corporation tax at 19% to 25% |
| Main risk | IRS reclassifying distributions as wages | Paying dividends without distributable reserves |
The US S corp saves payroll tax on the slice above reasonable wages but has no special income tax rate for that slice. The UK route runs dividends through corporation tax first and then applies lower dividend rates.
The figures below are illustrations only, using the rates cited above. They ignore state taxes, pensions and other income.
UK director, company profit of £50,000 before owner pay. Profit stays at or below £50,000 and the company has no associated companies, so the 19% small profits rate applies.
| Step | Option A: £12,570 salary plus dividends | Option B: all salary |
|---|---|---|
| Gross salary | £12,570.00 | £44,130.43 |
| Employer NIC at 15% above £5,000 | £1,135.50 | £5,869.56 |
| Taxable company profit | £36,294.50 | £0.00 |
| Corporation tax at 19% | £6,895.96 | £0.00 |
| Dividend paid | £29,398.54 | £0.00 |
| Employee NIC at 8% above £12,570 | £0.00 | £2,524.83 |
| Income tax on salary at 20% above £12,570 | £0.00 | £6,312.09 |
| Dividend tax at 10.75% above £500 | £3,106.59 | £0.00 |
| Owner keeps | £38,861.95 | £35,293.51 |
In this example the salary plus dividend mix leaves the director £3,568.44 better off. In Option B the salary is set so that salary plus employer NIC uses the full £50,000 (to the nearest penny).
US S corp owner, business profit of $150,000 before owner pay. Option A pays the whole profit out as salary: $150,000 ÷ 1.0765 = $139,340.46 of wages plus $10,659.55 employer FICA (to the nearest cent). The wages sit below the $184,500 base, so combined FICA is $139,340.46 × 15.3% = $21,319.09.
Option B pays a $90,000 reasonable salary and distributes the rest. Combined FICA is $90,000 × 15.3% = $13,770. After the $6,885 employer share, $53,115 is left for distributions with no payroll tax. Payroll tax falls by $7,549.09, provided $90,000 is genuinely reasonable pay for the owner's role. The S corp then adds payroll running costs and a separate business return, and the lower wage figure can also change your Section 199A deduction, so model income tax as well before switching.
Salary level drives retirement savings on both sides. In the US, Solo 401(k) employee deferrals and the employer contribution both depend on W-2 wages for an S corp owner, so a very low salary caps what you can put away. Our guide to Roth Solo 401(k) contribution limits explains how the limits stack, and SEP IRA vs SIMPLE IRA covers the simpler plans.
In the UK, many directors treat company pension contributions as a third extraction route alongside salary and dividends. The annual allowance and the company's own position limit how much makes sense, so agree the figure with your adviser before year-end.
Owners who live in one country and run a company in the other face both systems at once. Keep these checks on your list.
Is it better to take salary or dividends in the UK in 2026/27? For most single-director companies, a salary around the £12,570 personal allowance plus dividends still leaves more after tax than an all-salary approach, as the worked example shows. The gap depends on profit level and corporation tax rate, and the Budget on 28 October 2026 could change the rates.
Do S corp distributions count as salary in the US? No payroll tax applies to distributions that genuinely exceed reasonable compensation. If the owner's salary is too low for the work performed, the IRS can treat distributions as wages and assess FICA on them.
What is the 2026 Social Security wage base? For 2026, Social Security tax applies to the first $184,500 of combined wages and self-employment earnings. Medicare tax of 2.9% applies to all of it, with an extra 0.9% above $200,000 for single filers.
What are UK dividend tax rates for 2026/27? After the £500 dividend allowance, dividends are taxed at 10.75% in the basic rate band, 35.75% in the higher rate band and 39.35% in the additional rate band. These are the rates published before the 28 October 2026 Budget.
Madras Accountancy supports US and UK business owners and their CPA firms with bookkeeping, payroll records, tax preparation and planning work that feeds salary and dividend decisions. To talk through your own owner pay setup, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



