



Twelve states plus Washington, D.C. have an estate tax: Connecticut, Hawaii, Illinois, Maine, Maryland, Massachusetts, Minnesota, New York, Oregon, Rhode Island, Vermont and Washington. Five states have an inheritance tax: Kentucky, Maryland, Nebraska, New Jersey and Pennsylvania. Maryland has both. Every other state, 34 in all, has neither an estate tax nor an inheritance tax.
The federal estate tax still applies everywhere, but only to large estates. The federal basic exclusion amount is $15 million per person for 2026 and $15.48 million for 2027 (IRS Rev. Proc. 2026-35, IR-2026-133). State estate taxes often start far lower, which is why the state you live in, and where your property sits, can matter more than the federal rules for many families.
This guide covers:
Estate tax and inheritance tax both apply when someone dies, but they are charged on different people and work differently. Knowing which one applies in your state is the first step in any estate plan.
Definition: An estate tax is charged on the total value of a deceased person's estate before assets pass to heirs. The estate pays it, not the recipients.
How it works:
Federal exclusion:
Key point: Very few estates owe federal estate tax at these levels. Many more are exposed to state estate taxes, which can start at $1 million to $5 million depending on the state.
Definition: An inheritance tax is charged on the person who receives assets, not on the estate. Many beneficiaries do not expect it, so it is often a surprise.
How it works: The amount owed usually depends on:
Graduated rates: State inheritance tax rules usually favor close family:
States with an inheritance tax: Kentucky, Maryland, Nebraska, New Jersey and Pennsylvania. Iowa repealed its inheritance tax effective January 1, 2025, so it is no longer on the list.
Both taxes can apply: Maryland is the only state with both an estate tax and an inheritance tax, so an estate can be taxed first and some heirs taxed again.
Property location counts: A Florida resident (no estate or inheritance tax) who owns real estate in Oregon (an estate tax state) may still face Oregon estate tax on that property.
Relationship to the deceased counts: Inheritance tax rates often favor immediate family. A niece, friend or caregiver may owe more than a child would.
Gifting and trusts play a role: Lifetime gifts, irrevocable trusts and domicile planning can reduce or remove estate and inheritance taxes, but they work best when started early.
Estate and inheritance taxes are set state by state, on top of the federal estate tax. Most states charge neither. Here is the full breakdown.
These 34 states have neither tax, so assets can pass to heirs without a state-level death tax. Federal estate tax can still apply to very large estates.
Note: Having no estate or inheritance tax does not make a state low-tax overall. Income, property and sales taxes still differ widely.
Approximate 2026 exemptions are shown below. They come from a secondary source and change often, so treat them as approximate and check with the state before relying on them.
Oregon has the lowest threshold on this list, followed by Massachusetts. Both are far below the federal exclusion.
How much an heir owes in these states depends on:
Maryland is the only state with both an estate tax and an inheritance tax. If you live in Maryland or own property there, plan for both.
The federal basic exclusion amount is $15,000,000 per person for 2026, set by the One Big Beautiful Bill Act, and $15,480,000 for 2027 (Rev. Proc. 2026-35). Earlier versions of this guide warned that the exclusion would fall sharply after 2025. That drop did not happen, so plans built around a 2026 "sunset" are worth reviewing.
State exemptions vary widely and are often a fraction of the federal amount. Approximate 2026 examples:
Because these figures change and some are not indexed for inflation, confirm the current amount with the state's revenue department.
Some states offer credits or deductions that reduce estate tax. Looking at the federal and state rules together, along with any credits, helps keep the total bill down.
Estate and inheritance taxes are separate from income tax. Inheriting assets is generally not taxable income, but income those assets later produce, and withdrawals from inherited retirement accounts, can be. An estate planning attorney or CPA can help you plan for both.
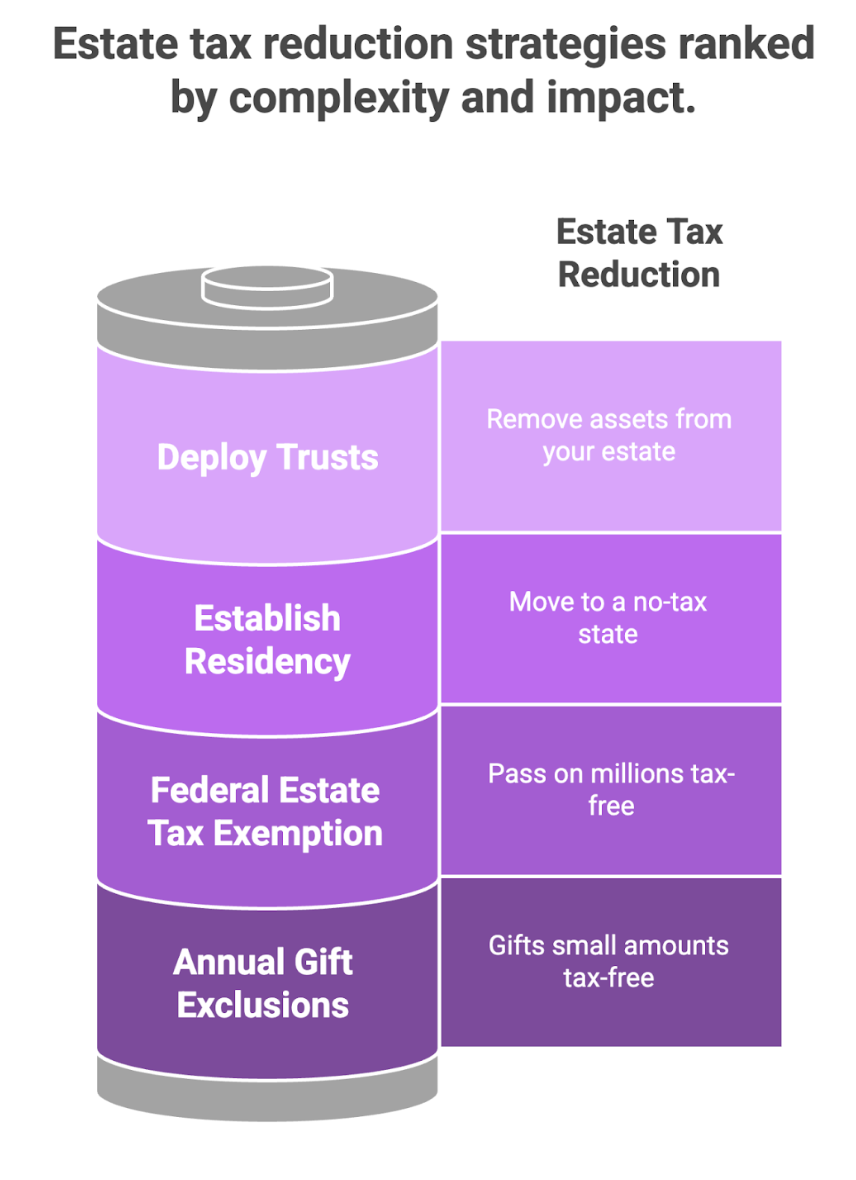
With planning, many families reduce or remove estate and inheritance taxes. Here are the main approaches for the 2026 and 2027 planning years.
Where you live, and where you are domiciled when you die, matters. States such as Florida, Texas and Nevada have no estate or inheritance tax. If your estate is also under the federal exclusion, it may owe no estate tax at all.
Owning a home there is not enough. To change domicile you generally need to show it:
High-tax states often review residency changes by wealthy taxpayers, so keep clear records.
For 2026 you can pass $15 million per person without federal estate or gift tax, rising to $15.48 million in 2027. Married couples can use roughly double that with portability.
Common approaches:
Remember that state estate taxes may still apply well below the federal exclusion, so plan for both.
The annual gift tax exclusion is $19,000 per recipient for 2026 and $20,000 for 2027.
That means:
For larger estates, trusts are a core tool. Three widely used types:
These trusts need legal and tax advice to set up correctly.
Estate law is state-specific and changes often. A good CPA or estate planning attorney will:
If you live in, or own property in, a state with a low estate tax threshold, planning matters even if your estate is far below the federal exclusion.
If you live in an estate tax or inheritance tax state, or own property in one, your estate may owe state tax even when no federal tax is due. Very large estates can owe both.
(Estate tax is charged on the total value of the estate before it is passed on. Figures are approximate; check with the state.)
Important: Some states have "cliff" rules, where an estate slightly above the exemption can lose the exemption entirely. Ask your advisor whether your state works this way.
(Charged on the recipient, based mainly on how closely related they were to the deceased.)
Only Maryland has both an estate tax and an inheritance tax.
If you are:
...then knowing where your assets are located and how each state taxes them can save your heirs a significant amount.
Look at the whole tax picture. Some states with no estate tax have high property or sales taxes. Others have lower income tax rates that help you during your lifetime.
Whether an estate tax return is needed depends on the value of the estate and the exemption that applies. A federal return (Form 706) is required for estates above the federal filing threshold, and is also used to elect portability for a surviving spouse. States have their own filing rules and thresholds.
State estate tax rules change often. Washington raised its exemption for deaths from July 1, 2026, and Iowa repealed its inheritance tax from 2025. Review your plan whenever your state changes its rules or you move.
Estate and inheritance taxes are often confused. Here are the most common mistakes.
They are not. Estate tax is paid by the estate before assets are distributed. Inheritance tax is paid by the person who receives the inheritance.
Some states have one, Maryland has both, and most have neither.
Only half true. The federal exclusion is $15 million per person for 2026, but state estate taxes often start much lower:
If you live in an estate tax state and own a home, retirement accounts and life insurance, your estate could owe state tax even if it does not feel large.
Not necessarily. Inheritance tax generally depends on where the deceased person lived or where the property is, not where the heir lives.
Example: You live in Florida but inherit from someone who lived in Pennsylvania. Pennsylvania inheritance tax may still apply.
Estate planning is not only about taxes. It also covers:
Modest estates benefit from trusts, beneficiary designations and good records, especially when property is held in more than one state.
It does not. States set their own death taxes, and these apply alongside federal law.
Most states have no estate or inheritance tax, and the federal exclusion is now $15 million per person for 2026 and $15.48 million for 2027. But 12 states plus D.C. still charge an estate tax, some starting near $1 million, and five states tax heirs directly.
Knowing where these taxes apply and how to structure your assets helps the people you care about receive more of what you have built.
At Madras Accountancy, we go beyond tax filing. We help you plan across estate, tax and business accounting so a state inheritance law or federal change does not catch you off guard.
Whether you are planning for your family or preparing your business for succession, we make sure your numbers support your plans.
Start a conversation with us at MadrasAccountancy.com for clear, practical advice.
For CPA firms: Madras Accountancy supports U.S. CPA firms with tax preparation and planning, including seasonal capacity for busy season. See our tax preparation and planning services.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



