

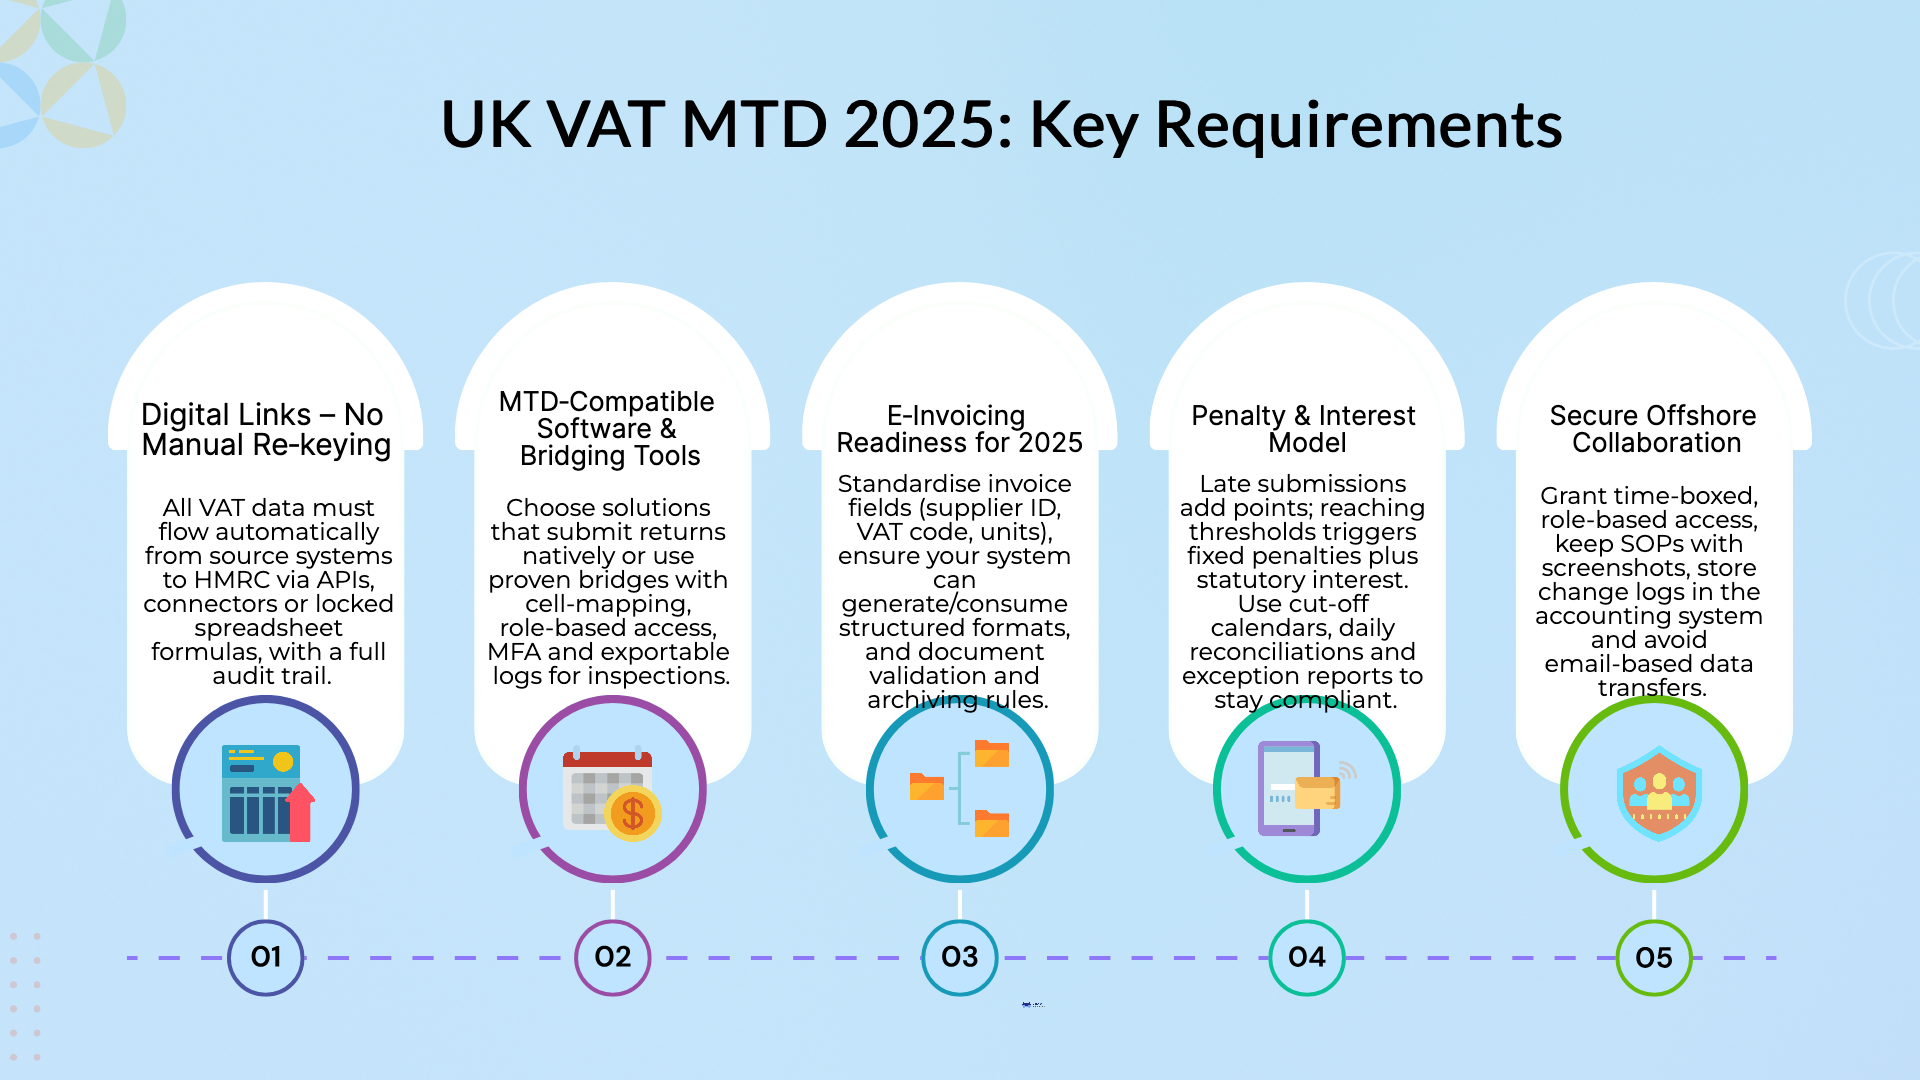

MTD for VAT digital links are the electronic transfers that carry VAT data from the software where a business keeps its records through to the return it files with HMRC. Once a figure is in your digital records, every later move of that figure must happen electronically, and HMRC treats copy and paste as a break in the chain.
This guide covers the MTD for VAT digital links rules as they stand in October 2026, for UK subsidiaries of US groups and for US businesses registered for UK VAT. It also covers the penalty regime for late returns and late payments, the decision to make e-invoicing mandatory for VAT invoices from 2029, and the Making Tax Digital for Income Tax rollout that began in April 2026.
Every VAT-registered business is inside Making Tax Digital for VAT. VAT Notice 700/22 states that the regime "requires all VAT-registered businesses to keep records digitally and file their VAT Returns using software." There is no turnover floor for the record-keeping rules once you are registered.
That matters for US companies. A business based outside the UK that supplies goods or services to the UK generally has to register regardless of turnover, while UK-established businesses register once taxable turnover passes £90,000 over a rolling 12 months. If your group is still deciding how to set up, our guide to expanding to the UK as a US company covers entity choice and registration, and our comparison of US sales tax and VAT explains why VAT records look so different from a US sales tax file.
Exemptions exist, and they are narrow. HMRC can exempt a business where digital record keeping is impractical because of age, disability or location, where the business is subject to an insolvency procedure, or on certain religious grounds. The notice says an exemption will not be granted solely because of the extra effort, time or cost of moving to software.
The rule sits in paragraph 3.2.1 of Notice 700/22. The core sentence is: "Once data has been entered into software that you use to keep and maintain your electronic account, any further transfer, recapture or modification of that data must be done using digital links."
HMRC defines a digital link as a transfer or exchange of data that is made, or can be made, electronically between software programs, products or applications, without manual intervention such as copying information over by hand. The notice lists methods HMRC accepts, and says the list is not exhaustive:
The notice is just as specific about what fails: "HMRC does not consider the use of 'cut and paste' or 'copy and paste' to select and move information, as a digital link."
Two points are easy to miss. An emailed CSV that is imported into the next system is acceptable, so a group that exports a trial balance from its ERP and imports it into a VAT tool has not broken the chain, provided nobody retypes or pastes values along the way. Retyping a subtotal from one spreadsheet into another does break it, even if the person is careful and the number is right.
The digital link requirement starts at the first software that holds your "electronic account," which is the set of VAT records the regulations require you to keep digitally. If a separate invoicing tool or ERP is outside that electronic account, the notice says no digital link is needed when data moves from it into the electronic account. The section 5 examples in the notice show several businesses keying sales or purchase figures into their software by hand at the start, with the mandatory links beginning once the data sits in the API-enabled software or spreadsheet.
The journey ends with submission. Paragraph 3.2.2 says submission to HMRC "must always be through an API," either through commercial software or through bridging software that connects a spreadsheet to HMRC's systems.
Partial exemption, capital goods scheme and road fuel scale charge adjustments often live in separate workbooks. Paragraph 3.4 allows that: the calculation can sit outside functional compatible software, and digital links are not needed for the inputs to that calculation. The total of each type of adjustment still has to be recorded in the software as its own line. A US controller who books a quarter-end partial exemption journal can therefore key the final adjustment total by hand, while the sales and purchase data feeding the return must stay linked.
The table below maps three common setups to where the links are mandatory and where errors tend to creep in.
| Setup | How data reaches HMRC | Where links are mandatory | Common failure point |
|---|---|---|---|
| Full accounting software with MTD filing built in | Ledger prepares and submits the return through HMRC's API | Inside the ledger and between any feeder apps that form part of the electronic account | Manual journals that restate VAT box totals without an audit trail |
| ERP plus API-enabled spreadsheet | ERP export is imported into a VAT workbook that submits directly | ERP export to workbook, and every formula between workbook tabs | A pasted subtotal or a hard-coded override in a VAT box cell |
| ERP plus bridging software | ERP report feeds a locked spreadsheet; a bridge maps cells to the nine VAT boxes and files | ERP to spreadsheet, spreadsheet to bridge | Bridge mapped to the wrong cell after someone inserts a row |
If the ledger is still being chosen, our comparisons of Xero and Sage and of QuickBooks and Xero for multi-entity groups cover how each handles consolidation alongside local VAT filing. For groups pulling data between systems, our guide to API integration for accounting workflows explains how connectors replace exports and uploads.
Walk the data from source to submission once a year and after any system change. For each hop, record the systems, the method (API, import, formula), the owner and a screenshot. Then test three things:
Our 5-day monthly close checklist includes reconciliation steps that pair well with a VAT control account review.
For VAT accounting periods starting on or after 1 January 2023, the old default surcharge was replaced by separate late submission penalties, late payment penalties and late payment interest. The return and payment are usually due one calendar month and 7 days after the end of the accounting period.
HMRC's late submission penalty guidance explains that each late return earns one point until you reach a threshold set by your filing frequency. At the threshold "you'll receive a £200 penalty," and a further £200 penalty for each later late return while you stay at the threshold. The rule applies to nil and repayment returns too.
| Filing frequency | Penalty point threshold | Period of compliance to clear points at threshold | On-time returns needed |
|---|---|---|---|
| Annual | 2 | 24 months | 2 |
| Quarterly | 4 | 12 months | 4 |
| Monthly | 5 | 6 months | 6 |
Points below the threshold expire on their own, usually after 24 months. Once you are at the threshold, HMRC's guidance on removing points says you clear them only by filing every return on time for the period of compliance shown above and by submitting all outstanding returns for the previous 24 months.
The late payment penalty rules were made more expensive in 2025. HMRC's guidance sets them out as follows:
Late payment interest runs separately from the first day the payment is overdue. HMRC's interest rates page sets it at Bank of England base rate plus 4% from 6 April 2025, and lists the late payment rate as 7.75% from 9 January 2026. As of October 2026 that is still the listed rate, with Bank Rate at 3.75%. The rate moves when the base rate moves, so check the page for the current figure.
A Time to Pay arrangement agreed with HMRC can mean lower or no late payment penalties, and the guidance encourages businesses to ask before day 15 where they can.
A UK subsidiary files its quarterly return on time showing £24,000 of VAT due, then pays the full amount 45 days after the due date. Following HMRC's method, and using the 7.75% interest rate listed as of October 2026:
| Charge | Calculation | Amount |
|---|---|---|
| First late payment penalty | 3% × £24,000 at day 15, plus 3% × £24,000 at day 30 | £1,440.00 |
| Second late payment penalty | £24,000 × 10% × 15 days (day 31 to day 45) ÷ 365 | £98.63 |
| Late payment interest | £24,000 × 7.75% × 45 days ÷ 365 | £229.32 |
| Total cost of paying 45 days late | £1,767.95 |
Most of the cost lands on day 16 and day 31. A payment workflow that releases VAT a few days before the deadline, with an alert to the US treasury team that funds the UK account, avoids nearly all of it. If HMRC has already raised questions about filings, our guide on how to handle an HMRC tax investigation sets out what to expect.
E-invoicing has moved from consultation to a firm commitment. HMRC and the Department for Business and Trade consulted from 13 February 2025, and the consultation response confirms that "as announced at Budget 2025, the UK will introduce mandatory e-invoicing for all VAT invoices from 2029."
What the response settles so far:
The exact start date within 2029, the technical standard and any phasing will come from that roadmap. For now, the useful preparation is data quality. Make sure supplier and customer records hold valid VAT numbers and addresses, that each item maps to a VAT code automatically, and that your invoicing system can produce and read structured invoices. Public bodies covered by UK public procurement rules already have to accept e-invoices that comply with the BS EN 16931 standard, so suppliers to the UK public sector can test there first. Teams already automating their payables can build on that work; our guide to automated accounts payable covers capture and approval workflows that will feed an e-invoicing setup.
Making Tax Digital now extends beyond VAT. HMRC's Making Tax Digital for Income Tax guidance applies to sole traders and landlords registered for Self Assessment with self-employment or property income above a qualifying income threshold. As of October 2026, the thresholds are:
| Qualifying income in tax year | Threshold | Must use MTD for Income Tax from |
|---|---|---|
| 2024 to 2025 | Over £50,000 | 6 April 2026 |
| 2025 to 2026 | Over £30,000 | 6 April 2027 |
| 2026 to 2027 | Over £20,000 | 6 April 2028 |
Partnerships will follow on a timeline HMRC has yet to set. Companies are outside this regime, so a UK limited company subsidiary is unaffected. It does reach US citizens living in the UK who run a sole trade or let property there, and US founders who own UK rental property in their own names. Our article on US and UK owner pay strategies covers how those individuals are taxed on both sides.
Is emailing a CSV file a valid digital link for MTD for VAT? Yes. Notice 700/22 lists emailing a spreadsheet of digital records for import into another product, and CSV import and export, as accepted digital links. The chain breaks only if someone retypes or copies and pastes the figures after the file arrives.
Can I still use spreadsheets for MTD for VAT? Yes. A spreadsheet can be part of functional compatible software when it is combined with bridging software, or it can be API-enabled and submit directly. Links between cells and tabs must be formulas, and the submission must go through HMRC's API.
How many penalty points does a quarterly VAT filer get before a fine? The threshold for quarterly filers is 4 points. The fourth late return triggers a £200 penalty, and each later late return while at the threshold triggers another £200.
When does UK e-invoicing become mandatory? The government has committed to mandatory e-invoicing for all VAT invoices from 2029. As of October 2026, the implementation roadmap, including the start date within that year and the standards, is due at Budget 2026 on 28 October 2026.
Does Making Tax Digital for Income Tax apply to UK companies? No. It applies to sole traders and landlords with qualifying income over the thresholds above, starting with those over £50,000 from 6 April 2026. Companies continue to file corporation tax returns outside this regime.
Madras Accountancy supports US businesses and CPA firms with bookkeeping, reconciliations, close support and reporting, including work for groups with international operations. If you would like help organising the records that sit behind your UK VAT filings, contact our team to talk through your setup.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



