


Understanding 1099 employees starts with the name itself. "1099 employee" is everyday shorthand for an independent contractor, a self-employed person paid for services and reported on Form 1099-NEC instead of a W-2. Under tax law the phrase is a contradiction: a worker is either an employee or a contractor, and the facts of the relationship decide which, not the form the business chooses to issue.
That matters to both sides. The business that gets it wrong owes back payroll taxes. The worker who is truly self-employed owes self-employment tax and quarterly estimates, with nobody withholding anything. And for payments made in 2026, the federal reporting threshold for Form 1099-NEC rose from $600 to $2,000, which changes who receives a form at all.
An independent contractor runs their own business and sells a result to clients. They decide how the work gets done, supply their own tools, can work for others, and carry the risk of profit or loss. A freelance designer, an IT consultant billing several companies, a delivery driver on an app and a bookkeeper with her own practice can all be contractors.
What makes someone a contractor is the working relationship. A signed "independent contractor agreement" helps document intent, but the IRS and the courts look past it to how the work actually happens.
Three different tests can apply to the same worker, and a business has to pass all that are relevant.
IRS common-law test. The IRS groups the evidence into behavioral control (who directs how the work is done, including training and instructions), financial control (who invests in equipment, who bears unreimbursed expenses, how pay is structured) and the type of relationship (benefits, permanency, whether the work is a key part of the business). No single factor decides it.

Department of Labor test (wage and hour law). Under the Fair Labor Standards Act the question is whether the worker is economically dependent on the business or in business for themselves. The DOL stopped enforcing its 2024 rule in May 2025, and in February 2026 it proposed a replacement rule that puts the most weight on two core factors: control over the work and the worker's opportunity for profit or loss. Check the Federal Register for whether that rule has been finalized before relying on it.
State tests. Several states use a stricter ABC test for wage, unemployment or both. California's version is the best known; see our AB5 worker classification guide.
For a side-by-side of the two statuses, read 1099 vs W-2 employees: key differences and how to choose. If you are working through a specific hire, our step-by-step on how to classify workers the right way applies the factors to real fact patterns.
| Question | Points toward contractor | Points toward employee |
|---|---|---|
| Who sets the hours and method? | The worker | The business |
| Who supplies tools and equipment? | The worker | The business |
| How is pay set? | Per project or invoice | Hourly or salary on a payroll schedule |
| Can the worker serve other clients? | Yes, and does | No, or rarely in practice |
| Can the worker make or lose money? | Yes, through pricing and expenses | No, pay is fixed |
| Is the relationship open-ended? | No, tied to projects | Yes, indefinite |
Collect a Form W-9 before the first payment. It gives you the contractor's legal name, tax classification and taxpayer identification number. If a payee will not provide a TIN and the payment is reportable, you must apply backup withholding at 24%, explained in our article on how backup withholding works.
Know the new threshold. The One Big Beautiful Bill Act (P.L. 119-21) raised the Form 1099-NEC and 1099-MISC reporting threshold to $2,000 for payments made after December 31, 2025. The IRS 2026 instructions confirm the $2,000 figure for nonemployee compensation and note that it may be adjusted for inflation starting in 2027. The $600 threshold still applies to gross proceeds paid to attorneys reported on Form 1099-MISC. Our 2026 1099 reporting threshold explainer covers every form affected.
Worked example: in 2026 you pay a photographer $1,800 and a web developer $2,400, both by check. Only the developer gets a 1099-NEC. The photographer still owes tax on the $1,800; the lower threshold only removes your filing duty.
Watch how you paid. Payments made by credit card or through a third-party network such as PayPal are reported by the payment processor on Form 1099-K, not by you on 1099-NEC. OBBBA also restored the 1099-K threshold to more than $20,000 and more than 200 transactions; see our note on the Form 1099-K reporting threshold.
File on time. Form 1099-NEC goes to both the contractor and the IRS by January 31. For 2026 payments, January 31, 2027 is a Sunday, so the deadline moves to Monday, February 1, 2027. If you file 10 or more information returns of any type in total, you must e-file. Full filing mechanics are in our guide to IRS 1099-MISC and 1099-NEC filing requirements.
Know the penalties. For returns due in 2026, the IRS penalty schedule runs $60 per form if corrected within 30 days, $130 if filed by August 1, and $340 after that, with $680 per form and no annual cap for intentional disregard. The amounts are adjusted for inflation each year.
No one withholds tax from a contractor's pay, so the worker handles three things.
Self-employment tax. Contractors pay both halves of Social Security and Medicare: 15.3% in total, made up of 12.4% Social Security and 2.9% Medicare. It applies once net earnings from self-employment reach $400. The tax is figured on 92.35% of net profit, the Social Security part stops at the 2026 wage base of $184,500, and an extra 0.9% Medicare tax applies above $200,000 for single filers. The IRS self-employment tax page has the details.
Worked example: a consultant with $80,000 of net profit has $73,880 subject to SE tax (80,000 × 92.35%). At 15.3%, the SE tax is $11,303.64. Half of that, $5,651.82, is deductible in computing adjusted gross income. Income tax is then calculated on top.
Income tax and quarterly estimates. For the 2026 tax year, estimated payments are due April 15, June 15 and September 15, 2026, and January 15, 2027. Our quarterly estimated tax payments guide shows how to size each one, and how much to set aside for taxes on 1099 income gives a simple percentage method.
Deductions. Contractors deduct ordinary and necessary business expenses on Schedule C, and many qualify for the 20% qualified business income deduction, which OBBBA made permanent. See our Section 199A deduction guide and the list of best tax deductions for 1099 contractors.
A contractor who receives no 1099 at all, which is now more common under the $2,000 threshold, still reports every dollar of business income.
There is no federal limit. A contractor can bill 10 hours one week and 70 the next, because the FLSA's minimum wage and overtime rules apply to employees, not to people in business for themselves.
The hours question becomes a classification issue when the business controls the schedule. Requiring set shifts, daily check-ins, or a 40-hour week at your office looks like behavioral control. A contract that defines deliverables and deadlines, and leaves the schedule to the worker, is consistent with contractor status. Long hours for a single client over several years also weakens the "independent business" picture, since the worker is unlikely to be serving others.
Contractors set their own rates, choose clients and deduct business costs that employees cannot. They also give up employer-paid payroll tax, health coverage, retirement matching, unemployment insurance and workers' compensation. A contractor earning the same gross as an employee needs a higher rate to come out even, largely because of the employer half of FICA and benefits.
Self-employed people can build their own retirement savings, often with larger limits than a workplace plan allows; a Solo 401(k) or SEP IRA are the usual options.

A written agreement will not save a relationship that fails the tests above, but a good one records facts that support contractor status and avoids clauses that undercut it. Include:
Leave out employee-style terms: required office hours, mandatory training, performance reviews, and eligibility for your benefit plans. Keep the signed W-9, the agreement, invoices and proof of payment together for each contractor for at least four years, which covers the period the IRS generally uses for employment tax records.
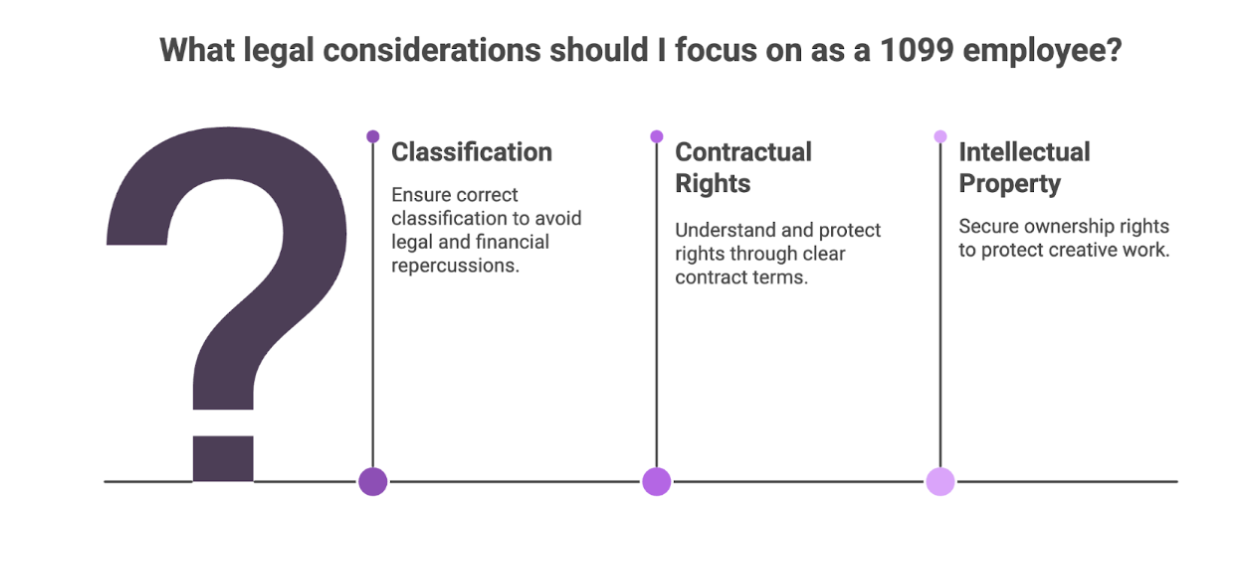
If the IRS reclassifies a worker, the business owes the employment taxes it should have paid. Where the error was not intentional, Section 3509 sets reduced rates: 1.5% of wages for the income tax that should have been withheld and 20% of the employee's share of FICA, plus the full employer share. The rates double to 3% and 40% if the business also failed to file 1099s. Penalties and interest come on top, along with state unemployment and workers' compensation exposure.
Two relief routes exist. Section 530 relief can shield a business that had a reasonable basis for its treatment, filed all required 1099s and treated similar workers consistently. The Voluntary Classification Settlement Program, filed on Form 8952, lets a business that reclassifies workers going forward pay 10% of the employment tax liability computed under Section 3509 for the most recent tax year, with no interest or penalties.
When the answer is unclear, either the business or the worker can file Form SS-8 to ask the IRS for a determination. Responses take months, so it is a poor tool for a hire you need to make next week.
Is a 1099 employee entitled to overtime? Not if the worker is genuinely independent, because the FLSA's overtime rules cover employees. If the relationship fails the DOL or state test, the worker is an employee and back overtime can be owed regardless of what the contract says.
Do I need to send a 1099-NEC if I paid a contractor $1,500 in 2026? No federal 1099-NEC is required for payments under $2,000 made in 2026. Some states set their own information-reporting rules, so check your state's requirements before skipping a form.
Can a business switch a worker from W-2 to 1099? Only if the job itself changes so the worker truly controls the work. Moving the same person doing the same tasks from payroll to a 1099 is one of the patterns auditors look for.
Do corporations get a 1099-NEC? Generally no. Payments to C and S corporations are exempt from 1099-NEC reporting, with exceptions such as fees paid to a law firm for legal services. The W-9 tells you how the payee is classified.
Can one person receive both a W-2 and a 1099 from the same company? It happens, but only when the contract work is clearly separate from the employee's regular job. Paying an employee on a 1099 for extra hours in the same role is treated as wages.
Madras Accountancy helps US businesses and CPA firms collect W-9s, track contractor payments against the $2,000 threshold, and file 1099s on time; our payroll and 1099 outsourcing overview explains how that works. Contact our team to set up contractor reporting before January.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



