
If you hold a taxable brokerage account, the tax document you get each February is usually called a "1099 Composite" or "Consolidated Form 1099." So what is a 1099 composite? It is a single statement from your broker that combines several separate IRS information returns, typically Form 1099-DIV, 1099-INT, 1099-B and 1099-MISC, plus a supplemental section the IRS never sees. Each piece is reported to the IRS separately under your Social Security number, so every figure on it has to land somewhere on your Form 1040.
The composite format exists for convenience. It doesn't change any tax rule, and it doesn't make the income any less visible to the IRS matching system.
The exact layout varies by broker (Schwab, Fidelity, Vanguard, E*Trade, Robinhood and others each use their own design), but the building blocks are the same IRS forms.
| Section | What it reports | Where it usually goes on your return |
|---|---|---|
| 1099-DIV | Ordinary dividends (box 1a), qualified dividends (1b), capital gain distributions (2a), nondividend distributions (3), Section 199A dividends (5), foreign tax paid (7) | Form 1040 lines 3a/3b, Schedule B, Schedule D line 13, Form 8995, Form 1116 or Schedule 3 |
| 1099-INT | Interest (box 1), US Treasury interest (box 3), tax-exempt interest (8), bond premium adjustments | Form 1040 lines 2a/2b, Schedule B |
| 1099-OID | Original issue discount on bonds and CDs | Schedule B |
| 1099-B | Proceeds, cost basis, dates, wash sale loss disallowed (box 1g) for each sale | Form 8949 and Schedule D |
| 1099-MISC | Royalties, substitute payments in lieu of dividends, other income | Schedule E or Schedule 1, depending on the box |
| Supplemental information | Detail on uncovered lots, fees, accrued interest, state-by-state muni income | Not filed with the IRS; used to prepare the return |
Two practical points. First, if a section shows zero, the broker usually still prints the page, so don't assume a blank page means a missing form. Second, the supplemental pages often hold the most useful numbers, such as basis for shares the broker was not required to report and the state breakdown of tax-exempt interest.
Brokers must furnish Form 1099-B by February 15. Under the IRS General Instructions for Certain Information Returns, that later due date also applies to statements furnished as part of a consolidated reporting statement, which is why your 1099-DIV and 1099-INT arrive with the 1099-B in mid-February instead of January 31. When February 15 falls on a weekend or holiday the date moves to the next business day; 2025 statements were due February 17, 2026.
The extra two weeks lets brokers wait for mutual funds and REITs to reclassify distributions. That reclassification is also the main reason corrected composites go out in late February and March.
Box 1a is total ordinary dividends. Box 1b is the portion that qualifies for the 0%, 15% or 20% long-term capital gain rates. Box 1b is already inside box 1a, so you never add them together.
A dividend only counts as qualified if you held the stock more than 60 days during the 121-day window starting 60 days before the ex-dividend date. Brokers apply this test to the extent they can, but if you trade around dividend dates, check it yourself. The Form 1099-DIV instructions set out the holding period rules, including the longer 91-day test for some preferred stock.
Box 2a capital gain distributions from mutual funds go straight to Schedule D line 13. Box 3 nondividend distributions are a return of capital: they aren't taxed when received, but they reduce your basis in the shares. Box 5 Section 199A dividends (mostly from REITs) can qualify for the 20% qualified business income deduction, which the One Big Beautiful Bill Act made permanent. Our Section 199A deduction guide covers how that deduction is computed.
Taxable interest goes on Form 1040 line 2b. US Treasury interest in box 3 is federally taxable but exempt from state income tax, which many self-prepared returns miss on the state side. Tax-exempt municipal bond interest is reported on line 2a. It is free of federal income tax, yet it still counts toward the taxable portion of Social Security benefits.
The 1099-B section lists every sale with proceeds, acquisition date, sale date, cost basis and gain or loss, split into short-term and long-term and then into "covered" and "noncovered" lots.
Covered securities are those where the broker must report your basis to the IRS. Per the Form 1099-B instructions, stock bought for cash after 2010 is generally covered, average-basis shares such as mutual funds after 2011, and most bonds and options after 2013 (some complex debt after 2015). For older or transferred-in shares, the broker may report proceeds with no basis at all. If you leave basis blank, the IRS treats basis as zero and the whole sale price as gain.
Box 1g shows wash sale losses the broker disallowed. Brokers only track wash sales within the same account and identical CUSIP; a repurchase in your IRA or at another broker is still a wash sale, but it won't be on the form. Our explainer on the wash sale rule and tax-loss harvesting walks through those cross-account traps.
This usually holds substitute payments in lieu of dividends (when your shares were lent out in a margin account) and occasional royalties or settlement income. Substitute payments are ordinary income, never qualified dividends, which surprises investors who see a lower rate on their regular dividends. For how 1099-MISC works for business payers, see our 1099-NEC and 1099-MISC filing requirements guide.
Here is the order we follow when preparing a return from a composite.
Priya, a single filer, receives one composite showing $2,140 of ordinary dividends (box 1a), of which $1,780 is qualified (1b), $410 of interest, $95 of foreign tax paid and two stock sales.
That second sale is the one that typically triggers an IRS notice when filed wrong.
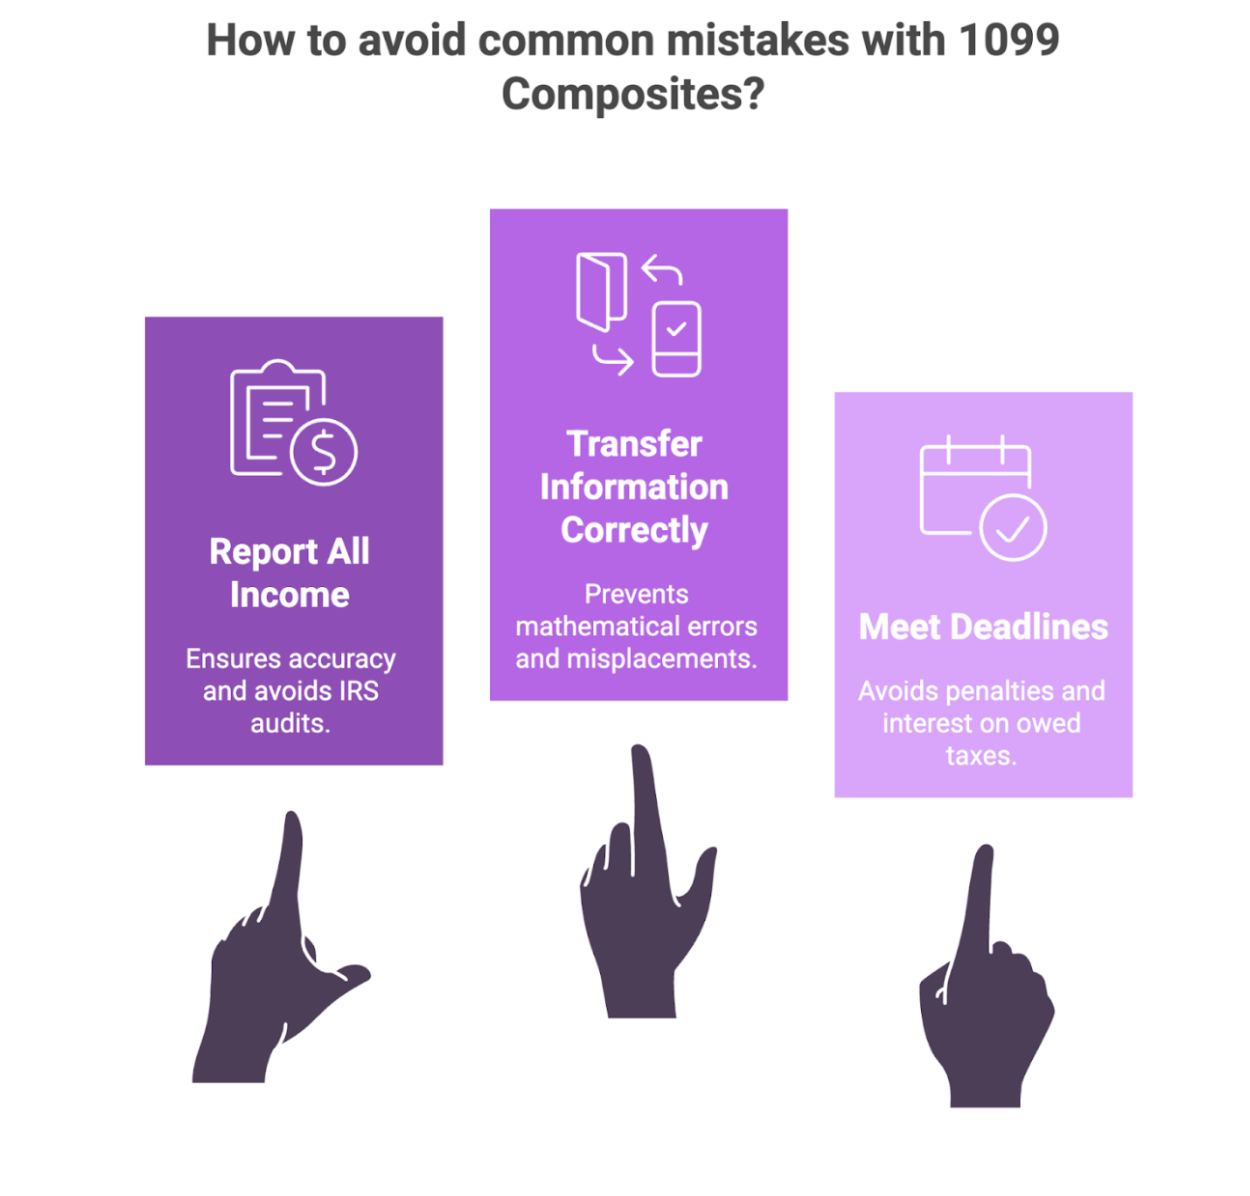
A mismatch between your return and the composite is the most common trigger for an automated underreporting notice. If one arrives, our guide to the IRS CP2000 notice explains how to respond.
Starting with 2025 transactions, brokers report digital asset sales on the new Form 1099-DA rather than Form 1099-B, and basis reporting begins for covered digital assets acquired from 2026 onward. Some platforms that also hold securities include the 1099-DA alongside the composite; others send it separately. Our Form 1099-DA guide covers the new box layout.
Most composites include a state withholding line and, in the supplemental pages, a state-by-state split of municipal bond interest. In most states, muni interest from your home state is exempt, while interest from other states' bonds is taxable. Mutual fund supplements also list the percentage of income from US government obligations, which many states let you subtract. These numbers rarely appear on the IRS pages, so preparers who skip the supplement routinely overpay state tax for clients.
Yes. Brokers use "composite," "consolidated" and "tax reporting statement" interchangeably. The IRS has no form called a 1099 Composite; it is a packaging format for several standard 1099s.
Usually yes, if the account paid at least $10 of dividends or interest. Brokers often send one even when every section is below the reporting threshold, and some only post it online.
If the corrected form changes your income or tax, file Form 1040-X. Small changes still create a mismatch in IRS records, so it is better to amend than to wait for a notice.
Not necessarily. Losses on the 1099-B can offset gains, and up to $3,000 of net capital loss ($1,500 if married filing separately) can offset ordinary income each year, with the rest carried forward. If large gains or dividends show up mid-year, quarterly estimated tax payments help avoid an underpayment penalty.
Only for covered sales with basis reported to the IRS and no adjustments. Sales with wash sale adjustments, missing basis or other corrections need Form 8949 detail, though many preparers attach the broker statement instead of retyping every line.
For CPA firms, composites are high-volume and error-prone: 40-page statements, corrected versions in March, and noncovered basis that needs research. Madras Accountancy's offshore tax preparation team prepares 1040s with investment schedules under your firm's review, so your staff spends time on judgment calls instead of data entry. Talk to our team about busy-season capacity.
Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.
The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.
Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.