



So, what is the tax on bonus payments in 2026? For federal income tax withholding, most employers take a flat 22% from a bonus paid separately from regular wages, and 37% on any bonus dollars above $1 million in the calendar year. Social Security (6.2%) and Medicare (1.45%) come out on top of that, plus state tax where it applies. That withholding is a prepayment. The tax you actually owe on the bonus is figured on your Form 1040 at your ordinary income tax rates, the same rates that apply to your salary.
The gap between what's withheld and what's owed is the source of most confusion. Employees see 30% to 40% missing from a bonus check and assume bonuses carry a special tax. They don't. Employers, for their part, need to pick a withholding method, apply the FICA wage limits correctly and report the bonus on the W-2.
No. A bonus is taxable wages, reported in Box 1 of Form W-2 alongside salary. The difference is in withholding. The IRS treats bonuses, commissions, severance, back pay and similar payments as supplemental wages, and IRS Publication 15 (Circular E) gives employers special methods for withholding on them. Our deeper piece on how supplemental wage withholding works walks through the payroll mechanics step by step.
Once the year closes, your bonus is simply part of your wages. If your total taxable income lands in the 12% bracket, the bonus is taxed at 12%, regardless of the 22% withheld.
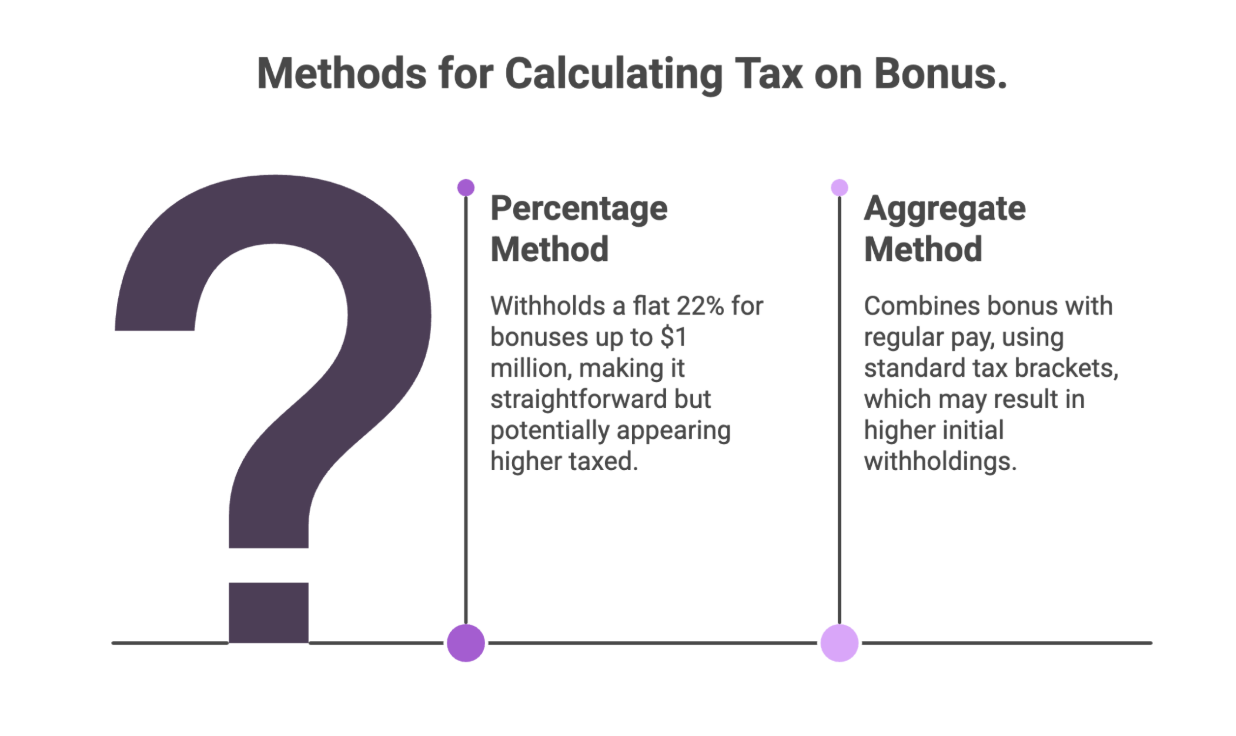
When the bonus is paid separately, or is identified separately on the pay stub, the employer can withhold a flat 22%. Pub 15 says no other percentage is allowed: an employee cannot ask for 15% or 30% on the flat-rate method. The employer can use this method only if it withheld income tax from the employee's regular wages in the current or prior calendar year.
The employer adds the bonus to the regular wages for the pay period, computes withholding on the combined amount as if it were a single regular paycheck, then subtracts the tax already withheld from the regular wages. Because payroll software annualizes that bigger paycheck, the aggregate method often withholds more than 22% on the bonus portion. A $3,000 biweekly paycheck plus a $10,000 bonus looks to the withholding tables like a $338,000 annual salary for that one pay period.
Once an employee's supplemental wages for the calendar year pass $1 million, the excess must be withheld at 37%, regardless of the employee's Form W-4 or the method used for the first $1 million. Supplemental wages from all businesses under common control count toward the $1 million.
| Withholding item | 2026 rule | Applies to |
|---|---|---|
| Federal income tax, flat method | 22% | Supplemental wages up to $1 million |
| Federal income tax, mandatory | 37% | Supplemental wages above $1 million in the year |
| Federal income tax, aggregate method | Regular W-4 tables on combined pay | Any amount up to $1 million |
| Social Security (employee) | 6.2% | Wages up to $184,500 |
| Medicare (employee) | 1.45% | All wages |
| Additional Medicare Tax | 0.9% | Wages above $200,000 from one employer |
| State income tax | Varies by state | Depends on the state's own supplemental rules |
The federal supplemental rate is still 22% for 2026, with 37% above $1 million. Those rates are tied to the 22% and 37% individual brackets created in 2017 and scheduled to expire after 2025. The One Big Beautiful Bill Act (P.L. 119-21, signed July 4, 2025) made the individual rates permanent, and the 2026 edition of Pub 15 confirms the supplemental rate remains 22%.
What the bill did add is a pair of temporary deductions that people sometimes confuse with bonuses:
Both deductions run for 2025 through 2028 and phase out at higher incomes. The IRS overview of the new deductions covers eligibility, and we explain the employer reporting side in no tax on tips and overtime in 2026. One employer-side point: a nondiscretionary bonus (one promised for hitting a target) must be included in a nonexempt worker's regular rate when computing FLSA overtime, which can increase the overtime premium for that period.
Assume a $10,000 bonus paid separately in 2026 under the flat method, to an employee who has not reached the Social Security wage base:
| Item | Rate | Amount |
|---|---|---|
| Gross bonus | $10,000 | |
| Federal income tax withheld | 22% | $2,200 |
| Social Security | 6.2% | $620 |
| Medicare | 1.45% | $145 |
| Net before state tax | $7,035 | |
| Example state withholding (hypothetical 5%) | 5% | $500 |
| Net check | $6,535 |
Pre-tax deductions change the picture. If the employee's 401(k) election applies to bonuses and they defer 10%, $1,000 goes to the plan and federal income tax withholding drops to $1,980. FICA still applies to the full $10,000, because 401(k) deferrals are subject to Social Security and Medicare.
Three things stack up. The 22% federal rate, 7.65% FICA and state withholding can easily reach 33% to 38% of the check. If the employer used the aggregate method, the annualized calculation can push federal withholding well past 22% for that period. And if the bonus is large enough to cross $200,000 in wages from that employer, the 0.9% Additional Medicare Tax starts.
The withholding then gets reconciled when you file. Three 2026 single filers, each receiving a $10,000 bonus withheld at 22%, using the 2026 brackets and $16,100 standard deduction from the IRS 2026 inflation adjustments:
| Salary | Taxable income incl. bonus | Bracket the bonus falls in | Federal tax on bonus | Withheld | Result |
|---|---|---|---|---|---|
| $40,000 | $33,900 | 12% | $1,200 | $2,200 | About $1,000 back |
| $80,000 | $73,900 | 22% | $2,200 | $2,200 | Roughly even |
| $180,000 | $173,900 | 24% | $2,400 | $2,200 | About $200 more owed |
These figures isolate the bonus and ignore credits and other income. The point holds: lower earners tend to be over-withheld on bonuses and higher earners under-withheld.
Social Security tax stops once an employee's wages for the year reach $184,500 for 2026, per IRS Topic 751 on Social Security and Medicare withholding. A $40,000 December bonus paid to someone who earned $190,000 in salary by November carries no Social Security at all, only Medicare. The employer's matching 6.2% stops at the same point. If an employee changed jobs mid-year and two employers both withheld Social Security past the base, the employee claims the excess as a credit on the 1040; the employers don't get theirs back.
Most "bonus tax strategies" are just ways to lower taxable wages, and they work the same on salary.
Non-cash bonuses deserve a mention. Gift cards, cash-equivalent awards and a paid vacation are taxable wages too; our guide to which fringe benefits are taxable covers the narrow exceptions for small achievement awards and de minimis items.
| Payment | Supplemental wage? | Notes |
|---|---|---|
| Performance or year-end bonus | Yes | Flat or aggregate method |
| Signing or retention bonus | Yes | Repayment clauses don't change withholding at payment |
| Commissions | Yes | Often paid separately each month |
| Severance | Yes | Also subject to FICA |
| Accumulated vacation payout | Yes, if paid on top of regular wages | Pub 15 treats lump sums for unused leave as supplemental |
| Reported tips | Yes, for income tax withholding | Employer may treat as regular wages instead |
| Stock awards (RSUs) at vesting | Yes | Value is wages; see ASC 718 accounting for stock compensation for the book side |
For the business owner, a bonus costs more than its face amount. On a $10,000 bonus the employer also pays $765 in matching FICA (less if the employee is past the Social Security base) and FUTA if the employee hasn't yet reached the $7,000 FUTA wage base for the year, which is reported on Form 940. The withheld amounts and the employer share flow onto the quarterly Form 941, and a large December bonus run can change your deposit schedule if it pushes you over $100,000 of liability on a single day, triggering the next-day deposit rule.
Deduction timing. An accrual-method business can generally deduct a year-end bonus in the year it is accrued if the bonus is fixed by year end and paid within two and a half months after year end (by March 15 for a calendar-year company). That rule doesn't help for related parties under Section 267, which includes any shareholder-employee of an S corporation and owners of more than 50% of a C corporation. Their bonuses are deductible when paid.
S corporation owners. Paying an owner a bonus through payroll can help support the salary side of the reasonable compensation test, but the bonus must be run as wages with withholding, not as a distribution.
Grossed-up bonuses. If you promise a $5,000 net bonus, gross it up: $5,000 ÷ (1 − 0.22 − 0.0765) = $7,107.32 before any state tax. Withholding errors on bonus runs are among the most common items in our payroll mistakes guide, and unremitted withholding is exactly what triggers the Trust Fund Recovery Penalty against owners personally.
Multi-state staff. States set their own bonus withholding rules, and several publish a separate supplemental rate. For remote teams, the work-location state usually controls; see our guide to multi-state payroll taxes.
No. At filing, bonus income and salary are added together and taxed under the same brackets. Only the withholding differs during the year, and that is trued up on your return.
Not under the flat-rate method, which allows only 22%. If your employer uses the aggregate method, your Form W-4 drives the calculation, so updating the W-4 before the bonus run changes the result. Claiming exemption to dodge withholding on a bonus is not permitted unless you truly expect no federal tax liability.
No. The deduction covers only the FLSA-required premium portion of overtime pay. A bonus may raise the regular rate used to calculate that premium, but the bonus itself stays fully taxable.
The same way as any employee's: income tax withholding plus FICA through payroll, reported on the W-2. The company can deduct the bonus only when paid, because S corporation shareholder-employees are related parties for deduction timing.
The rates are the same: 22% and 37%. What changed is the Social Security wage base, which rose to $184,500, and the income tax brackets and standard deduction, which were adjusted for inflation, so the final tax on the same bonus can differ slightly.
Running bonus payrolls correctly means choosing the right withholding method, tracking the wage bases and getting the 941 and W-2 right. Madras Accountancy supports US CPA firms and businesses with outsourced payroll and 1099 services, from year-end bonus runs to quarterly filings. Contact our team to talk through your payroll setup.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



