



The right time to hire a fractional CFO is when a financial decision with real consequences is coming and nobody inside the business can model it, defend it to a lender or investor, or manage the cash around it. In practice that moment usually arrives with one of five events: a cash squeeze, a new loan or covenant, a fundraising round, a purchase or sale of a business, or growth that has outrun your reporting.
Revenue alone is a weak guide to when to hire a fractional CFO. A $3 million company preparing to sell can need senior finance help more urgently than a stable $15 million company with a strong controller. This guide sets out the hiring triggers and a weighted scorecard you can fill in for your own business.
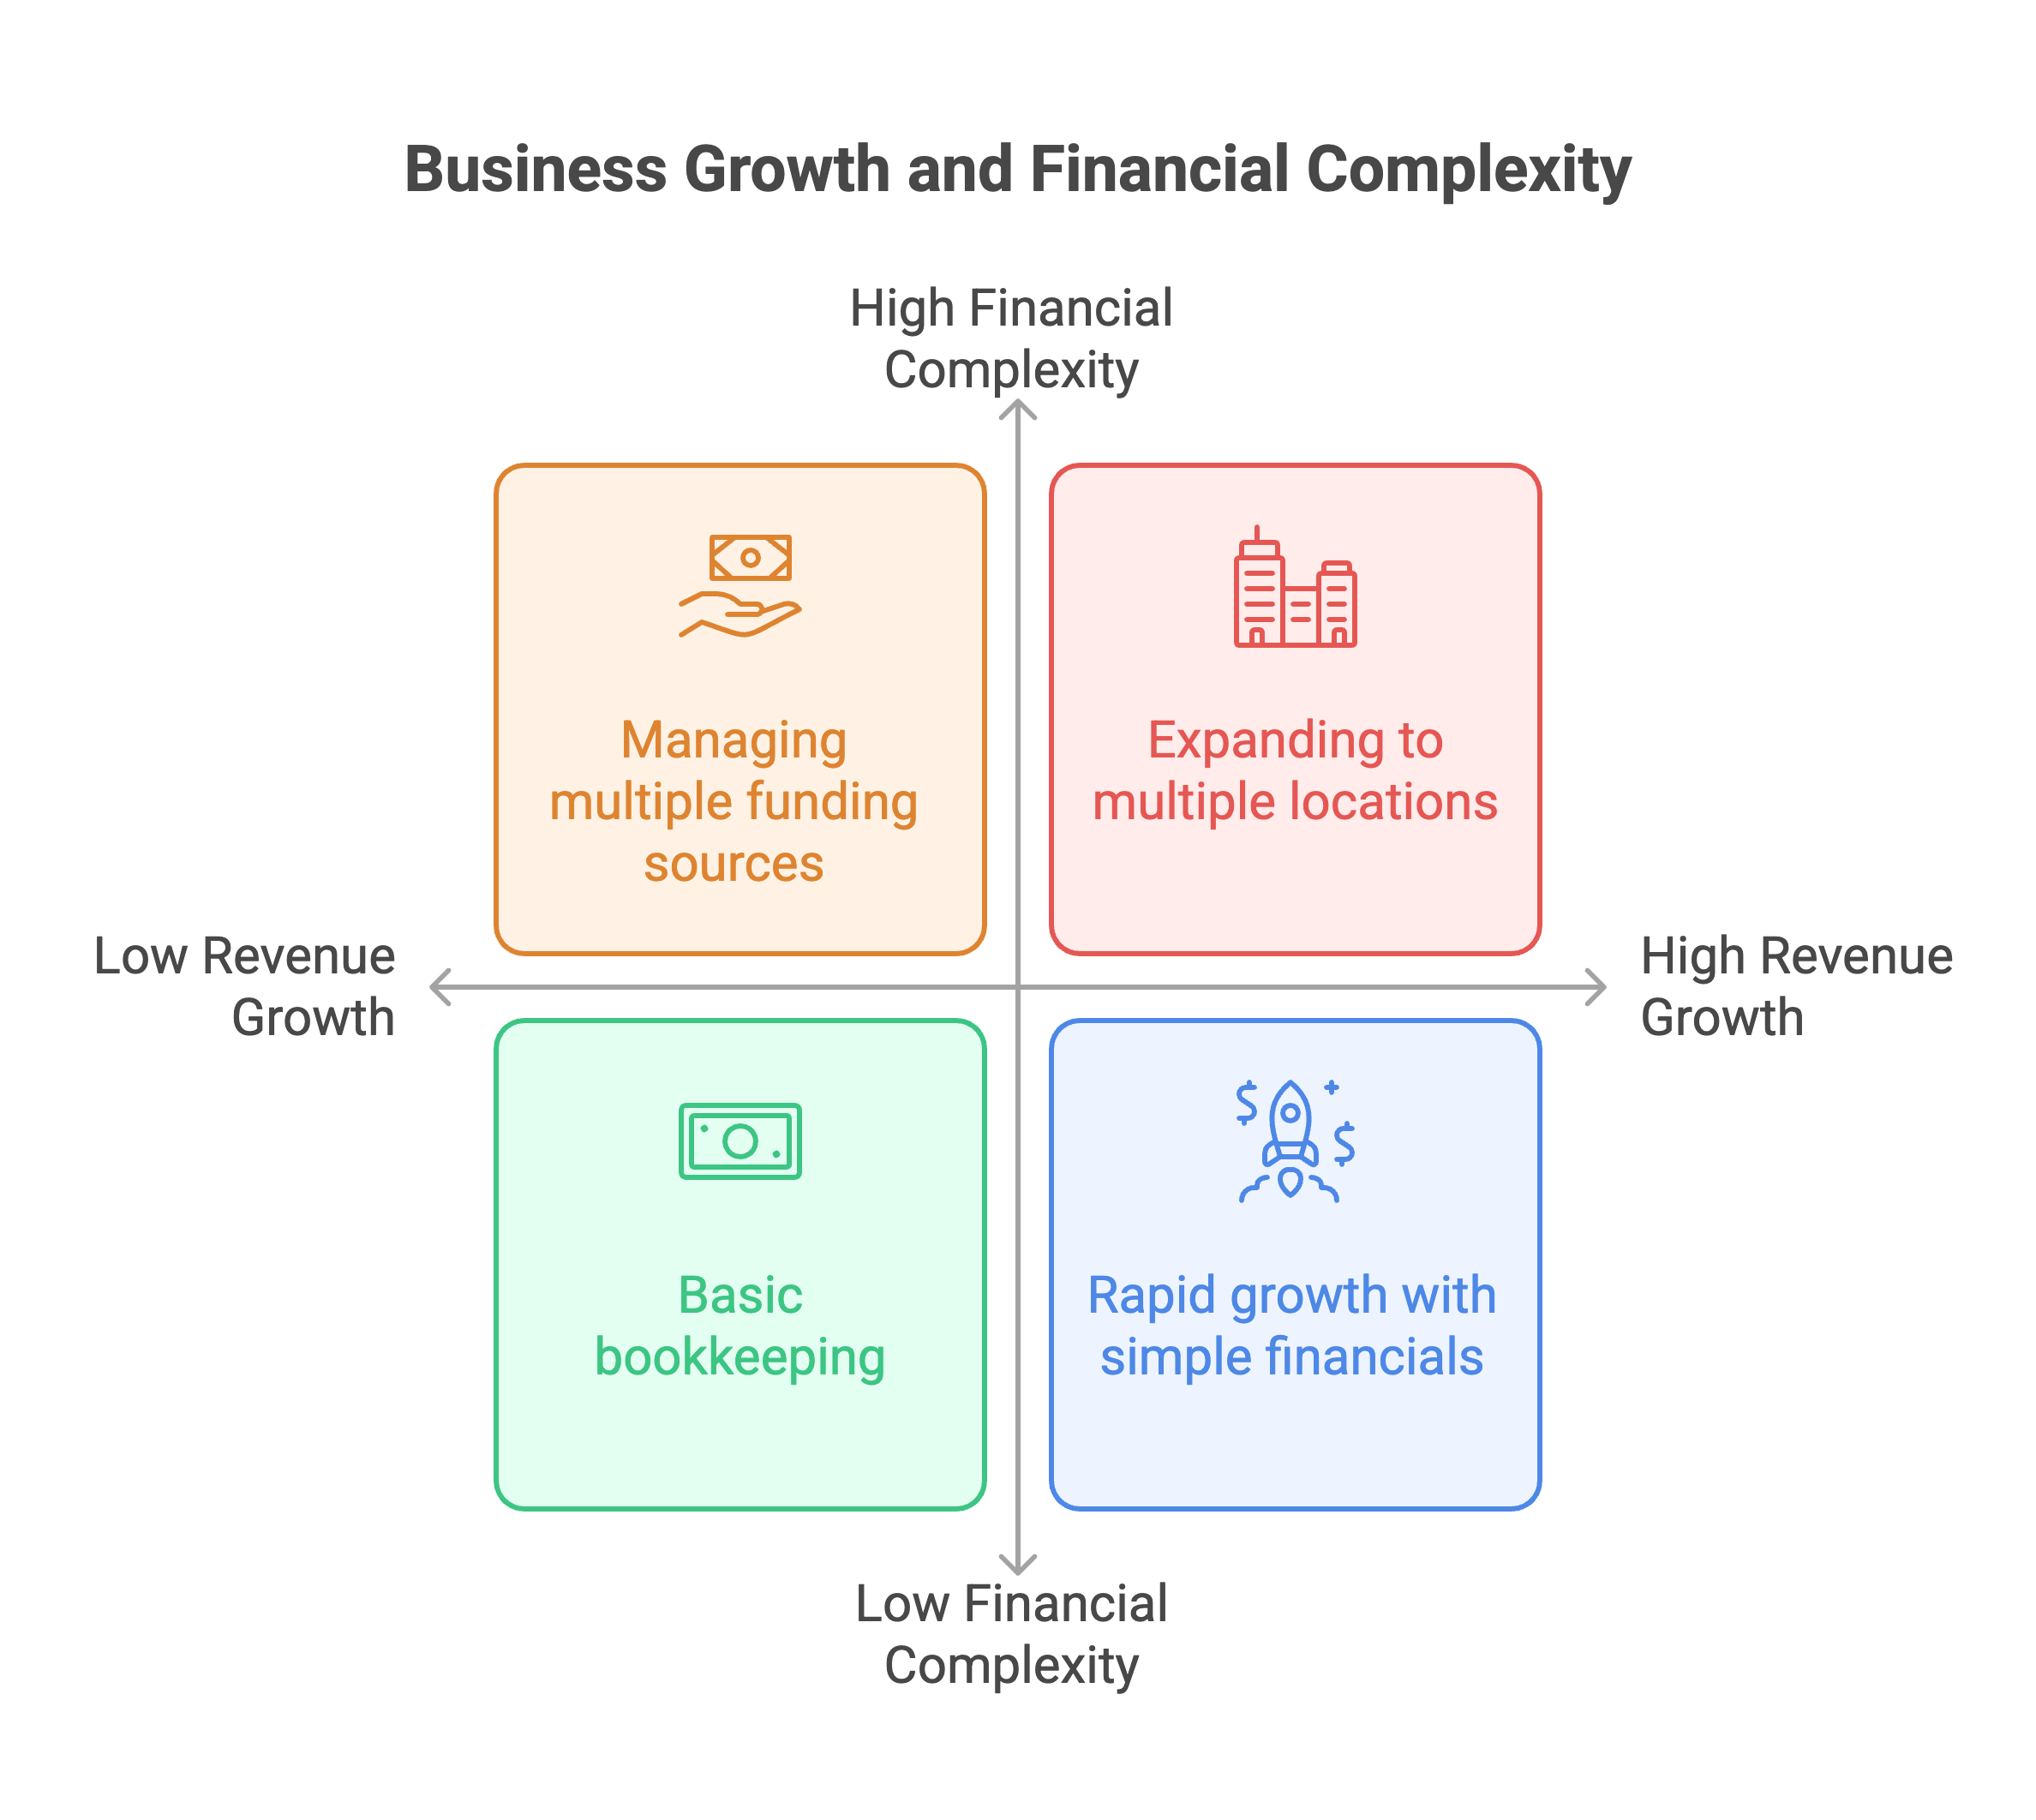
Most small companies run finance with a bookkeeper, an outside CPA for tax, and the owner. That setup records the past and files returns. It rarely produces a forward-looking cash forecast, a covenant compliance model or an investor-ready financial plan. If you are unsure which role covers which job, our breakdown of bookkeeper vs accountant vs CPA vs CFO responsibilities maps the handoffs.
A fractional CFO is a senior finance executive who works for you part of the month, usually on a retainer, and owns planning, capital and decision support. Some firms use the term virtual CFO for the same remote, part-time model. If the real gap is a slow close and messy reconciliations, a controller may be the better first hire, and our comparison of controller vs fractional CFO roles shows where one ends and the other begins.
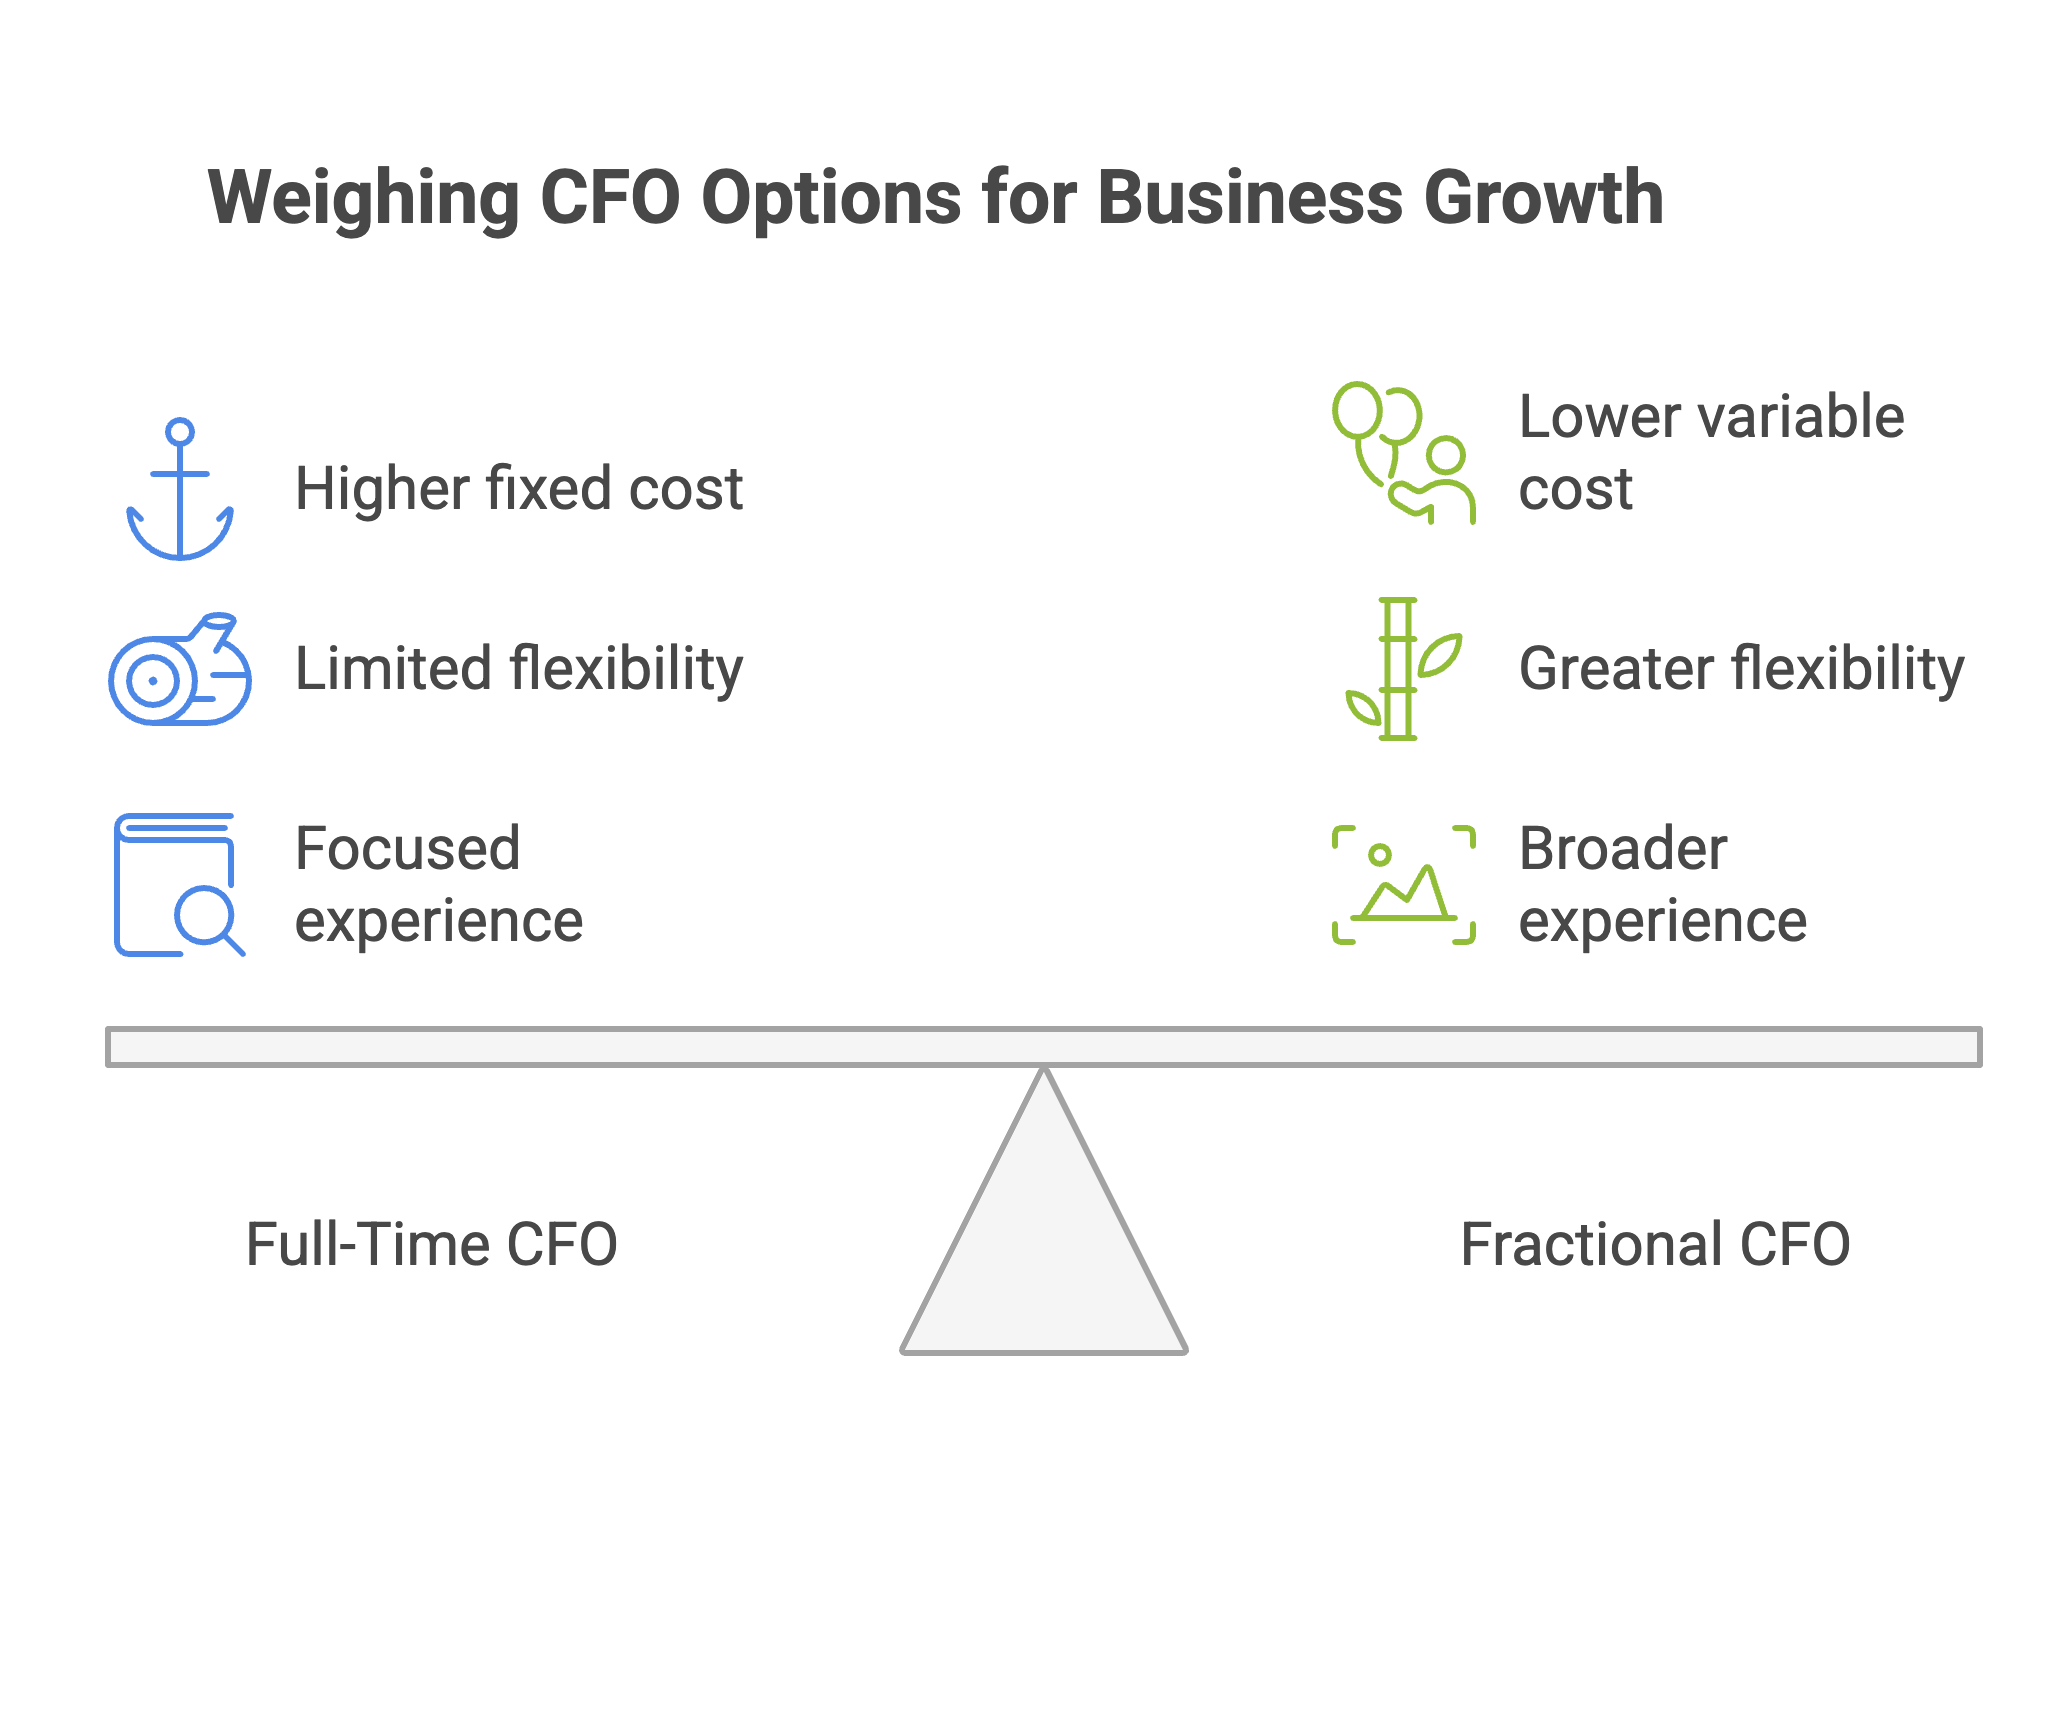
The full-time alternative is expensive. The Bureau of Labor Statistics groups CFOs with chief executives, and reports that the median annual wage for chief executives was $213,990 in May 2025, before benefits, bonus or equity.
A cash crunch is the most common reason owners call for help, and federal survey data shows how widespread the pressure is. The Federal Reserve's 2026 Small Business Credit Survey report on employer firms, fielded in late 2025 and released in March 2026, found that 77% of firms reported rising costs, tariff-related costs, or both as a financial challenge. Among firms that sought financing, the most common reason was to meet operating expenses (56%).
Signs that cash has become a CFO-level problem:
A fractional CFO typically builds a weekly cash forecast first. The methods are covered in our guide to cash flow scenario planning techniques, which shows how to model base, downside and recovery cases.
Debt is normal for small firms. The same Fed survey reports that only 31% of firms had no outstanding debt, which means roughly two in three carry some. It also found that 42% of financing applicants received the full amount they sought, 36% received some or most, and 22% received nothing.
Some lenders tie credit to regular, monitored reporting. The SBA describes its 7(a) Working Capital Pilot as offering monitored lines of credit, and says the program suits a business that "can produce timely and accurate financial statements, accounts receivable and accounts payable agings, and inventory reports." The maximum 7(a) loan is $5 million.
Once a loan agreement includes financial covenants, such as a minimum fixed charge coverage ratio or a maximum debt-to-EBITDA multiple, someone needs to project those ratios months ahead. A breach can trigger default interest or a demand for repayment, even in a profitable year. Our checklist for business loan preparation and lender documentation covers what to assemble before applying.
Illustrative covenant check. A company has EBITDA of $900,000, unfinanced capital spending of $150,000 and cash taxes of $50,000, leaving $700,000 to cover debt service. Annual principal of $400,000 plus interest of $160,000 gives debt service of $560,000. The fixed charge coverage ratio is $700,000 divided by $560,000, or 1.25x. If the covenant minimum is 1.25x, the company has zero headroom. A 10% drop in EBITDA to $810,000 cuts the ratio to about 1.09x, a breach. A fractional CFO would flag this two or three quarters ahead and negotiate with the bank before the test date.
Investors expect a three-statement model, a defensible use-of-funds plan, clean historical financials and a data room. Securities rules also apply to private raises. Under SEC Rule 503, a company relying on Regulation D must file a notice on Form D no later than 15 calendar days after the first sale of securities in the offering. Securities counsel handles the legal filing, and the CFO supplies the numbers, the cap table math and the investor reporting that follows.
Bring the fractional CFO in three to six months before you start meetings (practitioner guidance). Our article on how fractional CFOs help attract investors walks through the pitch materials in detail.
M&A is where an experienced finance lead pays for itself fastest. On the buy side, the CFO tests the target's quality of earnings, working capital needs and integration costs. On the sell side, the CFO prepares normalized EBITDA, defends add-backs and answers diligence requests before they slow the deal. Our M&A due diligence checklist for the financial review lists what buyers will request.
If the transaction is large or the company has lost its finance lead at the same time, an interim CFO who steps in full time for a defined period can be a better fit than a part-time retainer.
Revenue growth, new locations, a second legal entity, foreign sales or a move from cash to accrual accounting all add complexity. The warning signs are practical: the monthly close takes more than three weeks, managers argue about which numbers are right, or margins by product or location are unknown.
A first financial statement audit is a related trigger. Lenders, investors, franchisors and some customers ask for audited statements as a company grows. Nonprofits and other recipients of federal grants face a hard threshold: under the federal Uniform Guidance, a non-Federal entity that expends $1,000,000 or more in Federal awards in its fiscal year must obtain a single or program-specific audit. Our guide to preparing for a first external audit covers the readiness work.
Use the table below as a rough map. The revenue bands are practitioner guidance, and the trigger column matters more than the revenue column.
| Stage (annual revenue, guidance) | Typical finance setup | Signals that justify a fractional CFO | Usual starting scope |
|---|---|---|---|
| Under $2M | Bookkeeper and tax CPA | Fundraising, a large loan, or a sale in sight | Project work: model, forecast, lender pack |
| $2M to $10M | Bookkeeper or staff accountant, owner as finance lead | Cash swings, first covenants, new entity or location | Monthly retainer: forecast, KPIs, budget |
| $10M to $25M | Controller or senior accountant | Board reporting, acquisitions, audit, multiple lenders | Larger retainer with strategic projects |
| $25M and up | Controller plus small team | Complexity near full-time levels | Fractional as a bridge, then full-time hire |
For what each band typically costs, see our breakdown of outsourced CFO cost by company size.
The One Big Beautiful Bill Act, enacted in July 2025, changed several provisions that affect cash planning for capital-heavy and research-heavy companies. The IRS summary of business provisions confirms a permanent 100% additional first-year depreciation deduction for qualified property acquired after January 19, 2025, and an increase in the Section 179 expensing limit from $1,000,000 to $2,500,000, reduced once qualifying property placed in service exceeds $4,000,000. Both amounts are indexed for inflation for tax years beginning after 2025.
These rules change the after-tax cost of equipment and the timing of estimated tax payments. A fractional CFO works with your CPA so the capital budget, the debt plan and the tax plan rest on the same assumptions. Tax filing stays with the CPA.
The scorecard below turns the triggers into a number. Score each signal from 0 to 3, multiply by the weight, and add the results. The weights and bands are guidance built from the triggers above, and you should adjust them for your industry.
| Signal | Weight | 0 | 3 |
|---|---|---|---|
| Revenue scale and growth rate | 2 | Stable, under $2M | Over $10M or growing 30%+ a year |
| Cash visibility and runway | 3 | 13-week forecast in place, ample cash | Shortfalls found at the bank |
| Lender exposure and covenants | 2 | No debt | Covenants with thin headroom |
| Equity raise in next 12 months | 3 | None planned | Raise starting within 6 months |
| Acquisition or sale in next 18 months | 3 | None | Letter of intent signed or expected |
| Entity, location and system complexity | 2 | One entity, one location | Several entities, states or currencies |
| Reporting quality and close speed | 2 | Close in 10 days, KPIs reviewed | Close over 3 weeks, no budget |
| Owner hours spent on finance | 1 | Under 5 hours a month | Over 20 hours a month |
The maximum score is 54. Read the total this way:
One override applies. A score of 3 on cash, fundraising or M&A means you should bring in senior finance help now, whatever the total.
This example is illustrative. A wholesale distributor has $7.5 million in revenue growing about 20% a year, two warehouses in different states, and a bank revolver with a fixed charge coverage covenant sitting right at its 1.25x minimum. Cash shortfalls usually show up first in the bank balance, the monthly close takes about two weeks, and the owner spends about 25 hours a month on finance. There is no fundraising plan, and the owner has had one informal approach from a buyer.
| Signal | Weight | Score | Weighted |
|---|---|---|---|
| Revenue scale and growth | 2 | 2 | 4 |
| Cash visibility and runway | 3 | 3 | 9 |
| Lender exposure and covenants | 2 | 3 | 6 |
| Equity raise | 3 | 0 | 0 |
| Acquisition or sale | 3 | 1 | 3 |
| Complexity | 2 | 2 | 4 |
| Reporting quality | 2 | 2 | 4 |
| Owner hours | 1 | 3 | 3 |
| Total | 33 of 54 |
The total of 33 lands in the retainer band, and the cash score of 3 triggers the override on its own. The right move is a monthly engagement focused first on a 13-week cash forecast and a covenant projection, then a budget and KPI pack for the bank.
To test the economics, assume 15 hours a month at an illustrative senior rate of $290 an hour, the modelled rate from our cost-by-size guide. That is $4,350 a month, or $52,200 a year. The BLS median wage for chief executives of $213,990 is about 4.1 times that figure, and the full-time comparison is higher still once benefits are added. Actual quotes vary widely by scope and provider.
Some situations call for a different answer:
Once the scorecard says yes, the next steps are choosing the person and setting up the working relationship. Use our list of questions to ask a fractional CFO before you hire to compare candidates on experience, scope and contract terms. Then use our guide on how to work with a fractional CFO to set goals for the first 90 days, give access to data and agree on a reporting rhythm.
Write down the two or three outcomes you need in the first six months before the first meeting. Those outcomes become the measure of whether the engagement worked.
At what revenue should a business hire a fractional CFO? Many companies bring one in somewhere between $2 million and $10 million in revenue, but that range is guidance. Events matter more than size: a loan with covenants, a planned raise, an acquisition or a cash squeeze can justify a fractional CFO at almost any revenue level.
What are the signs you need a fractional CFO? The common signs are cash surprises, a slow or unreliable monthly close, no budget or forecast, lender or investor requests you cannot answer quickly, and an owner spending more than 20 hours a month on finance. If several apply at once, score your business with the scorecard above.
Should I hire a fractional CFO before raising money? Yes, ideally three to six months before you start investor meetings. That window allows time to clean up the historical financials, build the model and prepare the data room.
Is a fractional CFO worth it for a small business? It is worth it when the decisions ahead carry more financial risk than the fee. A single avoided covenant breach, a better loan structure or a higher sale price can outweigh a year of fees. If the books are not yet reliable, start with bookkeeping and add CFO support later.
When should a company move from a fractional to a full-time CFO? Move when the work fills most of a week on a steady basis, when the company prepares for a public listing, or when the board wants a dedicated executive. Many companies use the fractional CFO to define the role and help recruit the permanent hire.
Madras Accountancy provides bookkeeping, tax preparation, CFO and advisory support, payroll and audit support for US businesses. If your scorecard points toward senior finance help, contact our team to talk through the scope that fits your company.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



