


The most effective working capital management strategies for growing businesses shorten the cash conversion cycle: collect from customers sooner, hold less inventory per dollar of sales, pay suppliers on the latest date that keeps terms intact, and forecast cash 13 weeks ahead so financing is arranged before it is needed. Each day you remove from the cycle releases cash that would otherwise sit in receivables or on shelves.
This guide applies working capital management strategies for growing businesses to US companies in 2026. It covers the formulas behind days sales outstanding (DSO), days inventory outstanding (DIO) and days payable outstanding (DPO), a worked example in real dollars, tactics for each balance sheet line, a 13-week forecast structure, and the SBA loan limits that apply when internal cash falls short.
Net working capital is current assets minus current liabilities. Current assets are items a business expects to turn into cash within a year, such as cash, accounts receivable and inventory. Current liabilities are obligations due within a year, such as accounts payable, accrued wages and the current portion of debt. The OpenStax Principles of Finance textbook describes working capital as "the resources that are needed to meet the daily, weekly, and monthly operating cash flow needs."
The same text makes the point that matters most for an expanding company: "Growing companies, even if they are extremely profitable, need additional working capital as they ramp up operations." When sales rise, receivables and inventory rise with them, and they rise before the cash from those sales arrives. A company can post record profit on its income statement and still struggle to meet payroll, which is why owners who read their financial statements together watch the balance sheet as closely as the P&L.
Survey data shows how common this pressure is. The Federal Reserve Banks' 2026 Report on Employer Firms, based on 6,525 responses to the 2025 Small Business Credit Survey, found that 60% of firms applied for financing in the prior 12 months. The most common reason was "to meet operating expenses (56%)," ahead of pursuing an expansion or new opportunity (46%). The same report found that 77% of firms named rising costs, tariff-related costs or both as a financial challenge.
The cash conversion cycle (CCC) counts the days between paying for inventory and collecting cash from the customer who bought it. OpenStax gives the formula as inventory conversion period plus receivables collection period minus payables deferral period. In the shorthand most finance teams use:
Average balances across the year give a steadier reading than a single year-end figure. The example below uses year-end balances to keep the arithmetic easy to follow.
A wholesale distributor reports annual revenue of $7,300,000, all on credit, and cost of goods sold of $4,380,000. That works out to $20,000 of revenue and $12,000 of COGS per day. Its year-end balance sheet shows receivables of $1,000,000, inventory of $720,000 and payables of $360,000.
The business has $1,360,000 tied up in the operating cycle ($1,000,000 + $720,000 − $360,000). Now suppose management sets three targets for the next year.
| Metric | Current | Target | Balance change | Cash effect |
|---|---|---|---|---|
| DSO | 50 days | 40 days | AR falls from $1,000,000 to $800,000 | +$200,000 |
| DIO | 60 days | 50 days | Inventory falls from $720,000 to $600,000 | +$120,000 |
| DPO | 30 days | 35 days | AP rises from $360,000 to $420,000 | +$60,000 |
| CCC | 80 days | 55 days | Cycle investment falls to $980,000 | +$380,000 |
At the same sales level, cutting 25 days from the cycle releases $380,000. Growth pulls in the opposite direction. If revenue and COGS both rise 30% and the cycle stays at 80 days, the cycle investment grows from $1,360,000 to $1,768,000, so the company needs an extra $408,000 just to fund the larger receivables and inventory. Hitting all three targets while growing 30% would hold the cycle investment at $1,274,000, below today's $1,360,000, so the process changes would fund the growth without new debt. Tracking these days alongside the other ratios in a financial ratio analysis shows which lever is slipping before the bank balance does.
Receivables are usually the largest single block of cash a growing service or B2B firm controls. Tactics that move DSO:
Inventory ties up cash, warehouse space and insurance. Growing product companies tend to over-order in anticipation of demand that arrives later than planned.
Paying on day 30 instead of day 15 on net 30 terms is free financing. Paying on day 45 against net 30 terms risks late fees, credit holds and worse pricing.
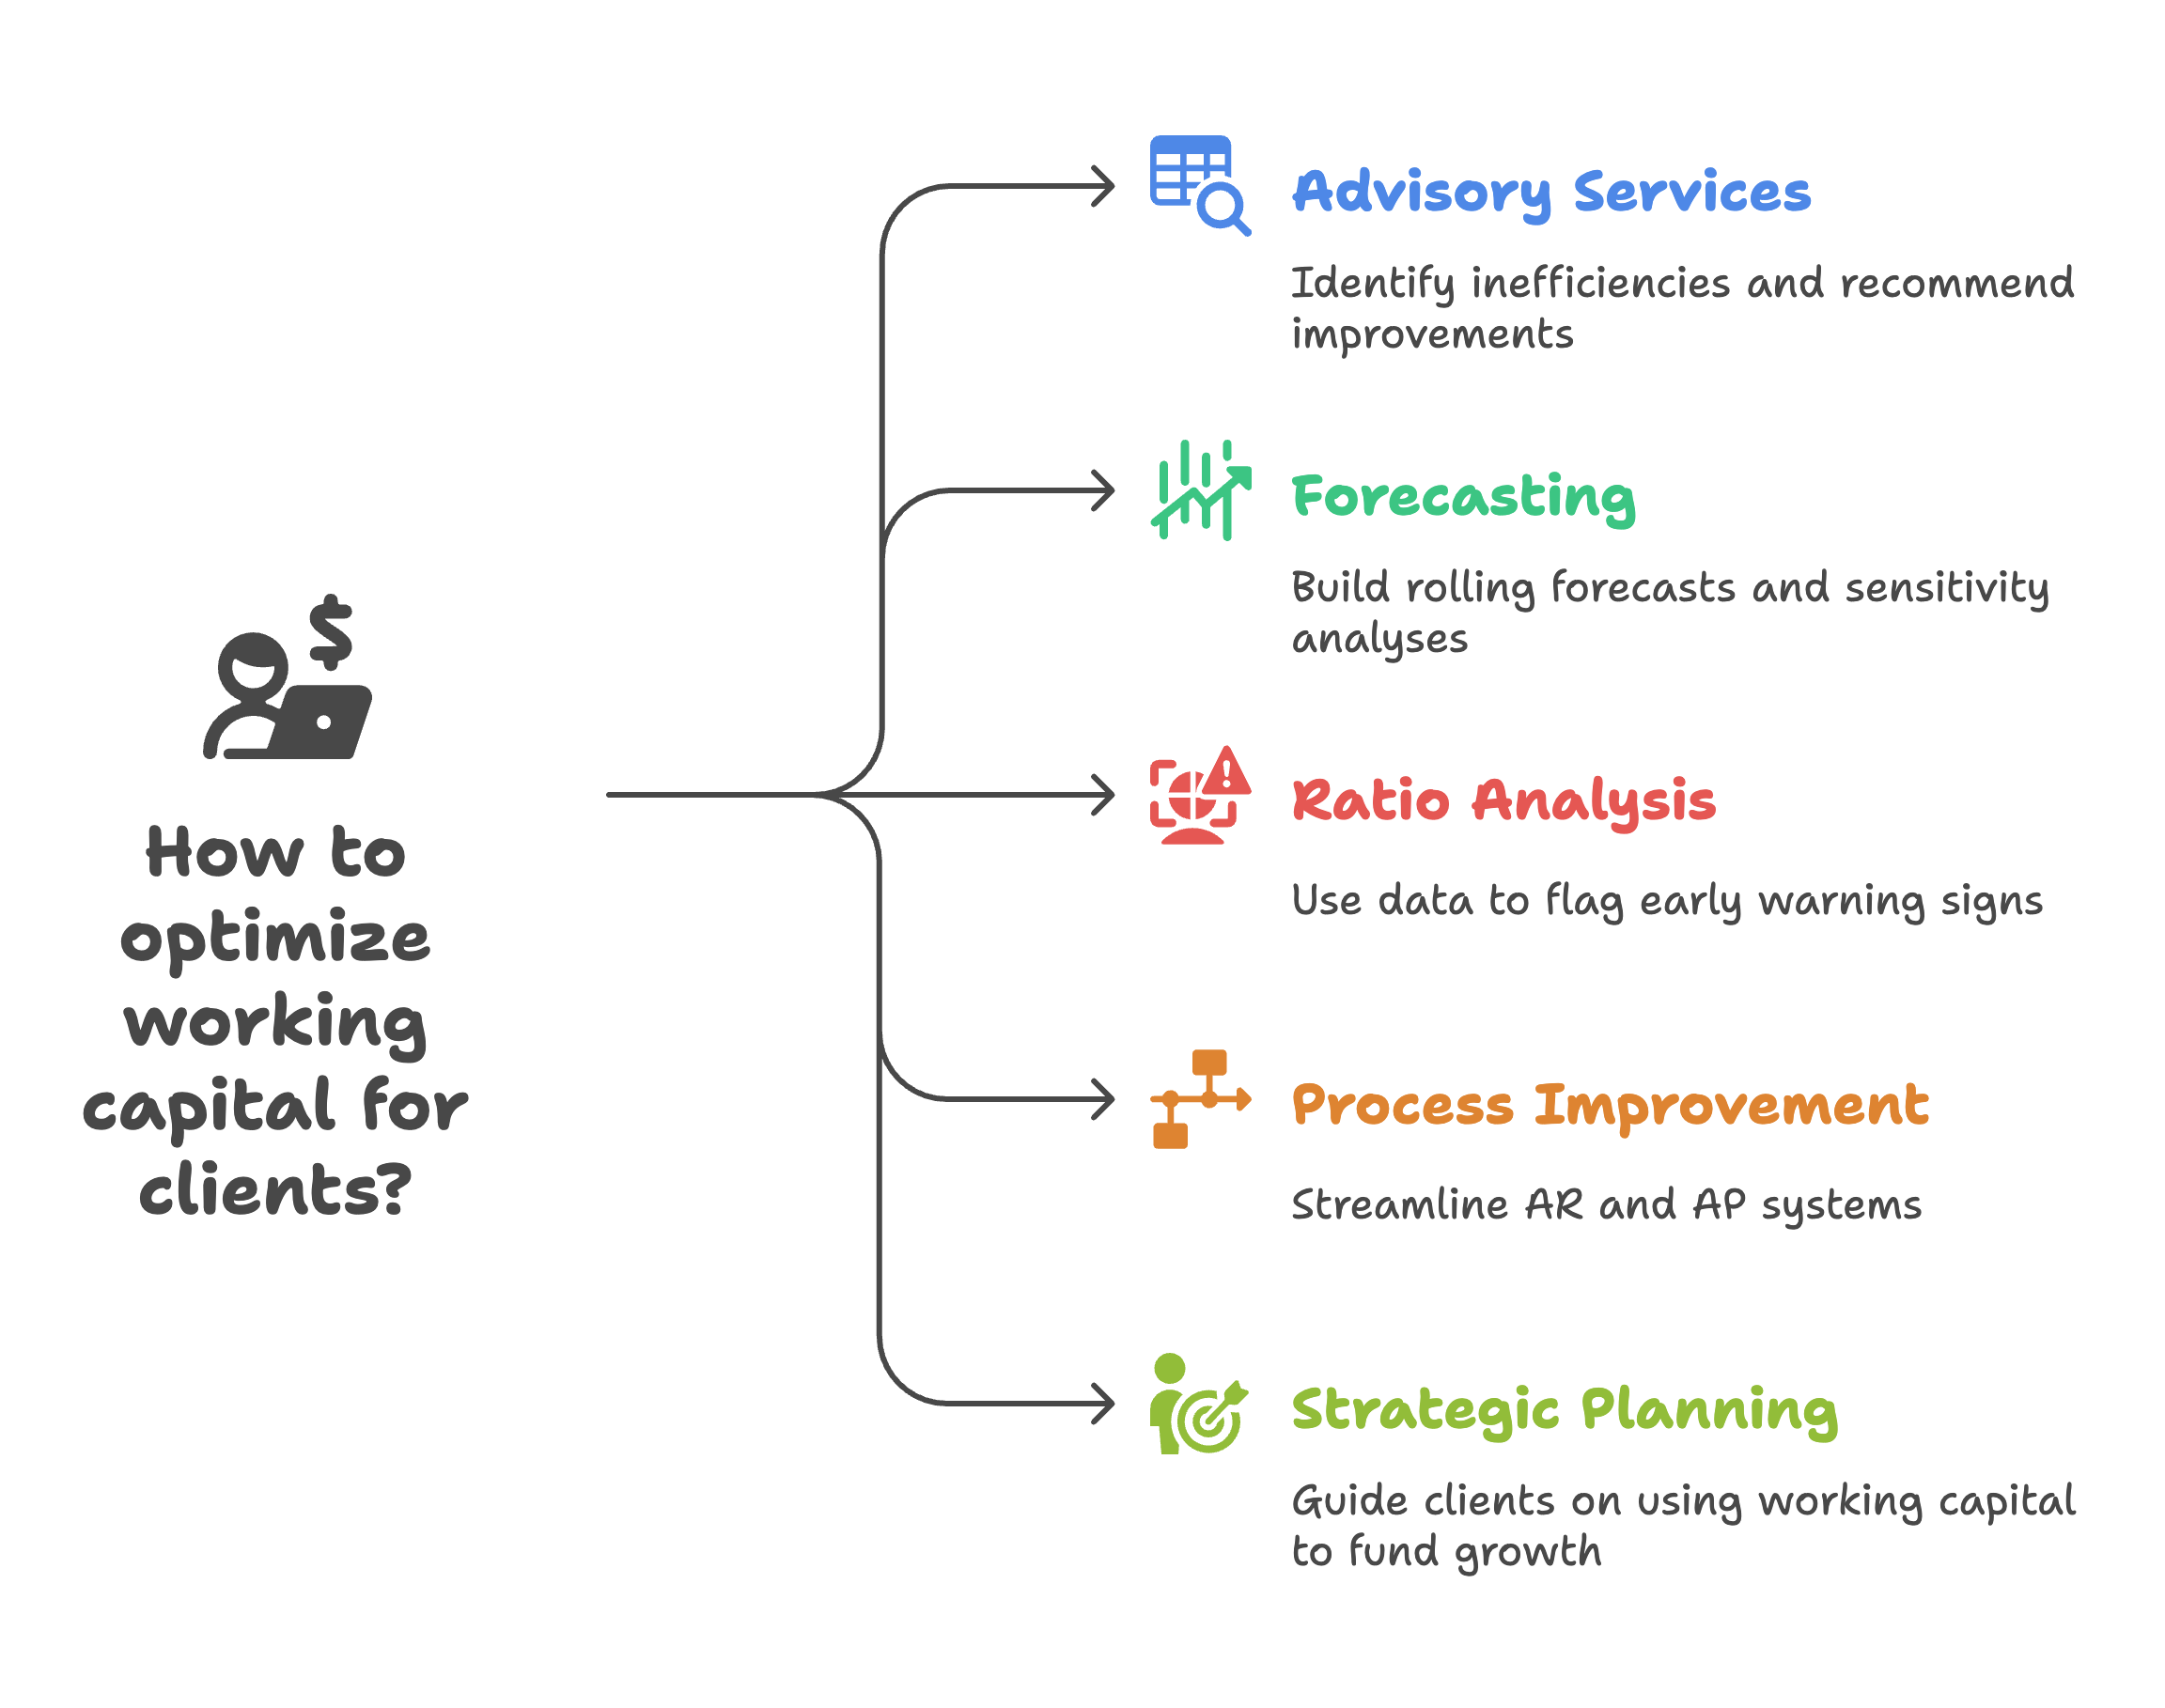
Ratios describe the past. A 13-week cash flow forecast shows the next quarter week by week, which is the window in which most cash shortfalls appear and can still be fixed.
A practical layout:
Update the model every week and compare actual receipts and payments with the forecast. Variances show whether customers are paying later than expected or whether spending is running ahead of plan. Our 13-week cash flow forecast setup guide walks through the spreadsheet, and a broader overview of cash flow forecasting tools and techniques covers longer horizons.
Run at least two versions: a base case and a downside case where a large customer pays 30 days late or a key product sells 20% below plan. Cash flow scenario planning turns those cases into decisions, such as when to draw on a credit line or delay a hire.
The forecast is only as reliable as the books behind it. A month-end close that reconciles bank, AR and AP accounts within a few business days, such as the process in this 5-day AP, AR and reconciliation checklist, gives the forecast accurate starting balances.
Process improvements reduce the amount you need to borrow. Fast growth, seasonal peaks or a large new contract can still require outside money. Arrange it while the numbers look healthy, because lenders approve on historical financial statements.
| Program | Maximum amount | SBA guaranty | Working capital use |
|---|---|---|---|
| Standard 7(a) | $5 million | Up to 75% | Short- and long-term working capital |
| 7(a) small | $350,000 | 85% up to $150,000; 75% above | Same uses as 7(a) |
| SBA Express | $500,000 | 50% | Revolving lines allowed, up to 10 years |
| 7(a) Working Capital Pilot | $5 million | 85% up to $150,000; 75% above | Lines of credit, maturity up to 60 months |
| Microloan | $50,000 | Made through intermediaries | Working capital listed as an eligible use |
Sources: the SBA 7(a) loans page states "The maximum loan amount for a 7(a) loan is $5 million" and lists "Short- and long-term working capital" among permitted uses. The SBA types of 7(a) loans page gives the program limits and notes that revolving lines are "Permitted only under SBA Express, Export Express, or CAPLines." The SBA microloan page describes loans up to $50,000 and says "The average microloan is about $13,000."
Lenders look at the same ratios covered above. Preparing clean statements, an AR aging and a 13-week forecast in advance shortens approval, as described in our guide to business loan preparation and documentation. The Federal Reserve report also found that 59% of firms with debt used a personal guarantee to secure it, so owners should read guarantee terms before signing.
Funding long-term assets with short-term money. Using a revolving line to buy equipment drains the capacity you need for receivables and inventory. Match long-lived purchases with term loans or equipment financing.
Chasing revenue with loose credit terms. Winning a large customer on net 90 terms can add months of receivables. Model the cash effect in the 13-week forecast before agreeing, and price the extended terms into the deal.
Ordering ahead of demand. A buying spree for an expected surge raises DIO the moment stock lands. Stage purchases so each order follows confirmed sales data.
Ignoring tax payments in the forecast. Quarterly estimated taxes, sales tax remittances and payroll tax deposits are large, predictable outflows. Leaving them out of the model makes cash look healthier than it is.
Measuring once a year. DSO, DIO and DPO drift month to month. Adding them to a monthly dashboard of essential small business KPIs means a slipping metric gets attention within weeks.
Waiting until the bank balance is low to borrow. A company that applies for credit during a shortfall has weaker statements and fewer options. The Federal Reserve report found that only 42% of applicants received the full amount of financing they sought.
What is a good cash conversion cycle for a small business? It depends on the industry. A retailer that sells stock before its supplier invoices fall due can run a very short or even negative cycle, while a manufacturer holding raw materials and finished goods will usually run a much longer one. Compare your CCC with your own trend and with businesses in your sector, and aim to shorten it year over year.
How much working capital does a growing business need? Start with the cycle investment: receivables plus inventory minus payables. If that equals 80 days of activity and sales grow 30%, the investment grows roughly 30% too unless the cycle shortens. Add a cash cushion based on your largest projected shortfall in the 13-week forecast.
Is negative working capital always a problem? No. Some business models collect cash before paying suppliers, such as subscription companies billing annually in advance or retailers with fast inventory turns. Negative working capital becomes a concern when it results from overdue payables or short-term debt that the business cannot roll over.
Should I take a 2/10, net 30 early-payment discount? In most cases, yes. The annual cost of skipping that discount is about 36.73% using a 360-day year, which is higher than the rate on most business lines of credit. If cash is tight, compare the discount with your borrowing cost before deciding.
How often should I update a 13-week cash flow forecast? Weekly. Roll the model forward by one week, replace forecast figures with actuals for the week just ended, and review variances with whoever manages collections and purchasing.
Madras Accountancy supports US businesses and CPA firms with bookkeeping, AR and AP processing, month-end close and cash flow forecasting, which give owners the accurate numbers these strategies depend on. To review your working capital process or set up a 13-week forecast, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



