

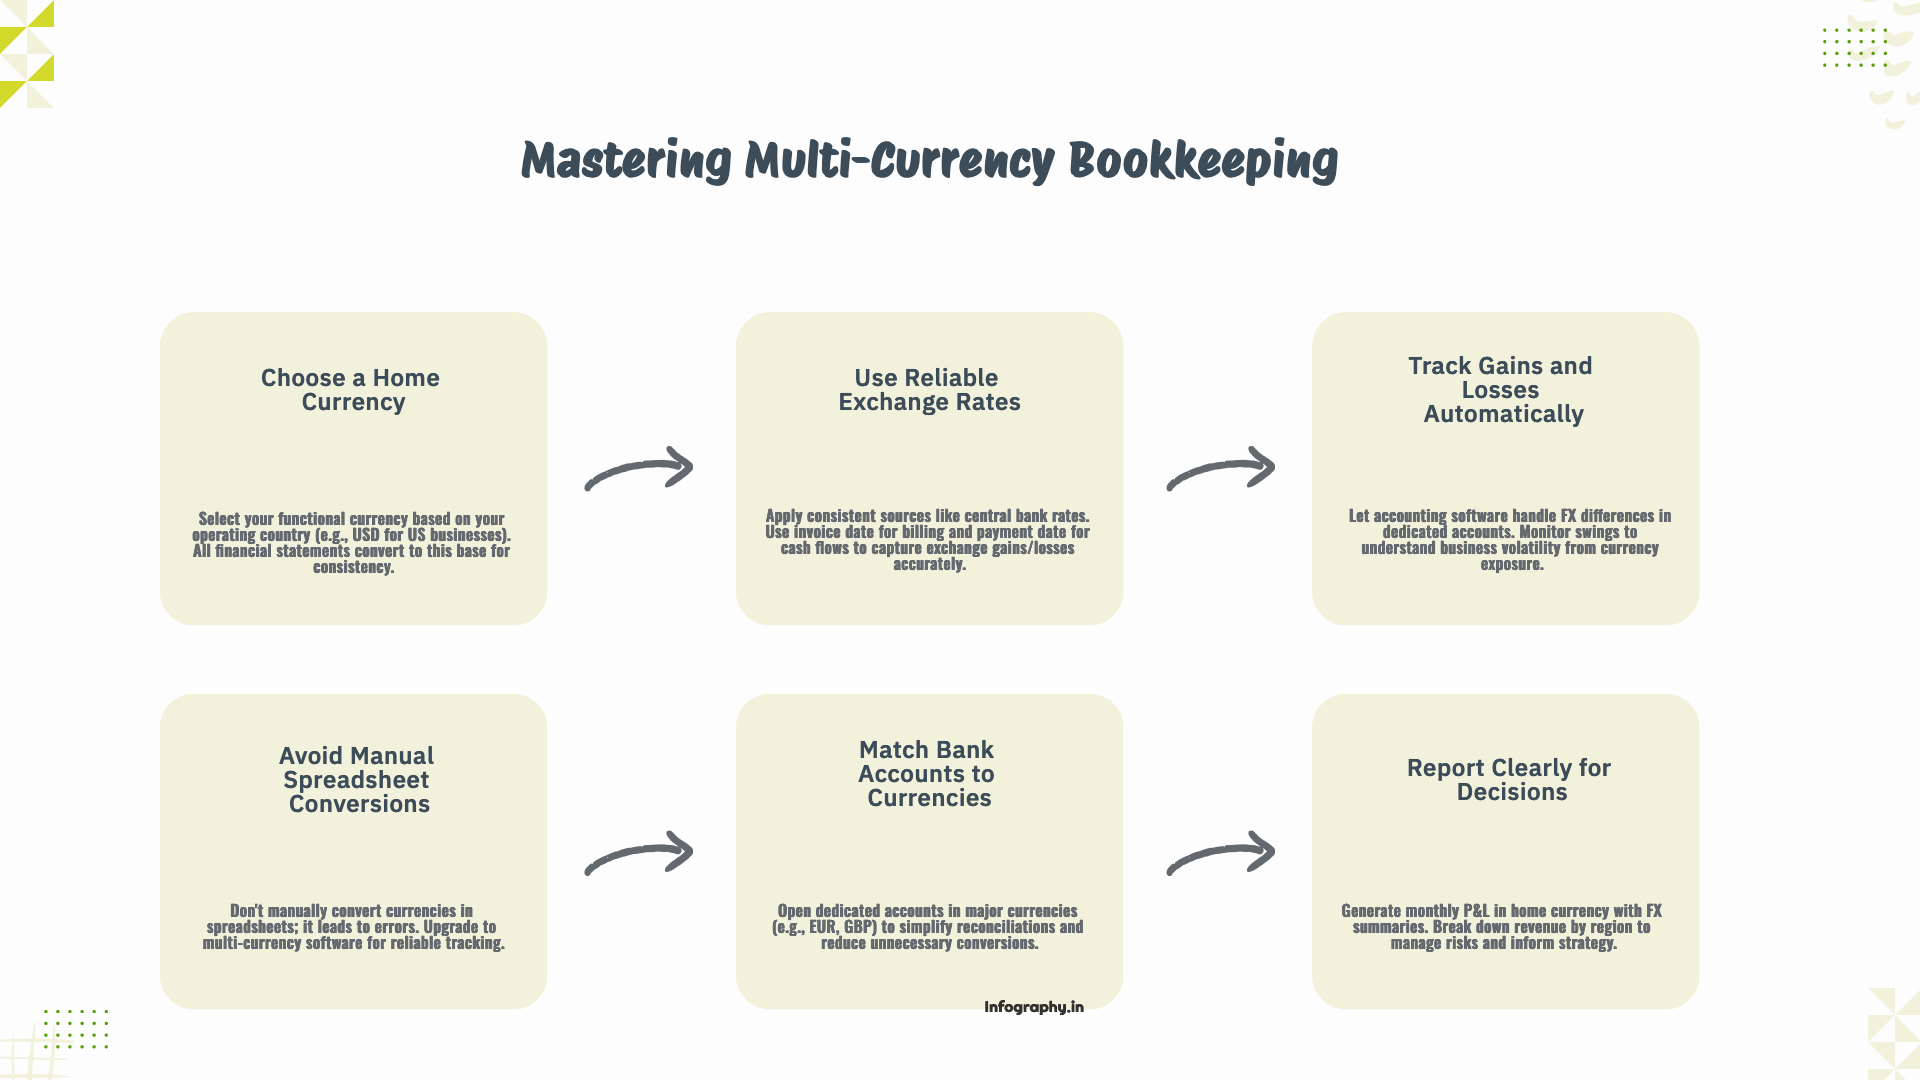

Multi-currency bookkeeping is the practice of recording sales, purchases and bank balances in the currency each transaction was made in, then converting them into your functional currency at the right exchange rate and posting the difference as a foreign exchange (FX) gain or loss. For most US companies the functional currency is the dollar, and every foreign invoice creates a small FX exposure from the day it is issued until the day it is paid.
This guide covers the day-to-day side of multi-currency bookkeeping under US GAAP (ASC 830), from remeasurement and month-end revaluation to software setup and the IRS rules for reporting in dollars. Translating a foreign subsidiary's full financial statements for a group report is a separate exercise, covered in our guide to financial consolidation software and ASC 830 translation.
ASC 830 builds everything around the functional currency. The Codification defines it as "the currency of the primary economic environment in which the entity operates; normally, that is the currency of the environment in which an entity primarily generates and expends cash" (Deloitte DART, Roadmap on Foreign Currency, section 1.4). A US company that sells to UK and German customers but pays its staff, rent and loans in dollars almost always has the dollar as its functional currency. Its foreign invoices are foreign currency transactions.
The reporting currency is the currency the financial statements are presented in. For a single US entity, both are dollars. An entity with transactions in other currencies "must first remeasure those amounts in its functional currency before they are translated into the reporting currency." The effects of remeasurement "are generally reported in the income statement," while the effects of translation "are reported in equity." Bookkeepers spend almost all of their time on remeasurement. Translation and the cumulative translation adjustment belong to the group reporting layer, which our overview of global accounting services for US companies places alongside transfer pricing and international filings.
| Term | What it means for the bookkeeper | Where the difference goes |
|---|---|---|
| Functional currency | The currency your ledger is measured in (usually USD for a US company) | Not applicable |
| Transaction currency | The currency printed on the invoice or bill | Not applicable |
| Remeasurement | Restating foreign currency balances into the functional currency at the current rate | Net income (FX gain or loss) |
| Translation | Converting a foreign entity's statements into the reporting currency | Other comprehensive income (CTA) |
| Reporting currency | The currency of the published statements | Not applicable |
Each foreign currency transaction is recorded at the exchange rate on the day it is recognized, and the receivable or payable carries both the foreign amount and a dollar carrying amount. ASC 830-20-35-1 says that this change "increases or decreases the expected amount of functional currency cash flows upon settlement of the transaction," and that the result is "a foreign currency transaction gain or loss that generally shall be included in determining net income for the period in which the exchange rate changes." ASC 830-20-35-2 then requires that, at each balance sheet date, recorded balances in a currency other than the functional currency "shall be adjusted to reflect the current exchange rate" (Deloitte DART, section 4.3).
Monetary items, such as cash, receivables, payables and loans, are remeasured at the current rate every period. Nonmonetary items, such as prepaid expenses and fixed assets bought in a foreign currency, stay at the historical rate.
The labels "realized" and "unrealized" come from practice and software:
Both go through net income under US GAAP. Separate accounts show which swings were locked in by cash and which may still reverse. When you set up your chart of accounts, add one account for realized FX gain or loss and one for unrealized FX gain or loss, both below operating income. Do not net them into revenue or cost of sales.
The figures below are illustrative. A US company with a dollar functional currency invoices a UK customer for £50,000 on 15 March. The customer pays on 30 April, and the pounds land in the company's GBP bank account.
| Date | Event | USD per GBP | USD value of £50,000 |
|---|---|---|---|
| 15 March | Invoice issued | 1.2700 | $63,500 |
| 31 March | Month-end revaluation | 1.2550 | $62,750 |
| 30 April | Customer pays | 1.2800 | $64,000 |
| 31 May | GBP bank balance revalued | 1.2650 | $63,250 |
15 March, record the sale. Dr Accounts receivable (GBP) $63,500 Cr Revenue $63,500
31 March, revalue the open receivable. The receivable is now worth £50,000 x 1.2550 = $62,750, so it has lost $750. Dr Unrealized FX loss $750 Cr Accounts receivable (GBP) $750
30 April, record the payment. The pounds received are worth £50,000 x 1.2800 = $64,000. The receivable's carrying amount is $62,750, so the difference of $1,250 is a realized gain. Dr Cash, GBP bank account $64,000 Cr Accounts receivable (GBP) $62,750 Cr Realized FX gain $1,250
Across the two months, the net FX result is a $500 gain: the $1,250 April gain less the $750 March loss, which equals $64,000 less the original $63,500. Some systems reverse the March revaluation on 1 April and then post a realized gain of $500 at payment. Either method gives the same total. Pick one and apply it the same way every month.
31 May, revalue the GBP bank balance. The £50,000 still sitting in the GBP account is now worth $63,250, a further $750 loss. Dr FX loss $750 Cr Cash, GBP bank account $750
Revaluation is the step that turns ASC 830-20-35-2 into a routine. Add it to your five-day monthly close checklist after bank reconciliations and before you review the income statement. A workable sequence is:
Faster collection also reduces exposure, since an invoice collected in 30 days carries less rate risk than one collected in 90. Our page on accounts receivable services for small businesses covers collection routines that also help here. Companies that want to hedge or reprice for currency risk can read our guide to currency risk and transfer pricing during global expansion.
ASC 830 asks for the rate at the transaction date and the current rate at each balance sheet date, and leaves the data source to you. Auditors and the IRS both look for a rate you can document and repeat. Common sources include:
The IRS lists Treasury, the Federal Reserve and other public sources on its foreign currency and exchange rates page. Write down which source you use, at what time of day, and who approves manual overrides. If your team still converts amounts in a spreadsheet, our comparison of Excel and accounting software explains why a ledger with native currency fields leaves a better trail.
Both major small-business ledgers support multi-currency bookkeeping, with different limits.
QuickBooks Online. Intuit's multicurrency help article says the feature is available in QuickBooks Online Essentials, Plus and Advanced, and Simple Start users can't use it. It states that "Once Multicurrency is on, you can no longer turn it off," and that "once multicurrency is enabled, you can no longer change your home currency." Exchange rates update automatically every four hours, and you can enter your own rates. Each customer or vendor carries a single currency, and QuickBooks Bill Pay and QuickBooks Payments are not compatible with the feature.
For month-end, QuickBooks uses home currency adjustments. Intuit's revaluation article explains that these "change the home currency value of your foreign balances, recalculating them based on a new rate," with the result showing on receivables and payables "as an unrealized gain or loss" and on bank accounts as a realized gain or loss. You run it from Settings, then Currencies, then Revalue Currency.
Xero. Xero's multi-currency product page says multi-currency is available on the Established plan in the US and that Xero "supports over 160 currencies." It offers hourly exchange rate updates, lets you override the rate on an individual transaction, and allows foreign currency bank accounts to be added once the feature is on. The same page recommends reviewing unrealized currency gains and losses before period-end close and refers to a currency revaluation feature for month-end.
| Feature | QuickBooks Online | Xero (US) |
|---|---|---|
| Plans with multicurrency | Essentials, Plus, Advanced | Established |
| Can it be turned off | No | Not stated on Xero's page; confirm before enabling |
| Rate updates | Every 4 hours, manual entry allowed | Hourly, override per transaction |
| Month-end tool | Revalue Currency (home currency adjustment) | Currency revaluation |
| Notable limits | One currency per customer or vendor; Bill Pay and Payments not compatible | Requires plan upgrade from Early or Growing |
Groups running several entities should also compare consolidation limits. Our QuickBooks vs Xero multi-entity comparison covers that side.
The IRS states: "You must express the amounts you report on your U.S. tax return in U.S. dollars." Under Internal Revenue Code section 985, the functional currency is the dollar, except for certain qualified business units (QBUs). A QBU's functional currency is the currency of the economic environment in which a significant part of its activities is conducted and which it uses to keep its books and records (26 U.S.C. 985).
The IRS's general rule is to "use the exchange rate prevailing (i.e., the spot rate) when you receive, pay or accrue the item." It also says "The Internal Revenue Service has no official exchange rate" and "Generally, it accepts any posted exchange rate that is used consistently" (IRS yearly average currency exchange rates).
The same page publishes yearly average rates. To convert foreign currency to dollars, you divide the foreign amount by the rate. The 2025 table, used for returns filed in 2026, shows 0.886 for the euro and 0.759 for the pound. An illustrative €10,000 of income converts to about $11,287 (10,000 / 0.886). As practitioner guidance, the yearly average suits income and expenses spread evenly through the year, such as foreign wages or small recurring costs. A business that books invoices in an accounting system already has spot rates on each transaction and should keep using them for tax.
Section 988 governs foreign currency gains and losses for tax. A section 988 transaction includes accruing an item of income or expense that will be paid or received later, so an ordinary foreign currency receivable or payable qualifies. The statute says the gain or loss "shall be computed separately and treated as ordinary income or loss," so it is taxed at ordinary rates and does not qualify for capital gain treatment (26 U.S.C. 988).
The tax measurement runs from the booking date, "the date on which accrued or otherwise taken into account," to the payment date, "the date on which the payment is made or received." In the worked example, the section 988 gain is $500 ($64,000 received less $63,500 booked), recognized when the customer paid in April. As guidance, an unrealized book gain or loss on an item still open at the tax year-end is usually a book-tax difference that reverses on settlement. Larger filers show it on the Schedule M-3 book-tax reconciliation.
Foreign bank accounts and foreign entities bring separate information returns. Our guides to FBAR filing on FinCEN Form 114 and Form 5471 filing requirements explain when a GBP or EUR bank account or a foreign subsidiary triggers them.
What is the difference between functional currency and reporting currency? The functional currency is the currency of the primary economic environment where the entity generates and spends cash. The reporting currency is the one the statements are presented in. For a single US company, both are usually the dollar.
What is the difference between realized and unrealized FX gains? An unrealized gain or loss is the change in value of an open balance at a reporting date. A realized gain or loss arises when the item is settled. Under US GAAP both go to net income.
Can I use the IRS yearly average exchange rate for my business? The IRS's general rule is the spot rate when an item is received, paid or accrued, and it accepts any posted rate used consistently. Invoice-level transactions are better translated at their own spot rates. Confirm the approach with your tax preparer.
Is a foreign exchange gain taxed as a capital gain? Section 988 gains and losses, which include those on foreign currency receivables and payables, are generally ordinary income or loss.
Can I turn off multicurrency in QuickBooks Online? No. Intuit states that once multicurrency is on it cannot be turned off, and the home currency can no longer be changed.
Madras Accountancy provides bookkeeping, month-end close, tax preparation and CFO advisory support for US businesses and CPA firms, including clients who invoice, pay and bank in more than one currency. To review your multi-currency setup, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



