

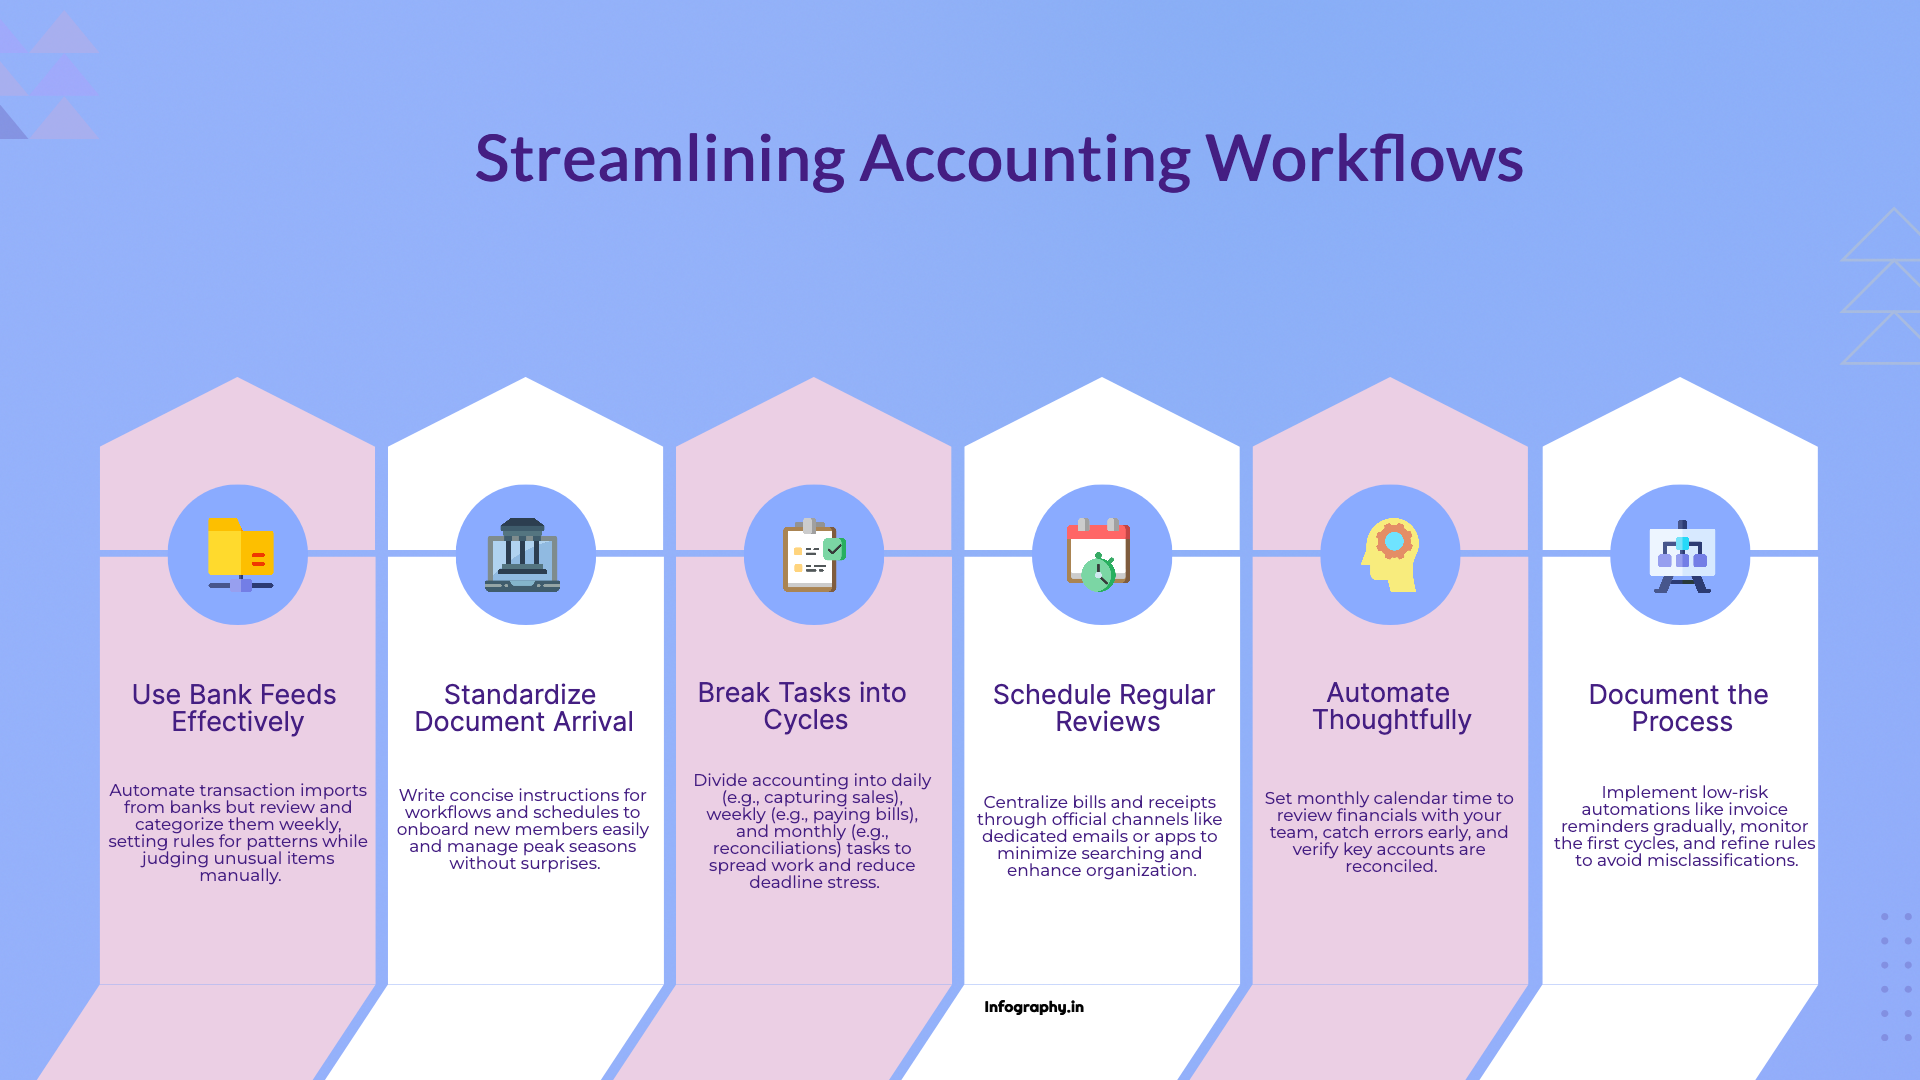

A small business bookkeeping checklist splits the accounting work into fixed cycles: a few minutes each day to capture sales, receipts and invoices, a weekly block for bills, collections and the bank feed, a monthly close with full reconciliations and a review of the reports, and a short list of quarterly and year-end tax tasks. Spreading the work this way stops the month-end scramble and catches errors while they are still small.
This guide turns that rhythm into a working small business bookkeeping checklist you can print, assign and adapt. It also covers the 2026 rules that change what you track during the year, such as the higher Form 1099-NEC threshold and the payroll tax deposit schedules in the current IRS employer guide. The goal is a routine that runs in the background so your books are ready when a lender, investor or tax preparer asks for them.
Many owners describe their accounting process with words like "fire drill" and "last minute." The work arrives in bursts around deadlines, documents go missing between email threads and text messages, and the same mistakes repeat each year. The fix is to decide which tasks happen on which schedule, write them down, and let software handle the repeatable parts.
The IRS gives a useful summary of why this matters. It says that "good records will help you monitor the progress of your business, prepare your financial statements, identify sources of income, keep track of deductible expenses, keep track of your basis in property, prepare your tax returns, and support items reported on your tax returns." The same page notes that you "may choose any recordkeeping system suited to your business that clearly shows your income and expenses," which leaves the choice of software to you.
The U.S. Small Business Administration makes a similar point in its finance guidance, telling owners to "ensure that someone can manage" accounts receivable, accounts payable, available cash, bank reconciliation and payroll. A checklist is the simplest way to make sure each of those has a named owner and a date.
Before you build the routine, check that your accounts are set up to support it. A clean, consistent account structure makes every later step faster, and our guide to building a strong chart of accounts explains how to set one up.
The table below is a starting template. Adjust the frequency to your transaction volume: a business with a few dozen transactions a month can fold the daily tasks into the weekly block, while a busy retailer may need daily reconciliation of card deposits.
| Cycle | Tasks | Typical owner |
|---|---|---|
| Daily | Record sales and deposits; issue invoices; capture receipts in one shared app; enter incoming vendor bills | Owner or office staff |
| Weekly | Categorize the bank and card feeds; schedule bill payments; follow up on overdue invoices; check the cash balance against upcoming payroll and bills | Bookkeeper |
| Monthly | Reconcile every bank, card and loan account; review receivables and payables aging; post adjusting entries; review the profit and loss statement and balance sheet; make payroll tax deposits if you are a monthly depositor | Bookkeeper, reviewed by owner or accountant |
| Quarterly | Calculate and pay estimated taxes; file payroll returns; file sales tax returns where required; compare results with budget | Accountant or tax preparer |
| Year-end | Confirm W-9s and file 1099s; reconcile payment platform 1099-K forms to recorded sales; count inventory if you carry it; assemble the tax package; archive records | Accountant with bookkeeper |
Assign each line to a person and keep the list where the team can see it, even as one page taped next to a desk.
Daily work should take minutes, and its only purpose is to get every transaction and document into the system the day it happens.
Centralizing input saves hours of hunting later, and it makes it far easier to answer questions from auditors, lenders or your own management team. If you still track sales and expenses in spreadsheets, our comparison of Excel and accounting software for small businesses explains what you gain from bank feeds and receipt capture.
Most modern accounting systems pull transactions from your bank and card accounts automatically. That saves a great deal of manual entry, though the feed still needs a person to review it.
Set aside one or two fixed slots each week to categorize new transactions so they do not pile up. Create bank rules where patterns are obvious, such as mapping a recurring software subscription to the same expense account every month. Then review anything new or unusual that needs a human decision, such as a large transfer, an owner draw or a refund.
The rest of the weekly block covers cash in and cash out:
The monthly close is the core of any small business bookkeeping checklist. Aim to finish it within the first ten business days of the following month.
Put a recurring review meeting on the calendar with your bookkeeper or accountant for this step. Catching a mistake after one month is far easier than digging back through a full year to find out why the cash account no longer matches the bank. Our list of common small business accounting mistakes shows the errors a monthly review usually catches.
Here is how a typical reconciliation at the end of September 2026 works for a small service business. The bank statement shows an ending balance of $18,420.00. The general ledger shows a cash balance of $19,265.00.
| Item | Amount |
|---|---|
| Bank statement ending balance | $18,420.00 |
| Add: deposit in transit (recorded Sept 30, credited by the bank Oct 1) | $2,150.00 |
| Less: outstanding checks | ($1,375.50) |
| Adjusted bank balance | $19,194.50 |
| Ledger cash balance | $19,265.00 |
| Less: monthly bank service fee not yet recorded | ($25.00) |
| Less: customer check returned for insufficient funds | ($45.50) |
| Adjusted book balance | $19,194.50 |
Both sides agree at $19,194.50. The two book-side items need journal entries: the fee goes to bank charges, and the returned check goes back to the customer's receivable balance so someone follows up on it. If the two adjusted balances did not agree, the difference would point to a missing, duplicated or mistyped transaction that needs to be found before the month is closed.
Each quarter, the books feed into tax filings and a broader review.
With a steady routine in place, most year-end work is already done. The remaining items are mostly about information returns and the tax package.
Form 1099-NEC at the new threshold. The IRS now tells payers to report nonemployee compensation for "payments totaling $600 ($2,000 for payments made after December 31, 2025)." For 2026 payments, that means fewer contractors will need a form, but you still need a W-9 on file from each one at onboarding so you can tell who crosses the line. Our guide to the 2026 1099 reporting threshold covers the related changes to Forms 1099-MISC and 1099-K.
Form 1099-K from payment platforms. The IRS says payment apps and online marketplaces must report when your payments for goods or services "total over $20,000 in more than 200 transactions," and that they may send a form for lower amounts. Whether or not a form arrives, all business income is reportable, so reconcile platform payouts to recorded sales during the year.
Inventory, fixed assets and the tax package. Count inventory if you carry it, update the fixed asset list for purchases and disposals, and hand your tax preparer a reconciled trial balance with supporting schedules. If the routine slipped during the year, our checklist for bookkeeping cleanup before tax season covers the catch-up work.
Record retention. The IRS sets different retention periods depending on the situation. The general rule is three years, while it says to "keep records for 7 years if you file a claim for a loss from worthless securities or bad debt deduction" and to keep employment tax records for at least 4 years after the date that the tax becomes due or is paid, whichever is later. Archive each closed year in a labeled folder so documents are easy to retrieve.
A checklist only helps if it survives busy months and staff changes. Four habits keep it working.
Automate carefully. Start with low-risk tasks such as invoice reminders, recurring journal entries for routine accruals and scheduled vendor payments. Watch the first few cycles closely and adjust rules early, before a misclassified expense repeats for three months.
Document the process. Write short instructions in plain language: "On Mondays we categorize the bank feed. By the 10th we close the prior month. Vendor bills go to this address." Short written steps make it easier to train new staff and to bring in help during busy seasons.
Separate duties where you can. The person who enters a bill should not be the only person who approves and pays it. In a very small business, the owner reviewing the bank reconciliation each month gives much of the same protection.
Get help when the routine slips. If the monthly close keeps running late or reconciliations fall behind, outside support often costs less than catching up later. Our page on outsourced bookkeeping services for small businesses explains how that arrangement usually works.
How much time does a small business bookkeeping checklist take each week? It depends on transaction volume. A business with a few hundred transactions a month that keeps up daily capture and a weekly bank feed review usually needs a few hours a week, plus a longer block for the monthly close. Falling behind multiplies the time because transactions have to be researched from memory.
What is the most important task on the checklist? The monthly reconciliation of every bank, card and loan account. It is the step that proves the books match outside records, and it catches missing transactions, duplicates and fraud early.
Do I need to send a 1099-NEC to every contractor in 2026? No. For payments made after December 31, 2025, the IRS reporting threshold for nonemployee compensation is $2,000 for the calendar year. Collect a W-9 from every contractor anyway so you can track totals and file for those who cross the threshold.
How long should a small business keep bookkeeping records? The IRS general rule is three years, with longer periods in specific cases: seven years for worthless securities or bad debt claims, six years if you leave out income that is more than 25 percent of the gross income shown on your return, and at least four years for employment tax records.
Can bank feeds replace a bookkeeper? Bank feeds remove most manual data entry, but someone still has to categorize unusual items, reconcile accounts, post adjustments and review the reports. Rules in the software help with routine transactions and need periodic checking.
Madras Accountancy provides bookkeeping, month-end close, reconciliation and tax preparation support for US businesses and the CPA firms that serve them. If you want help setting up a bookkeeping routine or keeping one on schedule, contact our team to talk through your needs.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



