



If the average guest stay at your rental is 7 days or less, the IRS does not treat it as a "rental activity" under the passive loss rules. If you also materially participate, losses (often boosted by cost segregation and 100% bonus depreciation) can offset wages and business income. The savings depend on your numbers; there is no standard percentage.
This is a legitimate strategy that works when the facts support it. Many investors miss it, or lose it on audit, because they misunderstand the qualification rules or don't document their involvement.
Here's how the short-term rental rules work: the exact requirements, how depreciation fits in, and how to avoid common mistakes.
Rental activities are generally passive, so losses can only offset passive income (apart from the $25,000 allowance for active participants, which phases out between $100,000 and $150,000 of modified AGI). But the passive activity rules list exceptions where an activity is not treated as a rental activity. The most important for Airbnb and Vrbo owners: the average period of customer use is 7 days or less.
When that exception applies, the property is treated like any other trade or business. If you materially participate, it is non-passive and losses can offset salary, bonuses and business profits. If you don't materially participate, the losses are still passive.
Key points:
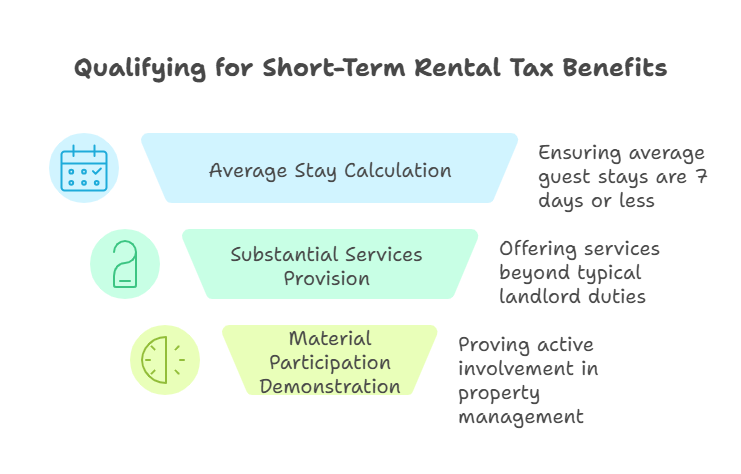
Two requirements must line up:
Requirement 1: Average stay of 7 days or less
Divide the total number of days rented by the number of separate rentals during the year. Individual stays can be longer as long as the average is 7 days or less. Keep booking records with check-in and check-out dates for every stay.
A second exception applies if the average stay is 30 days or less and you provide significant personal services (hotel-like services such as daily cleaning or meals, not just cleaning between guests). Significant services are not required for the 7-day exception. Note that rental losses here are not eligible for the $25,000 active participation allowance, because the activity is not a rental activity.
Requirement 2: Material participation
You must materially participate in the activity for the year. IRS Publication 925 lists seven tests; meeting any one is enough. The ones short-term rental owners usually rely on:
The other tests cover significant participation activities totaling more than 500 hours, material participation in 5 of the prior 10 years, personal service activities, and participation on a regular, continuous and substantial basis (which requires more than 100 hours). Your spouse's hours count toward your participation. Track time as you go using calendars or detailed logs.
Cost segregation accelerates depreciation by identifying building components with shorter recovery periods (5, 7 or 15 years) instead of depreciating everything over the building's life. Note that a property used mostly for stays under 30 days may not meet the definition of residential rental property and may need to be depreciated over 39 years rather than 27.5; confirm this with your CPA.
Under the One Big Beautiful Bill Act, 100% bonus depreciation is permanent for qualified property acquired after January 19, 2025. Shorter-life components identified in a cost segregation study can be deducted in full in the year placed in service. Property acquired before that date and placed in service in 2025 is limited to 40%. See our guide to Section 179 and bonus depreciation.
Illustrative example for a $500,000 property bought in January (actual allocations depend on the engineering study):
Without cost segregation, the same $400,000 building basis over 39 years gives roughly $10,000 a year. Operating expenses (mortgage interest, taxes, insurance, utilities, cleaning, supplies) are deducted on top. If those deductions exceed rental income, the loss can offset other income when you materially participate.
Many people confuse the short-term rental exception with real estate professional status. They are different.
Real estate professional status requires more than half of your personal services to be in real property trades or businesses in which you materially participate, and more than 750 hours in those businesses. That is very difficult for anyone with a full-time job. It lets rental real estate losses be non-passive if you also materially participate in the rentals.
The short-term rental exception doesn't depend on your career. If the average stay is 7 days or less and you materially participate in that property, the activity is non-passive, even if you keep your day job.
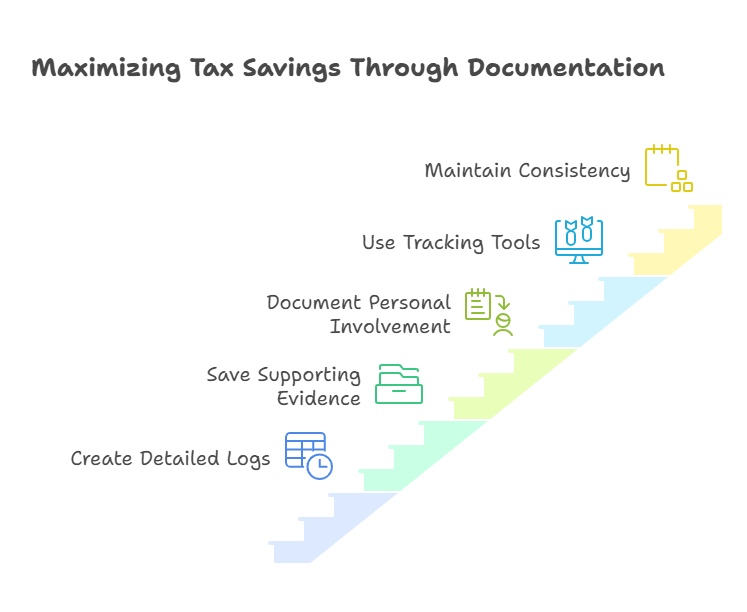
Documentation either proves your case in an audit or costs you the deductions plus possible penalties.
Keep a contemporaneous log of every hour: date, task and time spent. Typical tasks include booking management (inquiries, reservations, check-ins), property work (repairs, inspections, supplies), and marketing (listings, photos, pricing). Investor-type activities, such as reviewing financial statements without being involved in day-to-day management, generally don't count.
Save supporting evidence: calendar entries, messages with guests and vendors, receipts, photos and bank statements. If you use cleaners or a manager and rely on the 100-hour test, you need to show their hours were not more than yours, so keep records of their time too.
Property management software or a spreadsheet both work. Consistency matters: reconstructing hours after an audit notice is far weaker than records kept as you go.
Mistake 1: Claiming non-passive losses without meeting the requirements. If you can't show the average stay was 7 days or less and that you materially participated, the IRS will treat the losses as passive and disallow them against wages.
Mistake 2: Poor time tracking. Claiming 100+ hours without real-time records, or ignoring the cleaner's and co-host's hours, is a common way to lose the 100-hour test.
Mistake 3: Cost segregation without a proper study. Guessing at allocations is hard to defend. A study prepared by qualified engineers or specialists provides the support.
Mistake 4: Too much personal use. If your personal use exceeds the greater of 14 days or 10% of the days rented at fair rental price, the property is treated as a residence and deductions are limited to rental income, so you can't create a loss.
Year one usually gives the largest deduction because of bonus depreciation. Later years continue with regular depreciation on the building and operating expenses. You must meet the average-stay and material participation tests separately each year.
At sale, depreciation is recaptured. Gain attributable to depreciation on 5-, 7- and 15-year property (Section 1245 property) is generally taxed as ordinary income; depreciation on the building is taxed at up to 25%; remaining gain is taxed at capital gains rates. A 1031 exchange can defer the gain on the real property, but replacement property takes a carryover basis, so it does not "reset" depreciation, and recapture can still apply to personal property that is not real property.
You need enough income to use the losses. The benefit is largest for taxpayers in the higher brackets (federal rates run from 10% to 37%), where each dollar of deduction saves 32 to 37 cents.
You must genuinely be involved in managing the property. Overstating participation invites IRS problems. Work with experienced tax professionals to structure involvement legitimately.
Think about long-term goals. Short-term rentals require ongoing effort: guest communication, frequent turnovers and constant marketing. Also check local short-term rental rules and permits before buying. If you want income you can largely ignore, traditional rentals may suit you better despite smaller tax benefits.
For the passive loss rules, the key test is an average guest stay of 7 days or less. A property with an average stay of 30 days or less also qualifies if you provide significant personal services. Either way, the activity is not treated as a rental activity.
Yes, if the property meets the average-stay exception and you materially participate under one of the seven IRS tests, such as more than 500 hours, or more than 100 hours and not less than anyone else.
It depends on the property and your tax bracket. A cost segregation study moves part of the building's cost into 5-, 7- and 15-year property, which is eligible for 100% bonus depreciation if acquired after January 19, 2025. The tax saved equals the extra deduction multiplied by your marginal rate.
No. Real estate professional status (more than 750 hours and more than half your working time in real estate) is not required. You need the average-stay exception plus material participation in the short-term rental.
Hands-on work: managing bookings, coordinating cleaning and maintenance, buying supplies and furniture, responding to guests and marketing. Your spouse's hours count. Pure investor activities generally do not. Document with calendars, messages and receipts.
Bonus depreciation is 100% for qualified property acquired after January 19, 2025, and the One Big Beautiful Bill Act made it permanent. After a cost segregation study identifies 5-, 7- and 15-year assets, you can deduct their full cost in the year placed in service. The building structure itself is not eligible.
Once the average stay exceeds 7 days (and the 30-day services exception doesn't apply), the property becomes a rental activity and is generally passive. Suspended passive losses carry forward and can be used against passive income or when you dispose of the property in a fully taxable transaction.
We've processed 50,000+ tax returns since 2015, including cost segregation, material participation documentation and tax planning for real estate investors. We work as an offshore partner to U.S. CPA firms, reducing costs while maintaining quality.
The short-term rental rules deliver legitimate savings when the facts fit: an average stay of 7 days or less plus material participation lets depreciation losses offset other income.
Document everything from day one. Track hours, save communications and work with tax professionals who understand the details.
About Madras Accountancy: Since 2015, we've served as offshore partners to U.S. CPA firms, processing 50,000+ tax returns with cost segregation analysis, tax planning and compliance services for real estate investors.
For CPA firms: Madras Accountancy supports U.S. CPA firms with real estate and rental property accounting. See our real estate and property management accounting services.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



