


Here is a rule that catches almost everyone off guard. When a lender forgives money you owe, the forgiven amount usually counts as income, and you may owe tax on it. Settle a $20,000 credit card balance for $8,000, and that $12,000 the creditor wiped out can land on your tax return as cancellation of debt income.
It feels backward. You were struggling with debt, someone gave you a break, and now the IRS wants a cut of the relief. But the logic is simple once you see it: you got to use money you never paid back, so the tax code treats that unpaid amount as a financial gain. The good news is that several exclusions can shrink or erase the bill, and knowing them ahead of time is what separates a nasty surprise from a non-event.
This guide walks through how canceled debt is taxed, the form that reports it, the exclusions worth knowing, and what quietly changed for 2026.
Cancellation of debt income, often shortened to COD income, is the amount of a debt a lender forgives, discharges, or writes off for less than you owed. Under Section 61 of the Internal Revenue Code, discharge of indebtedness is listed right there in the definition of gross income, alongside wages and interest. So unless a specific rule says otherwise, canceled debt is taxable and gets taxed at your ordinary income rates.
You will also see this written as "cancelation of debt" with one L. Same thing, just a common alternate spelling. Whichever way it shows up, the cancellation of indebtedness is treated as income to the debtor in the year the debt is canceled.
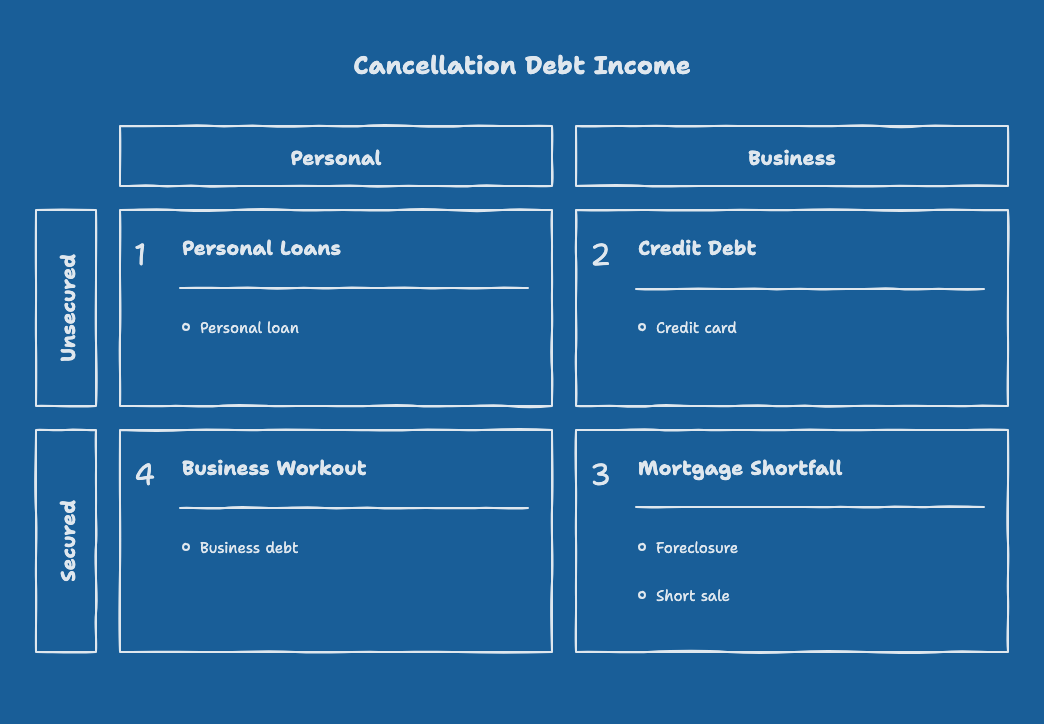
A few everyday examples of what can trigger COD income: a credit card debt settled for less than the balance, a personal loan a lender gives up on, a mortgage shortfall forgiven after a foreclosure or short sale, or a business debt reduced in a workout. Each one can create income from the cancellation of debt.
Most people meet their canceled debt through a piece of mail. When a creditor forgives $600 or more, they are generally required to file Form 1099-C, Cancellation of Debt, with the IRS and send you a copy. Box 2 shows the amount of canceled debt.
Two things trip people up here. First, the IRS gets the same form you do, so ignoring it is not an option. Second, you can still owe tax on canceled debt even if no 1099-C ever arrives. If the debt was discharged and no exclusion applies, you are supposed to report the amount on Schedule 1 of Form 1040, line 8c, as other income. A missing form does not make the income disappear.
If part or all of the canceled debt is taxable, it flows through as ordinary income. Nonbusiness debt goes on that Schedule 1 line, and business debt goes on the relevant business schedule.
Now for the part that actually saves money. Section 108 of the tax code lets you exclude canceled debt from income in specific situations. The two that help individuals most often are bankruptcy and insolvency.
Bankruptcy. If the debt is discharged in a Title 11 bankruptcy case, the entire amount of COD income is excluded. Nothing gets taxed.
Insolvency. This is the quiet hero, and most people have never heard of it. You are insolvent when your total liabilities are more than the fair market value of everything you own, measured right before the debt was canceled. You can exclude canceled debt up to the amount you were insolvent. Say your debts topped your assets by $15,000 and a creditor forgave $10,000. The whole $10,000 can be excluded. If they had forgiven $20,000, you could shield $15,000 and pay tax on the remaining $5,000. The IRS provides an insolvency worksheet in Publication 4681 to run the math, and you keep it with your records rather than filing it.
Two more exclusions cover narrower cases: qualified farm indebtedness and qualified real property business indebtedness (QRPBI) for certain business real estate.
To claim any of these, you attach Form 982, Reduction of Tax Attributes Due to Discharge of Indebtedness, to your return, check the box for the exclusion you are using, and enter the excluded amount. Here is the catch worth understanding: the exclusion is rarely free. In exchange, you usually have to reduce certain tax attributes, meaning things like net operating losses, credits, and the basis of your assets, in a set order. Think of it less as forgiveness and more as a trade. You skip the tax now, and give up some future tax benefits.
One more distinction, because it matters. Exceptions are different from exclusions. Some canceled amounts were never income to begin with, like a debt a family member forgave as a genuine gift, or a seller reducing what you owe on something you bought (a purchase price adjustment). Those fall out before you ever reach the exclusions, and they do not cost you any tax attributes.
This is where advice from a year or two ago can steer you wrong, so it is worth slowing down.
Student loans are taxable again. From 2021 through 2025, the American Rescue Plan Act made most student loan forgiveness federally tax-free. That provision was always temporary, and the One Big Beautiful Bill Act did not extend it. So for discharges on or after January 1, 2026, student loan forgiveness is generally back to being cancellation of debt income subject to federal tax. The borrowers most affected are those hitting the end of an income-driven repayment plan, since that forgiveness no longer has a shield. Some programs keep their own permanent exclusions, including Public Service Loan Forgiveness, Teacher Loan Forgiveness, and discharges for death or total and permanent disability. If your forgiven loan is taxable, insolvency and Form 982 can still cut the bill, and state rules vary, so the same loan can be tax-free federally but taxed by your state.
The home mortgage exclusion lapsed. For years, homeowners could exclude forgiven mortgage debt on a main home under the qualified principal residence indebtedness rule. Per IRS Publication 4681, that exclusion only covers debt discharged before January 1, 2026, or under a written arrangement entered into before that date, capped at $750,000 ($375,000 if married filing separately). Congress has revived this one several times in the past, so it could come back, but as the rules stand a 2026 foreclosure or short sale shortfall does not get that automatic protection. Bankruptcy and insolvency are still on the table for those homeowners.
Losing property to the lender adds a wrinkle, because you are treated as having sold it. What happens next depends on the kind of loan.
With recourse debt, where you are personally on the hook, a foreclosure can produce two separate things: a gain or loss on the property based on its fair market value, plus cancellation of debt income for any shortfall the lender forgives above that value. With nonrecourse debt, where the lender's only remedy is taking the property, the full balance is treated as the sale price. There is no separate COD income, just a gain or loss. Knowing which type of debt you had changes the entire tax picture, so it is one of the first things to pin down.
Canceled debt is one of those areas where a little planning beats a lot of cleanup. If you are heading into a debt settlement, a foreclosure, or a loan discharge, the smart moves are to figure out whether you will be insolvent before the debt is canceled, hold on to statements that prove your assets and liabilities on that date, and confirm which exclusion fits before you file. A single 1099-C can look terrifying and still end up costing nothing once the insolvency math is done.
The rules are technical and change more often than most tax provisions, especially now. If a client is facing forgiven debt this year, Madras Accountancy can run the insolvency numbers, handle the Form 982 reporting, and make sure the exclusion holds up if the IRS ever asks about it.
1. Is cancellation of debt always taxable? No. Canceled debt is taxable by default, but exclusions for bankruptcy, insolvency, qualified farm debt, and certain business real estate debt can reduce or eliminate the tax. Some amounts, like a forgiven gift, are never income at all.
2. What is a Form 1099-C? It is the form a creditor files when they forgive $600 or more of debt. You get a copy, the IRS gets a copy, and box 2 shows the amount of canceled debt. Receiving one does not automatically mean you owe tax, but you do have to address it on your return.
3. What if I never received a Form 1099-C? You are still responsible for reporting taxable canceled debt. If the debt was discharged and no exclusion applies, report it on Schedule 1 of Form 1040, line 8c, even without the form.
4. How does the insolvency exclusion work? If your liabilities were greater than the fair market value of your assets right before the cancellation, you can exclude canceled debt up to the amount you were insolvent. You claim it on Form 982 and reduce your tax attributes for the excluded amount.
5. Is forgiven credit card debt taxable? Usually yes. If you settle a credit card debt for less than you owe, the forgiven portion is generally cancellation of debt income, unless you were insolvent or bankrupt, or another exclusion applies.
6. Is student loan forgiveness taxable in 2026? Generally yes at the federal level. The temporary exclusion from the American Rescue Plan Act expired at the end of 2025 and was not extended, so forgiveness in 2026 is usually taxable. Death, total and permanent disability, Public Service Loan Forgiveness, and Teacher Loan Forgiveness keep their own separate exclusions.
7. What happened to the exclusion for forgiven mortgage debt on my home? The qualified principal residence indebtedness exclusion covers discharges before January 1, 2026, or under a written arrangement made before that date. For discharges after that, unless Congress revives it, you would look to bankruptcy or insolvency instead. Check IRS Topic 431 for the current status.
8. What is the difference between recourse and nonrecourse debt in a foreclosure? With recourse debt you can have both a gain or loss on the property and separate COD income for any forgiven shortfall. With nonrecourse debt the whole balance is treated as the sale price, so there is a gain or loss but no separate cancellation of debt income.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



