


Picture a client calling you in March. She has her Schedule K-1 open, she sees a capital account number in Item L, and she asks a fair question: "So this is my basis, right?"
It is not. That one mix-up causes more partnership tax headaches than almost any other, and it is easy to fix once you see how the numbers are built. This guide walks through the partner capital account, tax basis capital and outside basis, why they rarely match, and what the IRS expects the partnership to report each tax year.
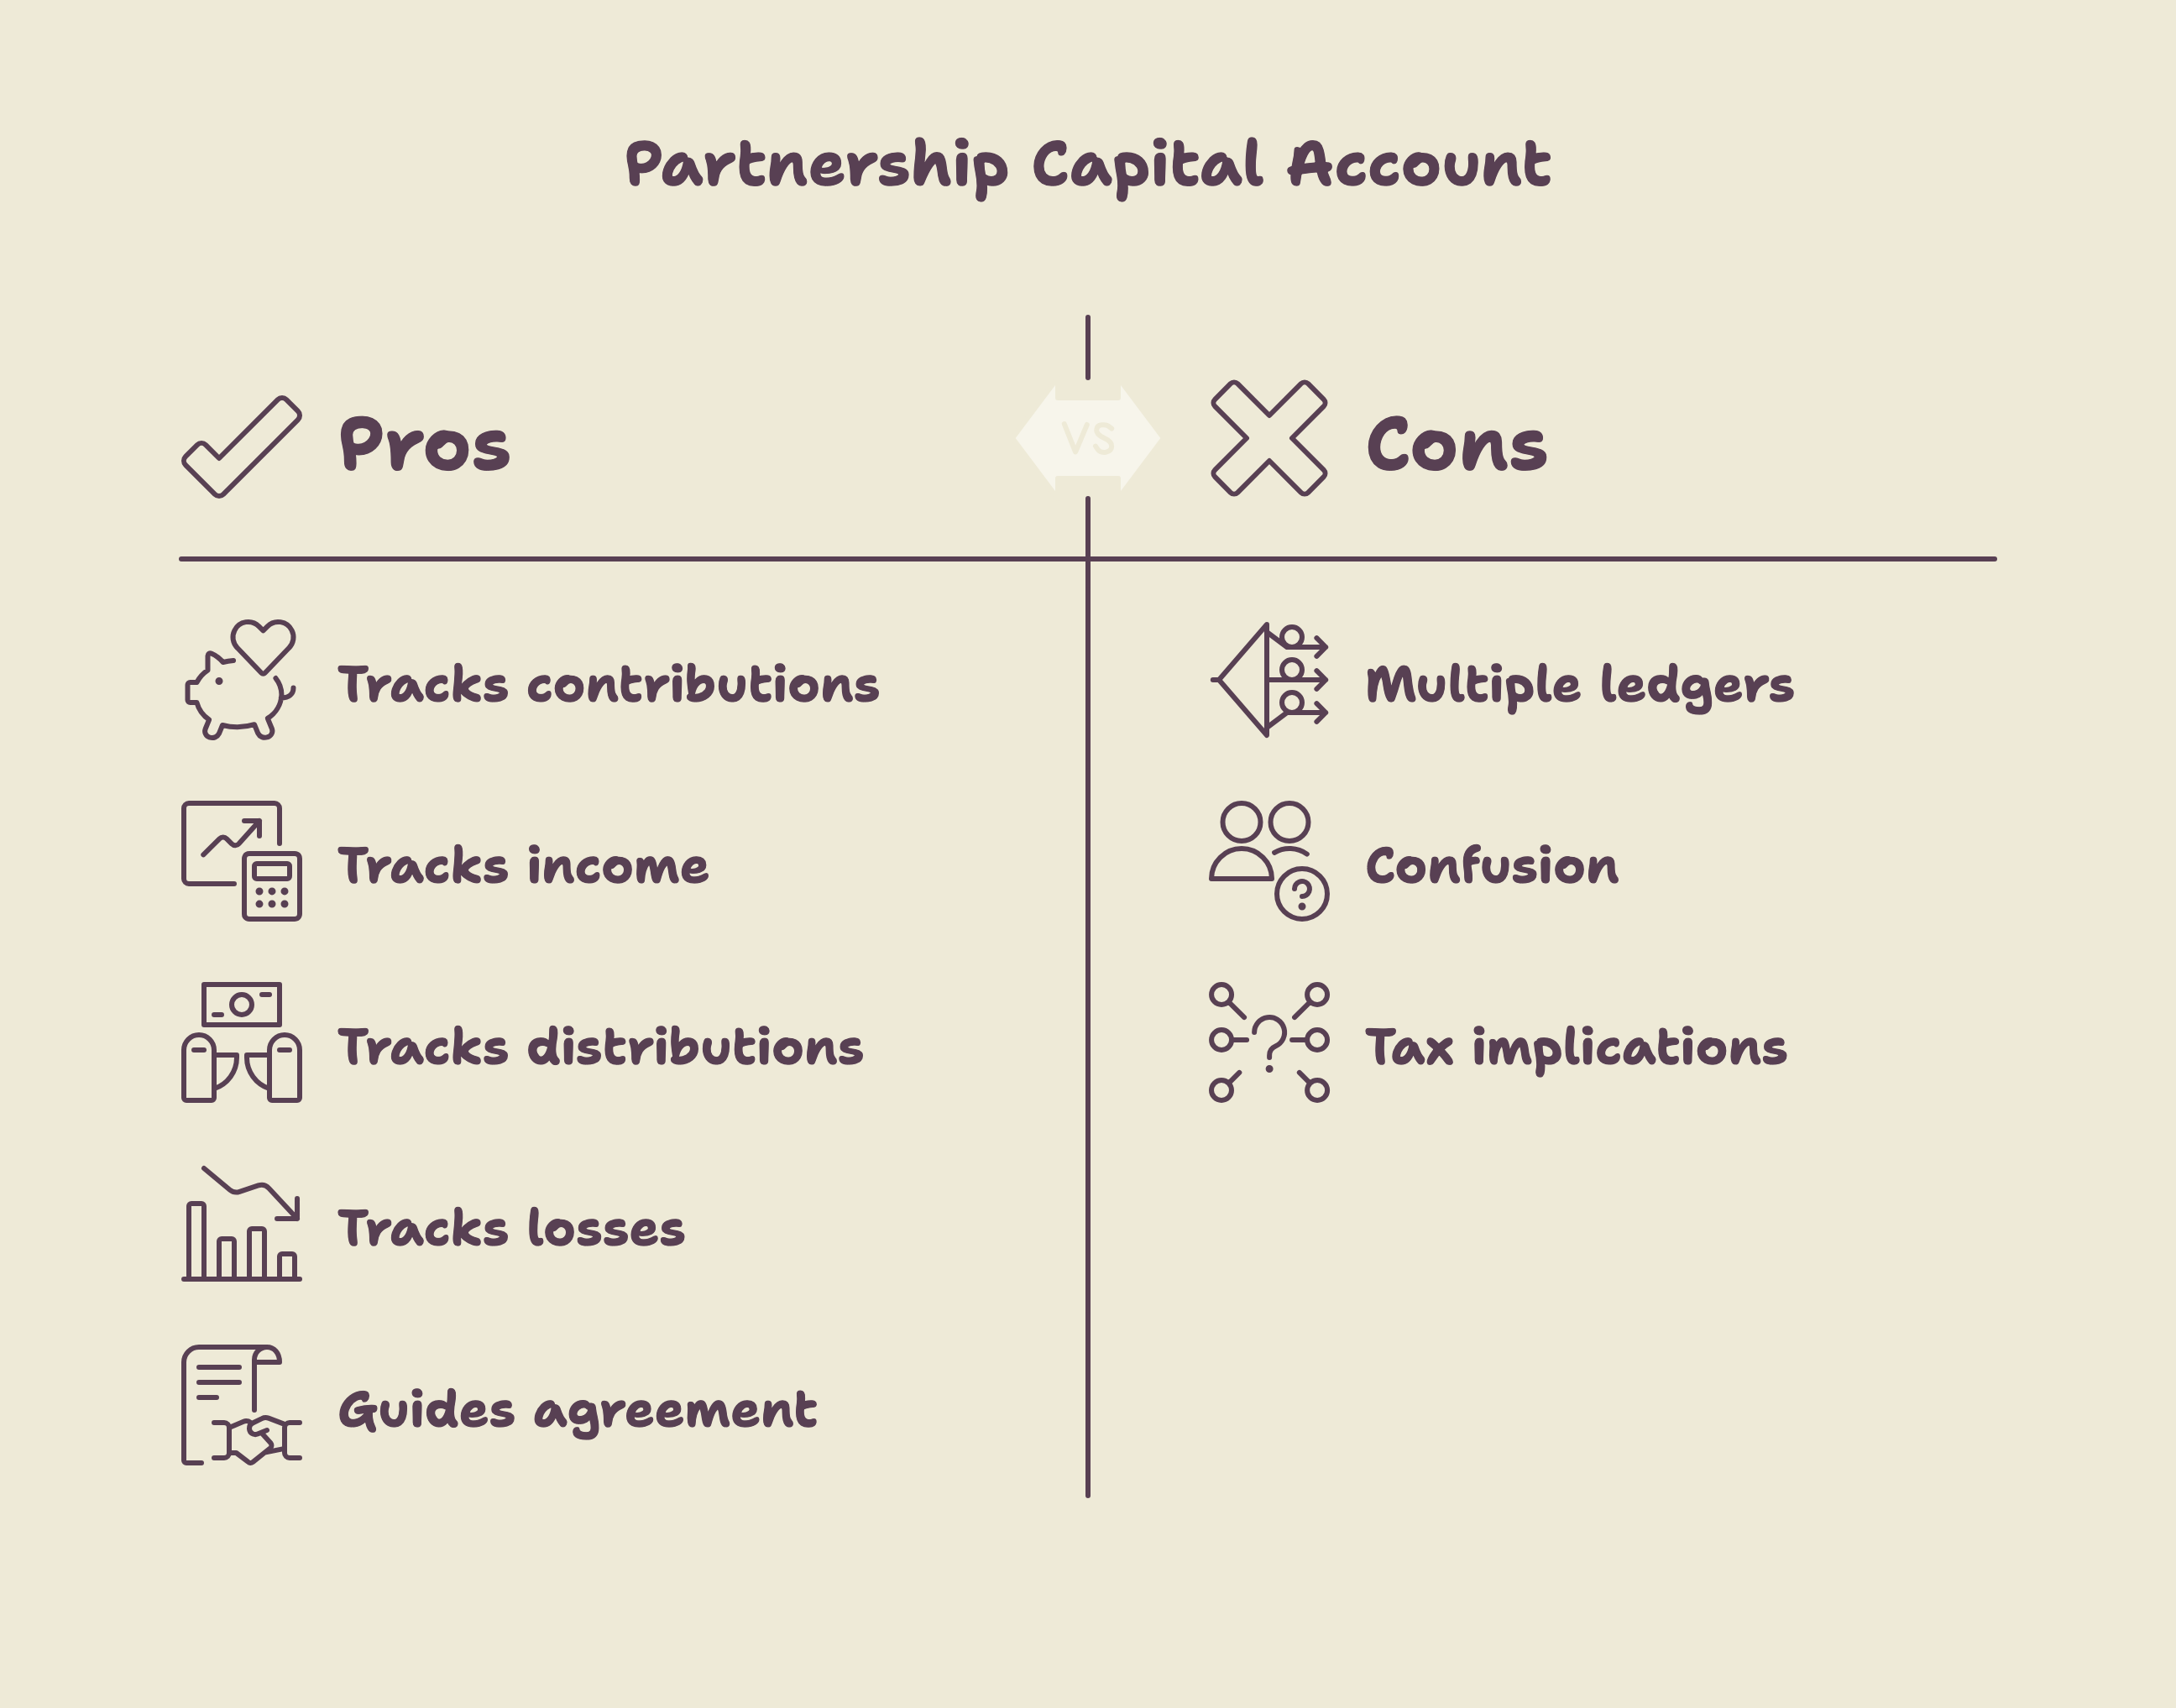
A capital account is a running tally of what each partner has put in and taken out. It goes up with cash or property contributed and with the partner's share of income. It goes down with every distribution and with the partner's share of losses. The partnership agreement decides how profits, losses and liquidation proceeds get split, so it also drives how these accounts are kept.
The confusing part is that "capital account" can point to three different ledgers. There is the book capital account, which follows GAAP or section 704(b) rules. There is the tax capital account, kept with tax numbers. And there is whatever number lands on the K-1. Most of the trouble starts when people treat these as one thing.
Tax basis capital is a capital account built from tax figures instead of book figures. Since the 2020 tax year, the Instructions for Form 1065 require every partnership to report each partner's Item L capital account using the tax basis method. GAAP, 704(b) and other methods no longer qualify for that box.
The method is called the transactional approach, and it follows the same tax principles used to figure basis. The partnership starts with the beginning capital account, adds capital contributed, adds or subtracts the partner's share of net income or loss figured for tax, subtracts withdrawals and distributions, and then handles any other increases or decreases. What remains is the ending capital account.
Two things are deliberately left out. Section 743(b) basis adjustments do not count, and neither does the partner's share of partnership liabilities. That second gap is the whole reason tax capital and outside basis drift apart.
Outside basis is your adjusted tax basis in the partnership interest. It starts like tax capital, but it also includes your share of partnership debt. Contributions, allocated income and a bigger share of liabilities push it up. Distributions, allocated losses and a smaller share of liabilities push it down.
Three rules do most of the work:
Here is the catch many partners miss. The IRS says plainly that the Item L analysis cannot be used to figure your adjusted basis. Tracking it is your job, and Regulations section 1.705-1 requires it whenever basis affects your tax liability. The Partner's Instructions for Schedule K-1 include a full basis worksheet to help.
Tax basis capital account
Outside basis
Who reports it
The partnership, in Item L of Schedule K-1
You, in your own records
Share of liabilities
Not included
Included
Can it be negative
Yes
No, the floor is zero
What it is used for
Gives the IRS a consistent view of partner capital
Limits losses, sets gain on distributions and sales
Priya joins an LLC taxed as a partnership and contributes $100,000 in cash. Her share of the partnership's debt is $30,000. For the year she is allocated $20,000 of taxable income and receives a $10,000 distribution.
Her tax capital ends the year at 110,000(100,000 plus $20,000 minus $10,000). Her outside basis ends at $140,000, which is that $110,000 plus her $30,000 share of debt.
Same partner, same year, two numbers. The gap is simply her share of liabilities, and Item K1 on her K-1 is where the partnership shows it.
Now flip the picture. After years of depreciation and debt-funded distributions, a partner's tax capital can go negative, say negative $15,000. If her share of liabilities is $40,000, her outside basis is about $25,000. So a negative capital account does not by itself mean she has run out of basis or owes tax today.
Basis is only the first gate for tax losses. The at-risk rules under section 465 come next, and they generally exclude nonrecourse debt, with an exception for qualified nonrecourse financing on real property. Item K1 splits liabilities into nonrecourse, qualified nonrecourse and recourse so you can see which ones count. Form 6198 is where you work out your at-risk basis.
Debt shifts matter too. When your share of liabilities falls, the IRS treats that drop as a deemed cash distribution under section 752. If it exceeds your basis, part of it becomes taxable. This is a good moment to loop in a tax advisor before year end, because timing is the easiest part of tax planning to get right.
The gap between book and tax shows up fastest with property contributed to the partnership. Book capital generally starts at fair market value. Tax capital starts at the partner's tax basis in that property.
Say a partner contributes land with a market value of $100,000 and a tax basis of $40,000. Book capital starts at $100,000, tax capital starts at $40,000, and the $60,000 difference is built-in gain. The partnership flags it in Items M and N of the K-1. Both ledgers stay in play, so most firms maintain the two side by side.
The reporting requirement took effect for the 2020 tax year. Partnerships that had not used the tax basis method before could figure their beginning capital accounts for 2020 with a few alternate methods, and Notice 2021-13 gave penalty relief for honest errors in those opening balances. That relief was a one time bridge. Today Item L is reported on the tax basis method every year. Before 2020, partnerships using another method had to report negative tax capital separately on line 20 of Schedule K-1, which is one reason many firms already had the data.
Partnerships that answer "Yes" to question 4 on Schedule B can skip Item L. Everyone else should get it right, because the penalties add up. Under the 2025 instructions, each incorrect or late Schedule K-1 can cost $340, and a late Form 1065 costs $255 per partner for each month, up to 12 months.
One more reminder for distribution years. Partners who receive property in a distribution file Form 7217 with their tax return, and the partnership supplies the numbers. These are the 2025 instructions used for returns filed in 2026, so check IRS.gov/Form1065 for any update.
Madras Accountancy is an offshore partner to U.S. CPA firms, supporting tax preparation, bookkeeping, audit support and more. If tax capital schedules and K-1 workpapers are squeezing your busy season, our team can take that load and hand back clean, reviewable files.
1. What is tax basis capital in a partnership? It is a partner's capital account figured with tax rules. It counts contributions, taxable income or loss and distributions, but leaves out the partner's share of liabilities.
2. Is the capital account on my K-1 the same as my outside basis? No. Outside basis includes your share of partnership liabilities and is your own record. Item L does not include liabilities.
3. How do I calculate outside basis? Start with last year's basis. Add contributions, income and increases in liabilities. Subtract distributions, losses and decreases in liabilities. The worksheet in the Partner's Instructions walks through each line.
4. Can a partnership still use GAAP for the Item L capital account? No. From the 2020 tax year on, Item L must use the tax basis method. The partnership agreement can still track book capital for economic sharing.
5. Can a capital account be negative? Tax basis capital can be negative. Outside basis cannot fall below zero.
6. What happens if a distribution is more than my outside basis? The excess is generally taxed as gain from selling your partnership interest. IRS Publication 541 covers the details.
7. Who is responsible for tracking outside basis? You are. The partnership reports Item L, but it may lack your partner level details, so keep your own yearly record.
8. What is the penalty for wrong capital account reporting? A $340 penalty per Schedule K-1 can apply for missing or incorrect information, unless the partnership shows reasonable cause.

Section 4960's 21% excise tax now reaches far more nonprofit employees. See who is a covered employee in 2026 and what changed.

The Section 45S paid family leave credit is permanent for 2026 with new options. See who qualifies, the amounts, and how to claim it.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



