

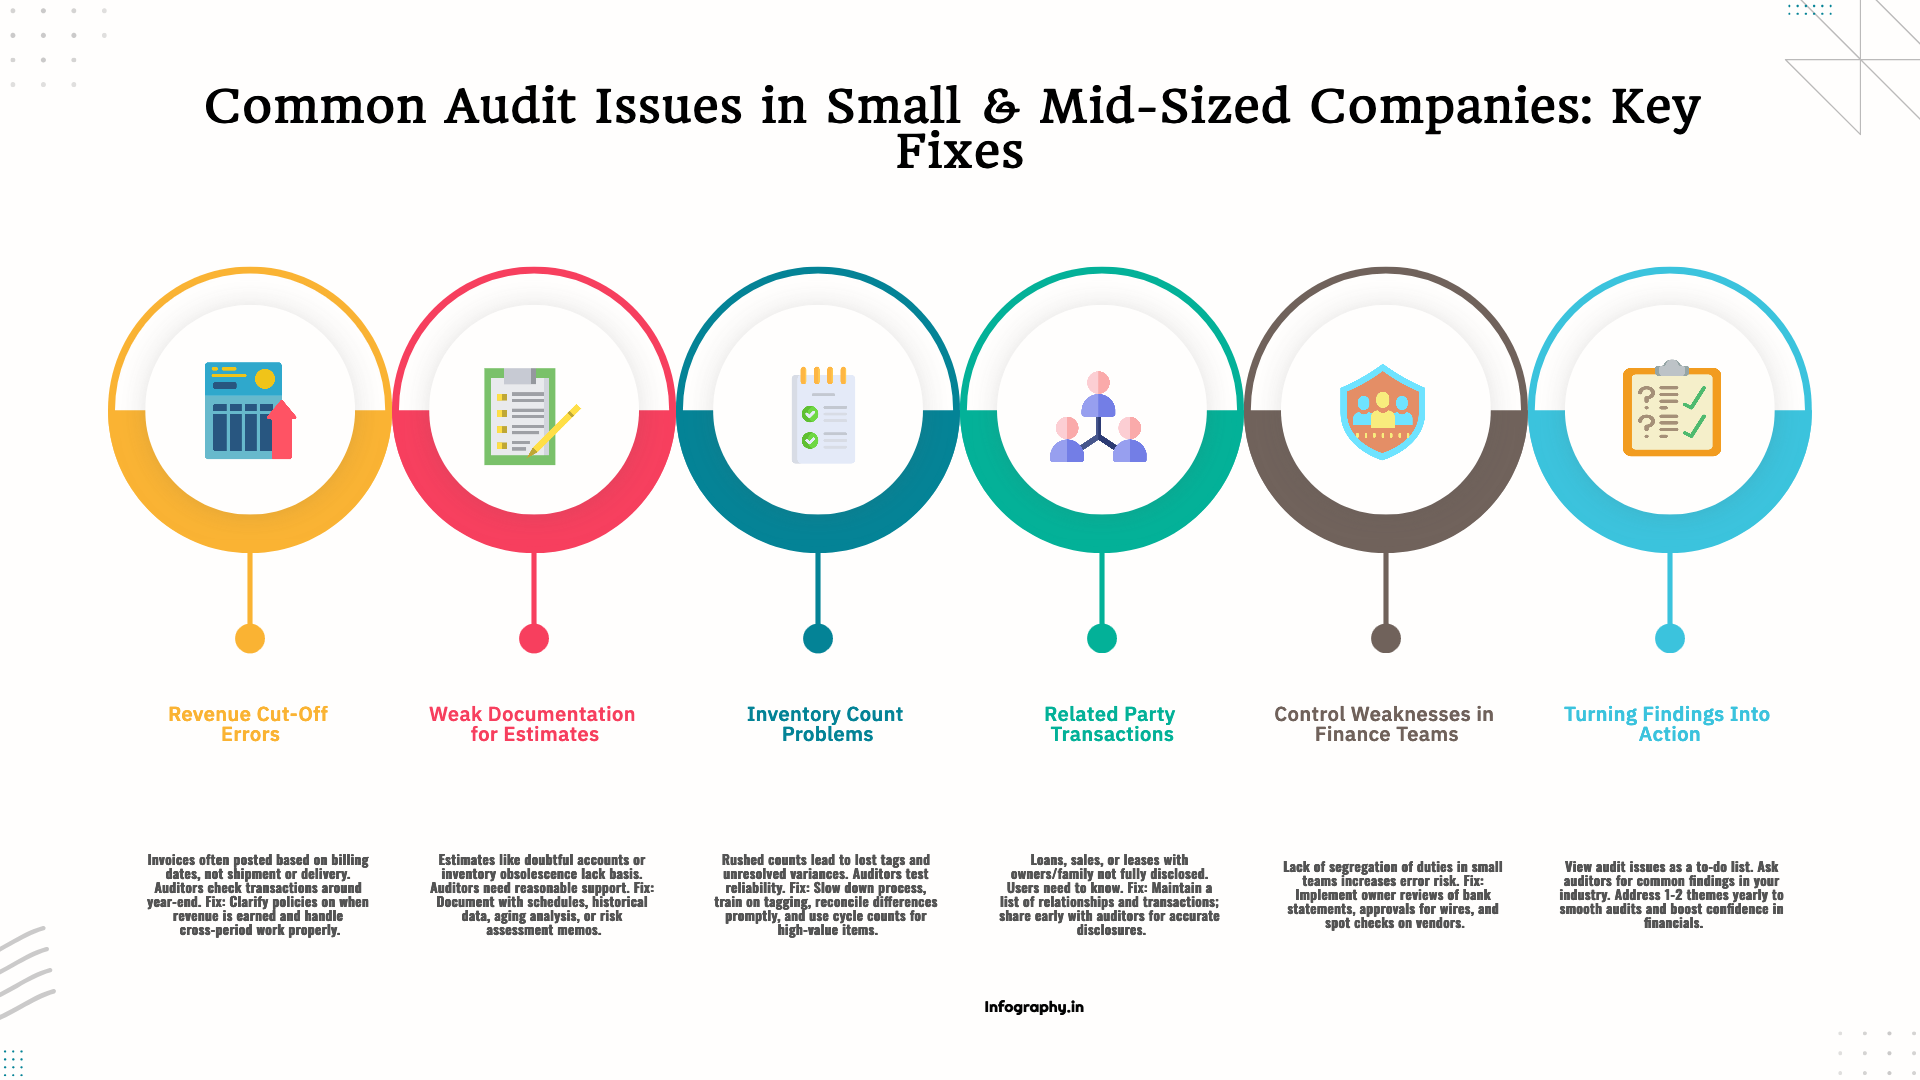

The common audit issues for small businesses are revenue booked in the wrong period, accounts that were never reconciled, year-end bills left out of payables, estimates with no written support, inventory that does not tie to the count, tax entries sitting in GAAP books, undisclosed related party dealings, and thin segregation of duties. Each one has a practical fix, and most of the fixes belong in the monthly close rather than the week before fieldwork.
This guide covers financial statement audits, the kind a CPA firm performs when a lender, investor, surety or buyer asks for audited statements. It walks through the common audit issues for small businesses one at a time, shows what auditors look for, and explains how to correct each problem so the next audit produces fewer adjustments and a shorter management letter.
A financial statement audit tests whether your balance sheet, income statement and disclosures are fairly presented under US GAAP (or another stated framework). An IRS examination tests whether your tax return is correct. Weak records cause trouble in both. If you have received an IRS letter, start with our guide on how to prepare for a tax audit, which covers the exam process itself.
If you are still deciding whether you need an audit at all, our piece on why a voluntary financial statement audit can be worth it explains who asks for one. For the difference between your own review function and the outside CPA firm, see internal vs external audits.
| Issue | What the auditor finds | Practical fix | Who owns it |
|---|---|---|---|
| Revenue cutoff | December invoices for January work, or December work billed in January | Written revenue policy plus a cutoff review of the last and first 10 days | Controller |
| Unreconciled accounts | Bank, credit card, loan or clearing accounts that do not agree to statements | Monthly reconciliations with preparer and reviewer sign-off | Bookkeeper and reviewer |
| Unrecorded liabilities | January payments for December goods and services not accrued | Search of subsequent disbursements before closing the year | AP lead |
| Undocumented estimates | Bad debt, obsolescence or warranty reserves set by feel | One-page memo per estimate with data and method | CFO or owner |
| Inventory variances | Test counts that differ from the system, unresolved count sheets | Count instructions, tag control and cycle counts | Operations and accounting |
| Tax-basis entries in GAAP books | Bonus depreciation or de minimis expensing in the audited ledger | Separate book and tax fixed asset schedules | Controller and tax preparer |
| Related party gaps | Owner loans, family vendors and common-control leases left out of notes | Annual related party questionnaire | Owner |
| Control deficiencies | One person initiates, records and reconciles cash | Owner review steps and system approval limits | Owner |
Cutoff errors are the most frequent revenue finding in small company audits. They happen when invoices are posted on the billing date instead of the date goods shipped or services were performed.
Auditors test this by pulling transactions from the days just before and just after year end and matching each to shipping records, timesheets or delivery confirmations. Under an accrual method, the IRS describes the principle in plain terms: you generally report income in the year it is earned. GAAP revenue recognition under ASC 606 is more detailed, and it rests on the same idea of matching revenue to performance.
How to fix it:
Auditors expect every balance sheet account to agree to an outside document or a supporting schedule. In small companies the bank account is usually reconciled, while credit cards, loan balances, payroll liabilities, merchant clearing accounts and "Ask My Accountant" style suspense accounts drift for months.
The fix is a reconciliation calendar. List every balance sheet account, the source document it ties to (bank statement, lender statement, payroll register, subledger), the preparer and the reviewer. Reconcile monthly, clear suspense items within 30 days as a house rule, and keep the signed reconciliation with its support. Our 5-day monthly close checklist gives a working sequence for AP, AR and reconciliations.
Supporting documents matter here as much as the reconciliation itself. IRS Publication 583 lists the basics: sales slips, paid bills, invoices, receipts, deposit slips, and canceled checks.
The mirror image of a revenue cutoff error is an expense left out. A contractor invoice for December work arrives on January 12, gets entered with a January date, and the year-end payables balance is understated. Auditors look for this with a "search for unrecorded liabilities": they scan payments made in the weeks after year end and ask which ones relate to the audited year.
You can run the same search yourself before the books close. Hold the year open for three to four weeks, review every January and early February bill and payment over a set threshold, and accrue anything that relates to the prior year. Payroll for December days paid in January and year-end bonuses are the usual items.
Estimates such as the allowance for credit losses on receivables, inventory obsolescence reserves, warranty reserves and accrued bonuses draw scrutiny because they rely on judgment. Many owners set these numbers from experience, with nothing on paper showing how they were reached.
A defensible estimate needs a one-page memo covering the data used (an aged receivables report, historical write-off rates, slow-moving inventory listing), the method, the result, and what changed from last year. Your auditor will test the inputs, so keep the reports that fed the memo.
Physical counts in small companies are often rushed: tags go missing, goods in transit are counted twice or left out, consigned stock is counted as owned, and the variance between the count and the system is booked as a single plug with no investigation. When the auditor observes the count and performs test counts, these gaps cast doubt on the whole balance.
How to fix it:
Retail and ecommerce businesses should also track shrinkage separately from count errors; our guide to inventory shrinkage accounting covers the entries and controls.
Many small businesses keep one set of books built around the tax return. That works until an audit requires GAAP statements. Two tax rules commonly cause audit adjustments.
The first is bonus depreciation. Section 70301 of the One Big Beautiful Bill Act gave taxpayers a permanent 100 percent additional first year depreciation deduction for qualified property acquired and placed in service after January 19, 2025. If your bookkeeper records that deduction in the general ledger, the audited balance sheet will show equipment at close to zero. GAAP requires depreciation over the asset's useful life.
The second is the de minimis safe harbor. The IRS lets a business without an applicable financial statement expense purchases up to $2,500 per invoice or item, and up to $5,000 with one, provided the business follows a consistent policy. Audited statements used for credit or owner reporting can count as an applicable financial statement, and the $5,000 limit then requires written procedures in place at the start of the year.
The fix is to keep separate book and tax fixed asset registers, record GAAP depreciation in the ledger, and let the tax preparer handle bonus depreciation on the return and in the book-to-tax reconciliation. Set a written capitalization threshold for the books and apply it every month.
Loans between the owner and the company, purchases from a relative's business, and rent paid to an LLC owned by the same shareholders are all related party transactions. None of them is improper on its own. GAAP requires that material ones be disclosed so readers understand that the terms may differ from arm's-length deals.
Auditors find gaps because owners forget arrangements that feel routine. Our article on related party transactions explains the disclosure concepts in more detail. Owner loans also carry tax exposure: the below-market loan rules in the Internal Revenue Code apply to any below-market loan directly or indirectly between a corporation and any shareholder, so document interest terms and repayment schedules in writing.
The practical fix is an annual related party questionnaire signed by each owner and officer, listing entities they control, family members who do business with the company, and any loans or guarantees. Hand it to the auditor at the planning meeting.
With one or two people in accounting, the same person often sets up vendors, enters bills, releases payments, records deposits and reconciles the bank. Auditors will note this as a control deficiency; the open question is severity.
Two terms describe severity. A material weakness is a deficiency, or a combination of deficiencies, in internal control over financial reporting with a reasonable possibility that a material misstatement will not be prevented or detected on a timely basis. A significant deficiency is less severe and still important enough to merit the attention of those who oversee financial reporting. That rule text is written for SEC registrants; the AICPA standards that govern private company audits use equivalent concepts, and auditors communicate both levels to management and those charged with governance in writing.
You cannot always hire a second accountant. You can add owner-level compensating controls:
Our guide on internal controls testing for small businesses shows how to test whether these controls work and how to document the results for your auditor.
A long list of proposed journal entries is a finding in itself. When the auditor has to correct depreciation, accruals and cutoff to get the statements right, the audit firm may conclude that the company's own close process is a control deficiency.
Management remains responsible for the financial statements even when the auditor helps draft them, so whoever signs the representation letter needs to understand each adjustment. Treat every proposed entry as a gap in the close process and add the step that would have caught it.
The following company and figures are illustrative. A distributor reports revenue of $6,200,000 and pretax income of $480,000. Its auditor sets overall materiality at $24,000, which is 5% of pretax income. A percentage of pretax income is a common practitioner benchmark (guidance, not a rule), and our guide to materiality and risk in audits explains how auditors choose one.
| Finding | Effect on pretax income |
|---|---|
| January service work invoiced on December 28 | ($31,500) |
| December contractor and utility bills recorded in January | ($12,800) |
| Count variance never posted | ($9,400) |
| Allowance on $46,000 of receivables over 120 days, at a 40% historical loss rate | ($18,400) |
| Total adjustments | ($72,100) |
Pretax income falls from $480,000 to $407,900, a 15.0% reduction. The cutoff error alone exceeds materiality, and the four items together are three times materiality. An adjustment this size could also trip an earnings-based loan covenant.
Separately, suppose the same company bought a $300,000 machine in 2026 and the bookkeeper expensed it in full under the bonus depreciation rule. Using a 10-year straight-line life and a full year of depreciation for simplicity, GAAP expense would be $30,000, so equipment would be understated by $270,000 and pretax income understated by the same amount.
Three months before year end, meet with the auditor to agree on timing, the document request list and any new accounting areas such as a new lease, a loan, or a new revenue stream. Our PBC request list template gives a 30-day schedule for assembling support.
At year end, plan the inventory count, then hold the books open long enough to capture late bills and run your own cutoff and unrecorded liability searches. Update each estimate memo and the related party questionnaire, and reconcile every balance sheet account.
After the audit, read the management letter with your accountant and assign an owner and a date to each comment. For a first-time engagement, our guide on preparing for your first external audit covers the planning meeting and timeline in more depth.
What is the most common audit finding for small businesses? Revenue and expense cutoff errors and unreconciled balance sheet accounts appear most often, followed closely by segregation of duties comments. All three come from a month-end close that skips reconciliations and period checks.
Is a segregation of duties comment a material weakness? Not automatically. The auditor weighs whether the gap creates a reasonable possibility of a material misstatement that would go undetected. Owner review controls, such as reviewing bank statements and approving large payments, often reduce the severity to a significant deficiency or a lesser deficiency.
Can my auditor fix the books for me? An auditor can propose adjustments and may help draft the statements, subject to independence rules. Management stays responsible for the numbers and must understand and approve every entry, so relying on the auditor to close the books usually generates a control comment.
Do financial statement audit findings affect my tax return? They can. Adjustments to revenue, accruals or inventory may change taxable income, and documented related party loans and capitalization policies support your tax positions too.
How long does it take to clear recurring audit findings? It depends on the issue. Cutoff and reconciliation problems can often be fixed within two or three monthly closes. Control changes that need new approval workflows or extra staff may take a full audit cycle to show results.
Madras Accountancy helps small and mid-sized US businesses with monthly bookkeeping, reconciliations, year-end close, audit support and tax preparation, so your books are ready before the auditor arrives. To talk through your next audit, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



