



Property rental accounting means recording rent and every property expense separately for each rental, keeping receipts, holding security deposits as liabilities, and tracking depreciation, so you can file Schedule E accurately and see which properties make money. Most individual landlords use the cash method with simple rental accounting software.
You just received three rent payments, paid a plumber for emergency repairs, and your accountant is asking for last quarter's receipts. Meanwhile, you're wondering if that new water heater counts as a repair or a capital improvement for your taxes.
Property rental accounting is the process of tracking all financial transactions related to your rental properties, including rental income, expenses, security deposits, and tax-deductible costs. Unlike personal finance, rental property accounting requires meticulous record-keeping to maximize tax deductions, prove income for future investments, and understand which properties in your portfolio are actually profitable.
Done correctly, rental accounting helps you capture deductions you would otherwise miss and gives you clear visibility into each property's performance. This guide covers everything from choosing the right accounting method to setting up systems that make tax season routine.
Property rental accounting is the specialized practice of recording, categorizing, and reporting all financial activities related to rental real estate. This goes beyond simple income tracking, you're managing multiple revenue streams, tracking deductible expenses, handling security deposits, and maintaining records that satisfy IRS requirements.
The main difference between rental accounting and regular business accounting is the property-by-property tracking requirement. If you own three rental properties, you essentially run three separate businesses. Each property needs its own income statement showing rent collected, expenses paid, and net profit or loss. Schedule E of Form 1040 reports income and expenses for each property separately.
Your rental accounting system must answer three questions for each property: How much rental income did you collect? What expenses did you incur? What's your net taxable income after deductions? These answers directly affect your tax liability and investment returns. Landlords who skip proper accounting tend to miss deductible expenses or can't prove them if the IRS asks.
The IRS gives you significant tax advantages for owning rental properties, depreciation, mortgage interest deductions, and expense write-offs, but only if you maintain documentation. Your accounting system is what turns those potential benefits into actual tax savings.
Accurate rental accounting directly impacts your bottom line in three ways: tax savings, investment decisions, and legal protection. Tax savings alone often justify the effort, because you can only deduct what you can document.
When you track expenses properly, you capture every deductible dollar. That $45 trip to the hardware store? Deductible. The $200 monthly property management fee? Deductible. The $8,000 roof replacement? Deductible over time through depreciation. Without accounting records, many of these small expenses are forgotten by tax season.
Investment decisions improve with clear financial data. You can't accurately calculate return on investment without knowing your true expenses. Many landlords think a property is profitable because rent exceeds the mortgage payment. But when you factor in maintenance, vacancy, insurance, and property taxes, that "profitable" property might be losing $200 monthly. Proper accounting reveals this before it becomes a major problem.
Legal protection matters too. If the IRS audits your rental income, you need receipts, bank statements, and transaction records proving every deduction. Without documentation, the IRS will disallow expenses and assess penalties. Organized records make an examination far easier to resolve.
Property financing depends on accurate records. When you apply for your next investment property loan, lenders want 2-3 years of tax returns showing rental income and expenses. Clean books make loan approval faster and help you secure better interest rates because lenders see you as a professional operator.
Tracking rental income starts with separating personal and business finances. Open a dedicated bank account for each rental property or at minimum one account for all your rental operations. Every rent payment deposits into this account, and every property expense pays from it. This separation is critical for both accounting accuracy and IRS audit protection.
Record income as it arrives. When a tenant pays $1,500 rent, log it immediately with the date, property address, and payment method. Don't wait until month-end to batch-record payments. Real-time tracking prevents errors and gives you current cash flow visibility. Beyond rent, remember to record other income sources: late fees, pet fees, parking fees, laundry income, and application fees all count as taxable rental income.
Expense tracking requires more detail. Every expense needs documentation showing the date, amount, vendor, property address, and expense category. The IRS recognizes specific expense categories on Schedule E, so organize your tracking around these: advertising, auto and travel, cleaning and maintenance, commissions, insurance, legal and professional fees, management fees, mortgage interest, repairs, supplies, taxes, utilities, and depreciation.
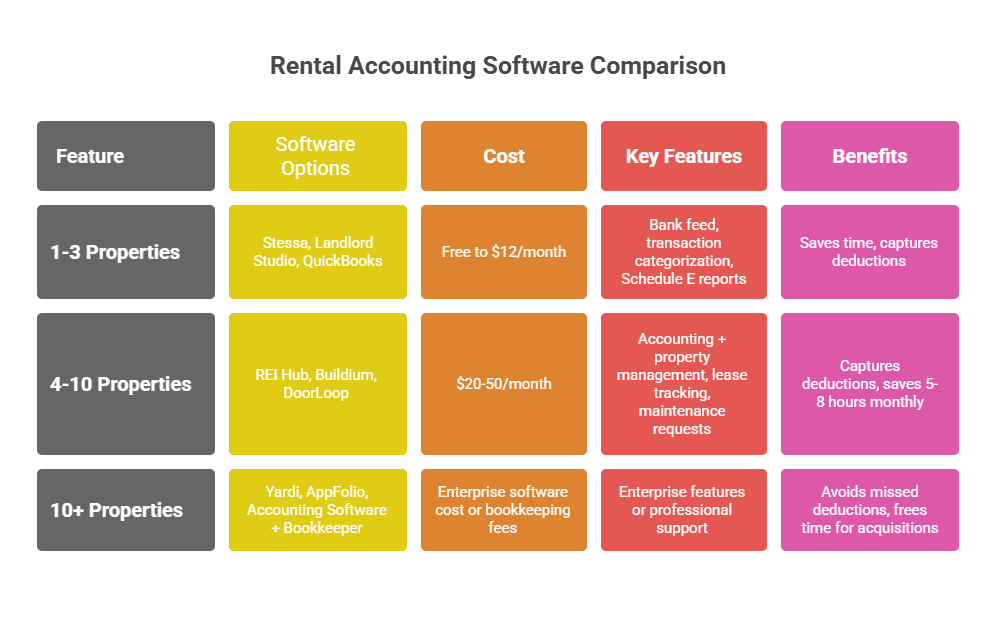
Use the right tools for your portfolio size. Managing 1-2 properties? A dedicated spreadsheet or basic accounting software like QuickBooks might work. Managing 3-10 properties? Purpose-built rental property software like Stessa, Landlord Studio, or REI Hub will save you hours weekly. Managing 10+ properties? Consider outsourcing your bookkeeping to specialized accounting services that understand real estate.
Digitize everything immediately. Use scanning apps to photograph receipts the moment you get them. Many accounting platforms let you snap photos of receipts and automatically extract the amount, date, and vendor. Paper receipts fade and get lost, digital copies are searchable and permanent.
Landlords have two accounting method options, and your choice affects how you report income and expenses. Most individual landlords use cash basis accounting, while larger rental businesses often use accrual accounting.

Cash basis accounting works for most landlords because it's straightforward and matches your bank account. You report income when you actually receive the payment and deduct expenses when you pay them. If a tenant's $1,200 rent check arrives on January 3rd for December's rent, you report that income in January under cash accounting.
Accrual accounting records transactions when they're earned or incurred, not when cash changes hands. December rent gets recorded in December even if the tenant pays late in January. This method provides a more accurate picture of monthly performance but requires more complex bookkeeping.
The IRS allows most individual landlords to use either method, but you must remain consistent year-to-year and need IRS consent (usually Form 3115) to change. Cash basis is usually the simpler choice for individual landlords; C corporations above the gross receipts test ($32 million for 2026, per Rev. Proc. 2025-32) must use accrual. If you're unsure which method fits your situation, review our guide on choosing between cash and accrual accounting methods for your business structure.
The IRS allows rental property owners to deduct ordinary and necessary expenses for managing and maintaining investment properties. Understanding these deductions can save you thousands annually.
Repairs versus capital improvements is a critical distinction. Repairs restore property to original condition and are immediately deductible. A capital improvement adds value or extends the property's life and must be depreciated over multiple years. Fixing a broken water heater is a repair ($800 immediate deduction). The de minimis safe harbor election also lets you expense items costing up to $2,500 per invoice or item (IRS tangible property regulations). Installing central air conditioning where none existed is a capital improvement ($8,000 depreciated over 27.5 years).
Most landlords miss travel deductions. Every business mile driven to the property, the hardware store, or a tenant meeting is deductible using the standard mileage rate or actual costs. At the 2026 rates of 72.5 cents (January-June) and 76 cents (July-December), 2,000 rental miles split evenly across the year comes to $1,485. Keep a log of date, destination, purpose and miles. Use a mileage tracking app to automatically log these trips.
Home office deductions can apply if you use space regularly and exclusively for rental property management and your rental activity rises to the level of a trade or business. A dedicated office where you handle bookkeeping, tenant communications, and property research qualifies for a home office deduction calculated by square footage or simplified method ($5 per square foot, up to 300 square feet, per the IRS simplified option).
Choosing the right software depends on your portfolio size and technical comfort level.
Free spreadsheets work for 1-2 properties but become unmanageable beyond that. Purpose-built rental accounting software saves time and captures deductions you'd otherwise miss.
For 1-3 properties, consider rental-focused apps such as Stessa or Landlord Studio (some offer free tiers; check current pricing on their sites), or simple QuickBooks tracking. These platforms connect to your bank accounts, categorize transactions automatically, and generate Schedule E reports for tax filing.
For 4-10 properties, invest in more powerful software like REI Hub, Buildium, or DoorLoop. These platforms combine accounting with property management features: lease tracking, maintenance requests, and tenant communication. The monthly subscription often pays for itself through captured deductions and time saved on bookkeeping.
For 10+ properties, you need either enterprise software (Yardi, AppFolio) or a combination of accounting software plus professional bookkeeping support. At this scale, missing deductions costs more than hiring help. Many successful rental property investors outsource their accounting entirely once they reach 15-20 units, freeing time to acquire more properties instead of managing spreadsheets.
Key features to prioritize: bank feed connections that import transactions automatically, mobile receipt capture for instant documentation, property-level profit and loss statements, Schedule E report generation, and mileage tracking for travel deductions. These features help you capture deductions and hand your tax preparer clean records.
Tax preparation starts with year-round organization, not December scrambling. Landlords who maintain monthly accounting routines spend far less time preparing taxes than those who batch-record an entire year in January.
Schedule monthly bookkeeping sessions. Set aside 2-3 hours monthly to categorize transactions, reconcile bank accounts, and file digital receipts. This habit prevents year-end chaos and catches errors while they're still fresh. Most accounting software can handle this reconciliation process automatically if you keep bank feeds connected.
Maintain separate documentation for security deposits. These aren't income when received, they're liability. Only when you keep a portion for damages does it become income. Track security deposits in a separate account or ledger to avoid accidentally reporting them as rental income.
Generate property-level profit and loss statements quarterly. This shows each property's rental income, operating expenses, and net income. Quarterly reviews help you identify underperforming properties and make mid-year adjustments before problems compound.
For guidance on avoiding common pitfalls, review our article on accounting mistakes small business owners should avoid. Many of these principles apply directly to rental property operations.
Prepare Form 1040 Schedule E by pulling data from your accounting system. Schedule E lists income and expenses for each property separately. Your accounting software should generate this form automatically, saving hours of manual data entry. Many tax professionals price Schedule E work per property, and clean books usually lower the bill because less cleanup is needed.
The most expensive mistake is commingling personal and business funds. When your personal expenses and rental income flow through the same account, separating them for taxes becomes nearly impossible. This mistake costs landlords thousands in missed deductions and creates nightmare scenarios during IRS audits.
Missing depreciation deductions is costly. Depreciation is a non-cash deduction that reduces taxable income by spreading the building's cost over 27.5 years. A $275,000 rental property that includes $75,000 of land has a $200,000 building basis, which provides roughly $7,272 in annual depreciation deductions. Worse, the IRS reduces your basis by the depreciation you were entitled to claim even if you didn't claim it, so skipping it raises your tax at sale without lowering it now. If you missed depreciation in earlier years, ask your preparer about a change in accounting method (Form 3115) to catch up.
Failing to track mileage is leaving money on the table. That trip to Home Depot? Deductible. Driving to show the property to prospective tenants? Deductible. Meeting the plumber on-site? Deductible. At more than 70 cents per mile, a few hundred untracked miles a year adds up quickly.
Not keeping receipts destroys deductions during audits. The IRS can disallow any expense without documentation. That $2,500 water heater replacement becomes non-deductible if you can't prove the expense. Digital receipt storage through accounting software solves this problem by automatically linking receipts to transactions.
Misclassifying repairs as capital improvements or vice versa affects current-year taxes. Repairs are immediately deductible while capital improvements must be depreciated. A $1,000 repair saves you $220-370 in taxes this year (depending on your tax bracket). The same expense incorrectly classified as a capital improvement only saves you $8-13 annually for 27.5 years.
Managing multiple rental properties requires systems that scale. What works for one duplex breaks down at five single-family homes. The key is property-level accounting that rolls up into portfolio-level reporting.
Create a separate chart of accounts for each property within your accounting system. Each property gets its own income and expense categories. This separation allows you to compare property performance, identify which properties generate the best returns, and make data-driven decisions about selling underperformers.
Use property codes or tags to categorize every transaction. When you pay a $300 plumbing bill for 123 Oak Street, tag it with that property's code. Your software can then filter all transactions by property, generating individual profit and loss statements automatically.
Standardize your processes across properties. Use the same expense categories, same vendor management system, and same rent collection process for all properties. Standardization reduces errors and makes it easier to train assistants or property managers as you grow.
Consider entity structuring as your portfolio expands. Many landlords create separate LLCs for groups of properties to limit liability. This adds accounting complexity because each LLC needs its own books, tax returns, and bank accounts. Whether the protection justifies the cost depends on your equity, insurance and state LLC fees. Professional guidance helps determine the right structure, explore our resources on structuring your business for tax efficiency.
Portfolio reporting should show both individual property performance and aggregate numbers. You want to see that 123 Oak Street generated $18,500 net income while 456 Maple Street lost $3,200. This visibility helps you prioritize maintenance spending, adjust rent pricing, and decide which properties to sell or refinance.
How do I report rental income if my tenant pays late?
If you use cash basis accounting (most landlords do), report rental income in the year you actually receive payment, not when it's due. If December rent arrives on January 4th, report it on next year's taxes. Keep documentation showing payment dates in case of IRS questions. For advance rent paid covering future periods, you must report the full amount in the year received regardless of accounting method.
Can I deduct the cost of furniture and appliances in my rental property?
Yes, but the deduction method depends on the item's cost and useful life. Items costing up to $2,500 per invoice or item can be expensed immediately if you make the de minimis safe harbor election. Otherwise, appliances and furniture used in a residential rental are 5-year property, while a building system like HVAC is depreciated over 27.5 years (IRS Publication 527). Appliances and furniture acquired after January 19, 2025 also qualify for permanent 100% bonus depreciation under the One Big Beautiful Bill Act (IRS Notice 2026-11), so they can usually be deducted in full in the year placed in service.
Do I need separate bank accounts for each rental property?
Separate accounts for each property simplify accounting but aren't legally required. At minimum, maintain one dedicated rental business account separate from personal finances. As your portfolio grows beyond 3-4 properties, separate accounts per property become valuable for tracking cash flow and security deposits. Many landlords use one checking account with sub-accounts or accounting software property codes to track separately without multiple physical accounts.
What records should I keep for rental property tax purposes?
Keep all receipts, invoices, bank statements, and lease agreements for at least 7 years. The IRS generally has 3 years to assess additional tax (6 years if you omit more than 25% of gross income) (IRS record-keeping guidance). Beyond receipts, maintain documentation showing property acquisition costs, improvement expenses, and depreciation calculations. These records prove your tax basis when you eventually sell the property and calculate capital gains.
How does depreciation work for rental properties?
Residential rental properties depreciate over 27.5 years using the straight-line method. You can only depreciate the building value, not the land. If you purchased a property for $350,000 with a land value of $100,000, your depreciable basis is $250,000, giving you a $9,091 annual depreciation deduction (the first year is prorated using the mid-month convention). This is a paper loss that reduces taxable income without requiring cash outflow, making it one of real estate's most powerful tax benefits.
Should I hire a bookkeeper or accountant for my rental properties?
Hire a bookkeeper if managing 5+ properties becomes time-consuming; fees depend on transaction volume, so get a quote. Consider a CPA or tax accountant at minimum for annual tax preparation. A preparer who knows rental property rules can often find deductions and avoid errors worth more than the fee. Many successful investors use bookkeepers for monthly work and CPAs for tax strategy and filing.
How do I track expenses when I use a credit card for rental property costs?
Open a dedicated credit card exclusively for rental property expenses. This creates an automatic expense log and builds business credit. Categorize and record credit card charges when made, not when you pay the bill. Your accounting software should connect to the credit card account and import charges automatically. Pay the card from your rental property bank account to maintain clean separation from personal finances.
What's the difference between a repair and a capital improvement for tax purposes?
Repairs maintain existing condition and are immediately deductible (fixing a broken pipe, painting a room, replacing broken windows). Capital improvements add value, adapt property to new use, or extend its life beyond one year, and must be depreciated (installing new HVAC, adding a deck, replacing the entire roof, kitchen remodel). IRS Publication 527 provides detailed guidance, but when in doubt, consult a tax professional since misclassification can cost thousands in current-year deductions.
Property rental accounting transforms from overwhelming to manageable when you implement the right systems from the start. Separate bank accounts, consistent transaction tracking, and monthly bookkeeping sessions are the foundation. Landlords who master these basics capture more deductions and spend much less time on tax preparation.
Start with your accounting method choice and software selection based on your current portfolio size, then commit to recording transactions as they happen rather than batch-processing monthly. A few minutes spent categorizing each week's expenses saves hours during tax season.
At Madras Accountancy, we partner with rental property investors across the US who want professional bookkeeping and tax preparation without hiring full-time accounting staff. Our team understands real estate taxation, tracks property-level performance, and prepares Schedule E forms that maximize deductions while maintaining IRS compliance.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



