

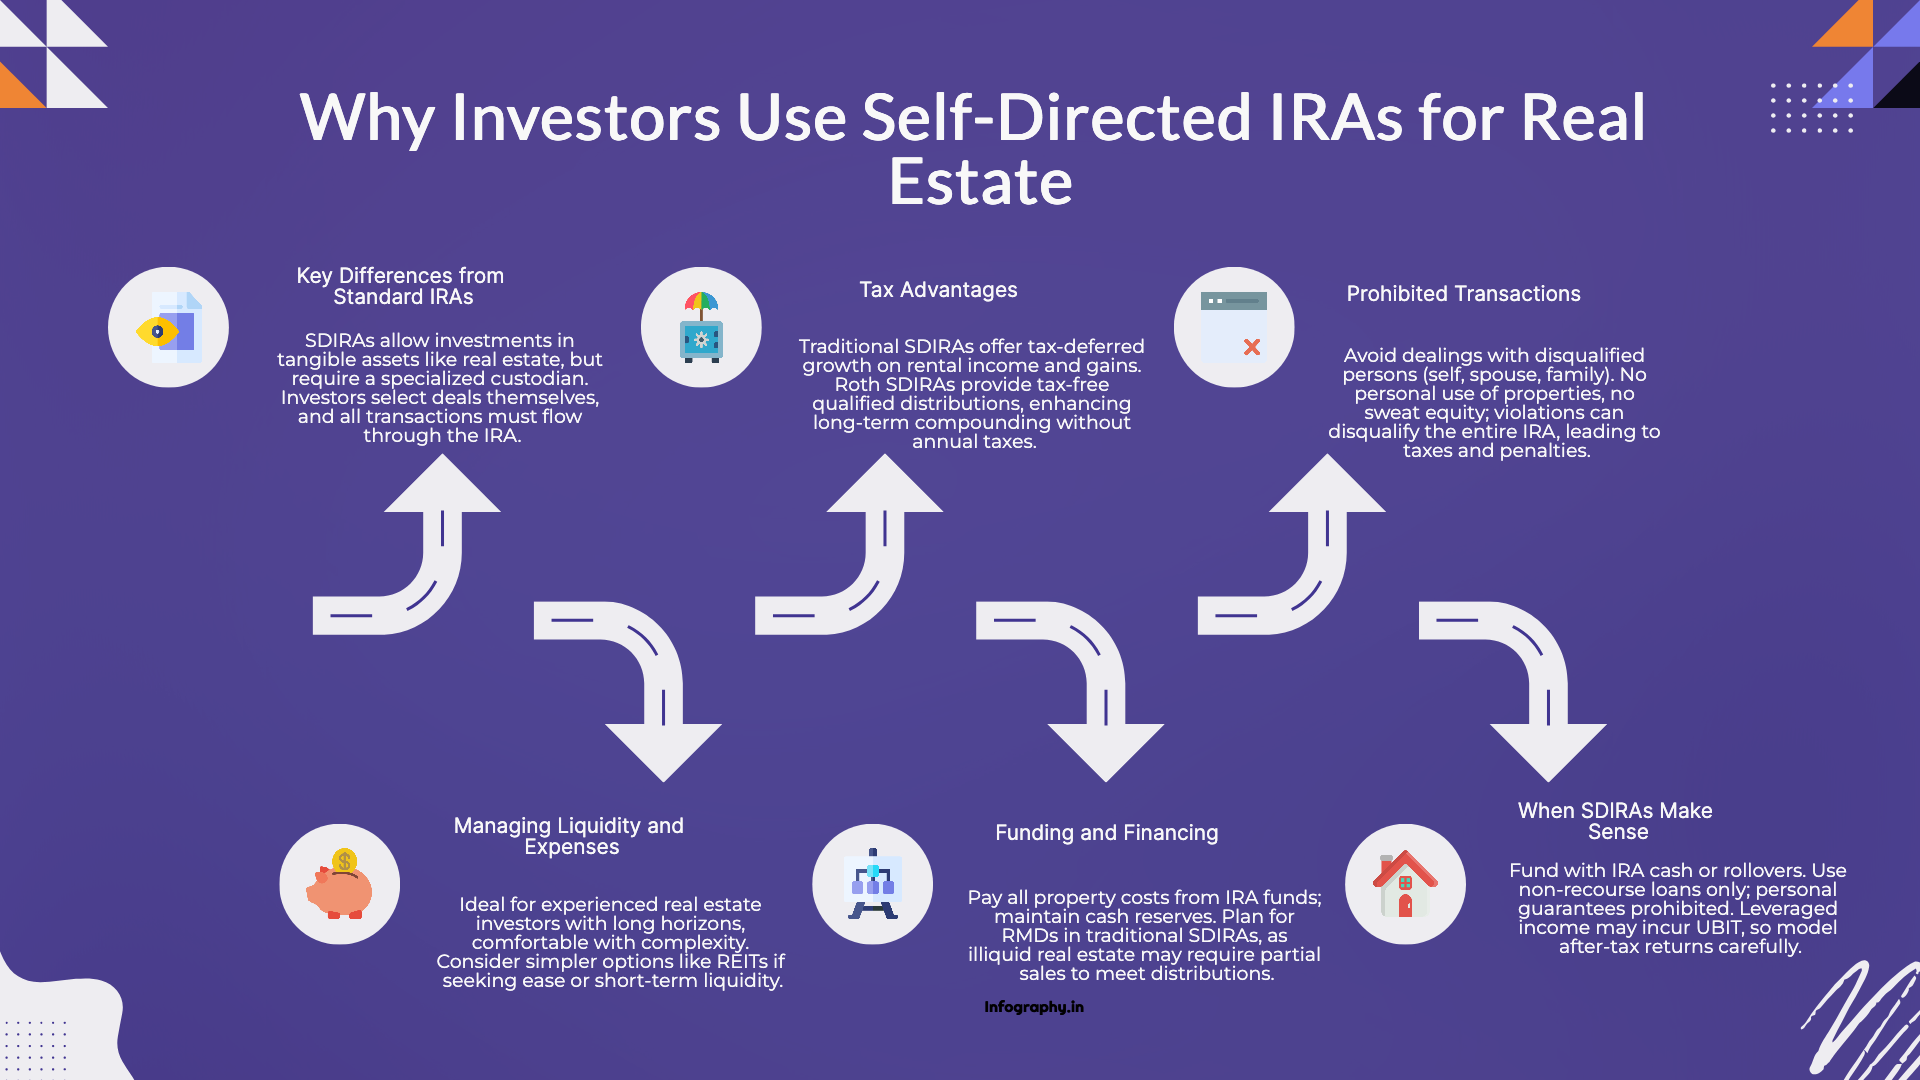

You can buy real estate with your IRA if the account is held by a trustee or custodian that accepts real property, the purchase is paid entirely with IRA money, and neither you nor any disqualified person uses or deals with the property. Most brokerage IRAs only offer securities, so investors open a self-directed IRA (SDIRA) with a custodian that will hold a deed, then direct that custodian to buy.
The tax code bans only a few IRA assets, such as life insurance and most collectibles, and instead polices how you deal with what the account owns. Before you buy real estate with your IRA, learn the prohibited transaction rules in section 4975, the tax on debt-financed income, the 2026 contribution limits and required minimum distributions.
A self-directed IRA is an ordinary traditional or Roth IRA whose custodian agrees to hold nonpublicly traded assets such as rental houses, land or mortgage notes, and to sign and pay on your written instructions.
The custodian must meet the federal standard for any IRA. According to IRS Publication 590-A, "The trustee or custodian must be a bank, a federally insured credit union, a savings and loan association, or an entity approved by the IRS to act as trustee or custodian." Nonbank custodians apply under Treasury Regulation 1.408-2(e), and the IRS publishes a list of approved nonbank trustees and custodians you can check before opening an account.
Approval covers administration only. The SEC's investor alert on self-directed IRAs and the risk of fraud states that "Self-directed IRA custodians are only responsible for holding and administering the assets in the account," and that most custodial agreements say the custodian "has no responsibility for investment performance." Underwriting the deal is your job, so work through a real estate due diligence checklist before signing.
Title is taken in the name of the custodian for the benefit of your IRA (for example, "ABC Trust Company, Custodian FBO Jane Smith IRA"). Every bill and rent check runs through the account.
Custodian paperwork differs, so treat this sequence as a practical outline.
Section 4975(c)(1) of the Internal Revenue Code bans any direct or indirect "sale or exchange, or leasing, of any property between a plan and a disqualified person," any "lending of money or other extension of credit," any "furnishing of goods, services, or facilities," and any "transfer to, or use by or for the benefit of, a disqualified person of the income or assets of a plan."
Disqualified persons include you as the fiduciary who directs the account, your family, and entities those people own 50 percent or more of. Section 4975(e)(6) defines family as your "spouse, ancestor, lineal descendant, and any spouse of a lineal descendant." Siblings fall outside that definition, though a deal that indirectly benefits you can still be challenged.
| Action involving IRA-owned real estate | Status | Why |
|---|---|---|
| Buying a rental from an unrelated seller with IRA cash | Allowed | Arm's-length purchase with no disqualified person |
| Selling your own rental to your IRA | Prohibited | Sale between the plan and a disqualified person |
| Renting the IRA's house to your daughter at market rent | Prohibited | Leasing to a lineal descendant, regardless of rent |
| Staying in the IRA's vacation condo for a weekend | Prohibited | Use of plan assets for your benefit |
| Painting or repairing the property yourself | Prohibited | Furnishing services to the plan |
| Hiring an unrelated contractor paid from the IRA | Allowed | Third party paid from plan funds |
| Personally guaranteeing the IRA's mortgage | Prohibited | Extension of credit by a disqualified person |
| Paying the property tax bill from your checking account | Not permitted (guidance) | IRA expenses must be paid with IRA funds; outside payments risk treatment as an excess contribution or an extension of credit |
The penalty is severe. Publication 590-A explains that if you engage in a prohibited transaction, "the account stops being an IRA as of the first day of that year," and "the account is treated as distributing all its assets to you at their fair market values on the first day of the year." If you are under 59½, the 10% additional tax on early distributions can apply as well, which is reported on Form 5329. Disqualified persons other than the IRA owner face a separate excise tax of 15% of the amount involved, rising to 100% if the transaction is not corrected.
Publication 590-A also warns that "If your IRA is invested in nonpublicly traded assets or assets that you directly control, the risk of engaging in a prohibited transaction in connection with your account may be increased." That warning applies to IRA-owned "checkbook control" LLCs, where your signing authority makes it easy to pay a personal expense from IRA money by mistake.
An IRA can borrow to buy property, but you cannot sign or guarantee the note, because a personal guarantee is an "extension of credit" between a disqualified person and the plan under section 4975(c)(1)(B). Publication 590-A also lists "Using it as security for a loan" as a prohibited transaction.
That leaves non-recourse debt, where the lender's only remedy on default is the property. As a market observation, these lenders typically want a larger down payment and a higher rate than a conventional investor mortgage.
Borrowing also brings in a second tax. Under IRC section 514, income from "debt-financed property" is unrelated business taxable income in the same proportion that average acquisition indebtedness bears to the property's average adjusted basis for the year. Rent from real property is normally excluded from UBTI, but that exclusion does not protect the debt-financed share.
Section 514(c)(9) exempts real estate debt for "qualified organizations," a list that covers 401(a) qualified trusts and certain educational organizations. IRAs are not on that list. That is one reason some self-employed investors use a Solo 401(k) for financed property instead.
Publication 590-A states that "If the IRA has $1,000 or more of unrelated trade or business gross income, the IRA trustee is required to file a Form 990-T," due by "the 15th day of the 4th month after the end of the IRA's tax year." The tax is paid from the IRA. IRS Publication 598 lists "traditional IRAs, Roth IRAs, simplified employee pensions (SEP-IRAs), and savings incentive match plans" among the arrangements subject to the tax.
Two more rules shape the bill:
Publication 598 treats property as debt-financed if acquisition debt existed during the year or "during the 12-month period before the date of the property's disposal." For gains, section 514(c)(7) uses "the highest amount of the acquisition indebtedness" during the 12-month period ending with the sale. Paying the loan off more than 12 months before a sale removes the debt-financed share of the gain. Our Form 990-T and UBIT guide covers the return line by line.
The figures below are illustrative and simplified (straight-line depreciation, no mid-month convention).
A traditional SDIRA buys a rental for $400,000 in January 2026: $160,000 of IRA cash plus a $240,000 non-recourse loan at 6.5% over 30 years. The land is worth $70,000, so the $330,000 building depreciates over 27.5 years.
Year 1 operations
| Item | Amount |
|---|---|
| Gross rent | $42,000 |
| Operating expenses (tax, insurance, management, repairs) | $12,000 |
| Mortgage interest | $15,521 |
| Depreciation ($330,000 / 27.5) | $12,000 |
| Net rental income | $2,479 |
| Average acquisition debt (monthly average) | $238,785 |
| Average adjusted basis ($400,000 and $388,000) | $394,000 |
| Debt/basis percentage | 60.61% |
| Debt-financed gross income ($42,000 x 60.61%) | $25,454 |
| Net UDFI ($2,479 x 60.61%) | $1,502 |
| Less specific deduction | $1,000 |
| Taxable UBTI | $502 |
| 2026 trust tax at 10% | $50 |
Debt-financed gross income exceeds $1,000, so Form 990-T is required even though the tax is about $50. Cash flow inside the IRA is $42,000 minus $12,000 of expenses and $18,204 of annual debt service, or $11,796.
Sale at the end of year 6
The IRA sells for $520,000. Adjusted basis is $328,000 after six years of depreciation, so the gain is $192,000. The loan balance 12 months before the sale was $224,666, the highest balance in the look-back window. Average adjusted basis for year 6 is $334,000, which gives a debt/basis percentage of 67.27% and debt-financed gain of $129,149. Looking at the gain alone, $128,149 is taxable on Form 990-T after the $1,000 deduction. If all of it qualified for 2026 trust capital gain rates, the tax would be about $24,322. The depreciation portion can be taxed at up to 25% as unrecaptured section 1250 gain, so the real figure is higher; our guide to depreciation recapture on real estate explains that calculation.
Had the IRA retired the loan more than 12 months before closing, the debt-financed share of the gain would have been zero. Test payoff timing with real estate financial modeling.
Per IRS news release IR-2025-111, "The limit on annual contributions to an IRA is increased to $7,500 from $7,000" for 2026, and the catch-up for savers 50 and over "is increased to $1,100." Roth IRA eligibility phases out between $153,000 and $168,000 of modified AGI for single filers and between $242,000 and $252,000 for married couples filing jointly.
Those limits matter for upkeep. If a roof fails and the IRA lacks cash, you cannot pay the contractor yourself; you need a contribution within the limit, a transfer from another IRA, or a sale. Keeping six to twelve months of expenses in the IRA as a reserve is a common practitioner guideline. If you make nondeductible contributions or convert a traditional SDIRA to a Roth, track basis on Form 8606. Converting IRA-owned real estate to a Roth adds the property's value to your taxable income for the year, so plan on a current appraisal.
Traditional IRA owners must start RMDs at 73, and SECURE 2.0 raises that age to 75 for owners born in 1960 or later. The IRS RMD FAQs confirm the first distribution can wait until April 1 of the following year, and missing one triggers "an excise tax of 25%," reduced to "10% if the RMD is timely corrected within two years." Our SECURE 2.0 Act guide covers the change.
An IRA that is mostly one building can struggle to produce the cash. Options include a cash reserve, satisfying the RMD from another traditional IRA (the rules let you aggregate IRA RMDs), or taking an in-kind distribution of a fractional deed interest at appraised value. Owners who give to charity can also use a qualified charitable distribution to count toward the RMD. Roth IRAs avoid the issue during the owner's life, because "The RMD rules do not apply to Roth IRAs or Designated Roth accounts while the owner is alive."
Buying inside an IRA gives up personal tax benefits. Depreciation and rental losses stay inside the account, so they cannot offset your other income. Withdrawals from a traditional IRA are included in taxable income at your regular rate, so a property's appreciation eventually leaves the account without the lower long-term rates described in our capital gains tax on real estate guide.
If you want hands-on control or plan to use the property yourself, buying through a personally owned LLC or partnership usually fits better. Our comparison of LLCs, partnerships and REITs covers those trade-offs. Publicly traded REITs in a regular IRA give property exposure without these rules.
Can I buy real estate with my IRA and live in it later? Not while the IRA owns it. Personal use is a prohibited transaction. You could take the property as a distribution, pay tax on its fair market value, and then use it personally.
Can I use my IRA to buy a house for my children? No. Lineal descendants and their spouses are disqualified persons under section 4975(e)(6), so they cannot rent, occupy, or buy the property from the IRA.
Can I withdraw IRA money to buy my own first home? Yes, as a taxable withdrawal. The IRS allows up to $10,000 for qualified first-time homebuyers without the 10% early withdrawal tax, though income tax still applies to traditional IRA money.
Does a Roth IRA pay tax on a financed rental? Yes. Roth IRAs are subject to UBIT, so the debt-financed share of rent and gain is taxed on Form 990-T paid from the account.
Who files Form 990-T for my IRA? The IRA trustee or custodian is responsible for filing when gross unrelated business income is $1,000 or more. Any tax is paid from IRA funds, so ask your custodian early how it collects the figures.
Madras Accountancy supports real estate investors and their CPAs with bookkeeping, tax preparation, and CFO-level modeling, including tracking IRA-owned property income and preparing workpapers for Form 990-T. To talk through your situation, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



