


If you are leaning on a treaty to lower your US tax, there is a good chance you also have to tell the IRS you are doing it. You use Form 8833 for that, and skipping it carries a flat penalty even when your treaty claim is completely correct. This guide explains what the form is, when you must file it, the exceptions that let you skip it, and how to fill it out without tripping the rules.
Form 8833 is the Treaty-Based Return Position Disclosure required under section 6114 of the Internal Revenue Code. The United States has income tax treaties with over 60 countries, and when treaty provisions in an income tax treaty overrule or modify the normal rules of the tax code to reduce your tax, you are taking a treaty-based position, a treaty based return stance, for that tax year. The Internal Revenue Service calls this tax treaty-based return reporting, and IRS Form 8833 is how you disclose it on your return.
The logic is simple once you see it. Domestic law says one thing, the treaty modifies or alters it in your favor, so the treaty alters a plain reading of the law, and the US tax form 8833 tells the IRS which treaty you are relying on and why. It is an IRS disclosure form, not a claim form, and you notify the IRS using Form 8833. You still claim the benefit on your return itself; the return position disclosure under section 6114 just puts the IRS on notice that a treaty, not plain domestic law, is driving the number.
You must file the form whenever you take a position that a tax treaty overrules or modifies a provision of US tax law, and that position reduces, or could reduce, the tax you owe. In plain terms, if you are relying on a tax treaty to pay less than domestic law would charge, the disclosure required by section 6114 applies.
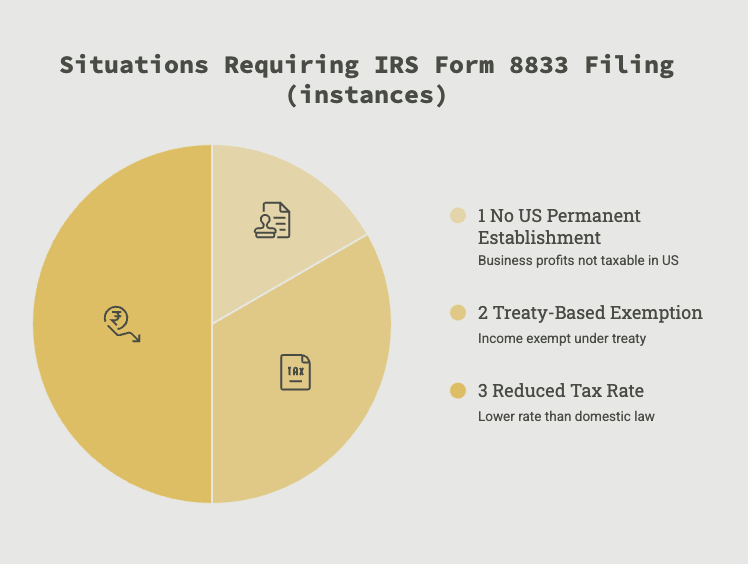
When you take a treaty-based position like these you must file IRS Form 8833. Common situations include claiming that you have no US permanent establishment so your business profits are not taxable here, claiming a treaty-based exemption on certain income, or taking a reduced rate not available under domestic law. Each reportable treaty-based return position gets its own form, so if you take two separate positions, Form 8833 must be filed twice. The safest habit is to ask, for every treaty claim you make, whether the form is needed before you file.
There is a second reason to file, and it catches a lot of people. A dual-resident taxpayer is someone treated as a tax resident of both the US and a treaty country under each country's domestic rules. When you use the treaty tie-breaker to be treated as a resident of the other country, and therefore a nonresident here, you disclose that under Regulations section 301.7701(b)-7.
This residency question matters because tax residency drives everything else. Being treated as a nonresident under a treaty can change which income the US can tax at all, so the IRS wants it flagged. The reporting rules here mirror the section 6114 rules, and the same penalty applies if you skip it.
Not every treaty benefit needs a form, and this is where people either over-file or panic unnecessarily. Regulations section 301.6114-1(c) lists positions where reporting is waived, and most of them involve income where tax is already collected correctly at the source.
The big one is passive income handled through withholding. If you claim reduced tax rates on dividends, interest, or royalties and a withholding agent already reports the payment and the treaty rate on a Form 1042-S, you generally do not file the form for it. Similar relief applies to many treaty claims on wages, pensions, annuities, and social security, and to reduced tax rates or exemptions the payer has already applied. The rule of thumb: if the saving shows up through correct withholding rather than as something you argue on the return, you usually skip the form. When you are unsure, the Form 8833 instructions spell out the full list.
Form 8833 is a short, two-page form, but it wants specifics. You identify yourself and your taxpayer identification number, then name the applicable treaty country, the specific treaty article of the relevant treaty, and the code section that the tax treaty provision overrules or modifies. You describe the treaty-based return position, summarize the facts behind it, and list the income items and amounts the relief covers.
The filing mechanics trip people more than the content. You attach Form 8833 to your federal income tax return for the year, usually a Form 1040-NR for a nonresident, and you never file it on its own when a return is due. If you would not otherwise have to file a federal tax return, you still file one with Form 8833 attached so the notice lands, since the form 8833 reporting only counts when the form is attached. One quirk to plan around: the form is generally not accepted for electronic filing, so an e-filed return usually needs a paper copy attached and mailed.
Here is the part that stings. If the form is required and you do not file it, section 6712 imposes a penalty of 1,000 dollars for an individual and 10,000 dollars for a C corporation, for each position you failed to disclose. The penalty is not tied to whether you owed more tax.
That last point surprises people. You can be fully entitled to the treaty relief, claim it correctly, and still owe the penalty simply because the filing was missing. The IRS can also challenge the underlying treaty claim. The one relief valve is reasonable cause, so if you missed the form, filing it promptly with a clear explanation gives you the best shot at abatement. It is a cheap form to file and an annoying one to skip.
A few patterns come up again and again. Students and researchers on F and J visas often claim treaty benefits and a treaty exemption on part of their income under their home country's article, and that claim usually needs the form; to claim tax treaty benefits you disclose a treaty-based position first. Foreign businesses claim no US permanent establishment under a treaty to keep business profits out of the US net. Investors take a reduced treaty rate on royalties or gains that domestic law would tax higher.
One thing the form is not for. It does not replace the foreign tax credit. The credit relieves double taxation by crediting foreign tax you paid, while Form 8833 discloses a treaty position that changes what the US taxes in the first place. They often show up on the same return, but they solve different problems, and relying on a treaty for the credit does not cover the disclosure.
Treaty work rewards precision. Naming the wrong article, missing an exception, or forgetting the form entirely all create problems that are easy to avoid and expensive to fix. The judgment call is usually whether a given benefit is a reportable position or one of the waived exceptions, and that turns on the specific income and the specific treaty. Madras Accountancy supports US CPA firms and their international tax clients on exactly this, mapping each treaty claim to the right article and code section and preparing the disclosure so it holds up.
If you have a treaty position to sort out, you can reach out here. This is general information, not tax advice, so a tax professional should confirm the treatment for any specific return, and you can review the official Form 8833 instructions for the current rules.
1. What is Form 8833? Form 8833 is the IRS Treaty-Based Return Position Disclosure required under section 6114. You attach it to your tax return to disclose that a US tax treaty overrules or modifies the tax code to reduce your tax.
2. Who must file Form 8833? Any US taxpayer, including individuals, corporations, estates, and trusts, who takes a treaty-based return position that reduces US tax must file Form 8833. Taxpayers resident in both countries who use a treaty tie-breaker file under Regulations section 301.7701(b)-7.
3. What is the penalty for not filing Form 8833? Section 6712 imposes a 1,000 dollar penalty for individuals and 10,000 dollars for C corporations, per undisclosed position. It applies even if the treaty relief was valid and you owed no extra tax, though reasonable cause can excuse it.
4. Do I need to file Form 8833 for reduced withholding on dividends? Usually not. If you receive a reduced rate on dividends, interest, or royalties and a withholding agent reports the payment on Form 1042-S, that position is generally an exception to filing Form 8833 under Regulations section 301.6114-1(c).
5. What is a dual-resident taxpayer? Someone taxed as a resident of both the US and a treaty country is a dual resident. If you use the treaty tie-breaker to be treated as a nonresident here, you disclose that treaty-based position on the return.
6. Can I e-file Form 8833? Often not directly. the form is generally not accepted for electronic filing, so an e-filed return usually needs a paper copy attached and mailed to the IRS.
7. Does Form 8833 replace claiming treaty benefits? No. You still claim the treaty benefit on your return; the form is the notice that tells the IRS a treaty is driving the position. The filing and the claim are two separate steps.
8. Which positions must be reported? Positions where a treaty overrules or modifies the Internal Revenue Code to lower your tax, such as claiming no permanent establishment, a treaty-based exemption, or a reduced rate not available under domestic law. Regulations section 301.6114-1(b) lists the specifically reportable ones.

The 2026 1099 reporting threshold changed: 1099-NEC and 1099-MISC now start at $2,000, and 1099-K is back to $20,000. Here is what you must file.

A plain guide to how a 2026 sales tax holiday works, which items are exempt, and the rules on price caps, refunds, and rain checks.

Form 7004 buys a 6-month extension of time to file business returns like 1065, 1120-S and 1120. Deadlines, e-file steps and the payment trap.



