

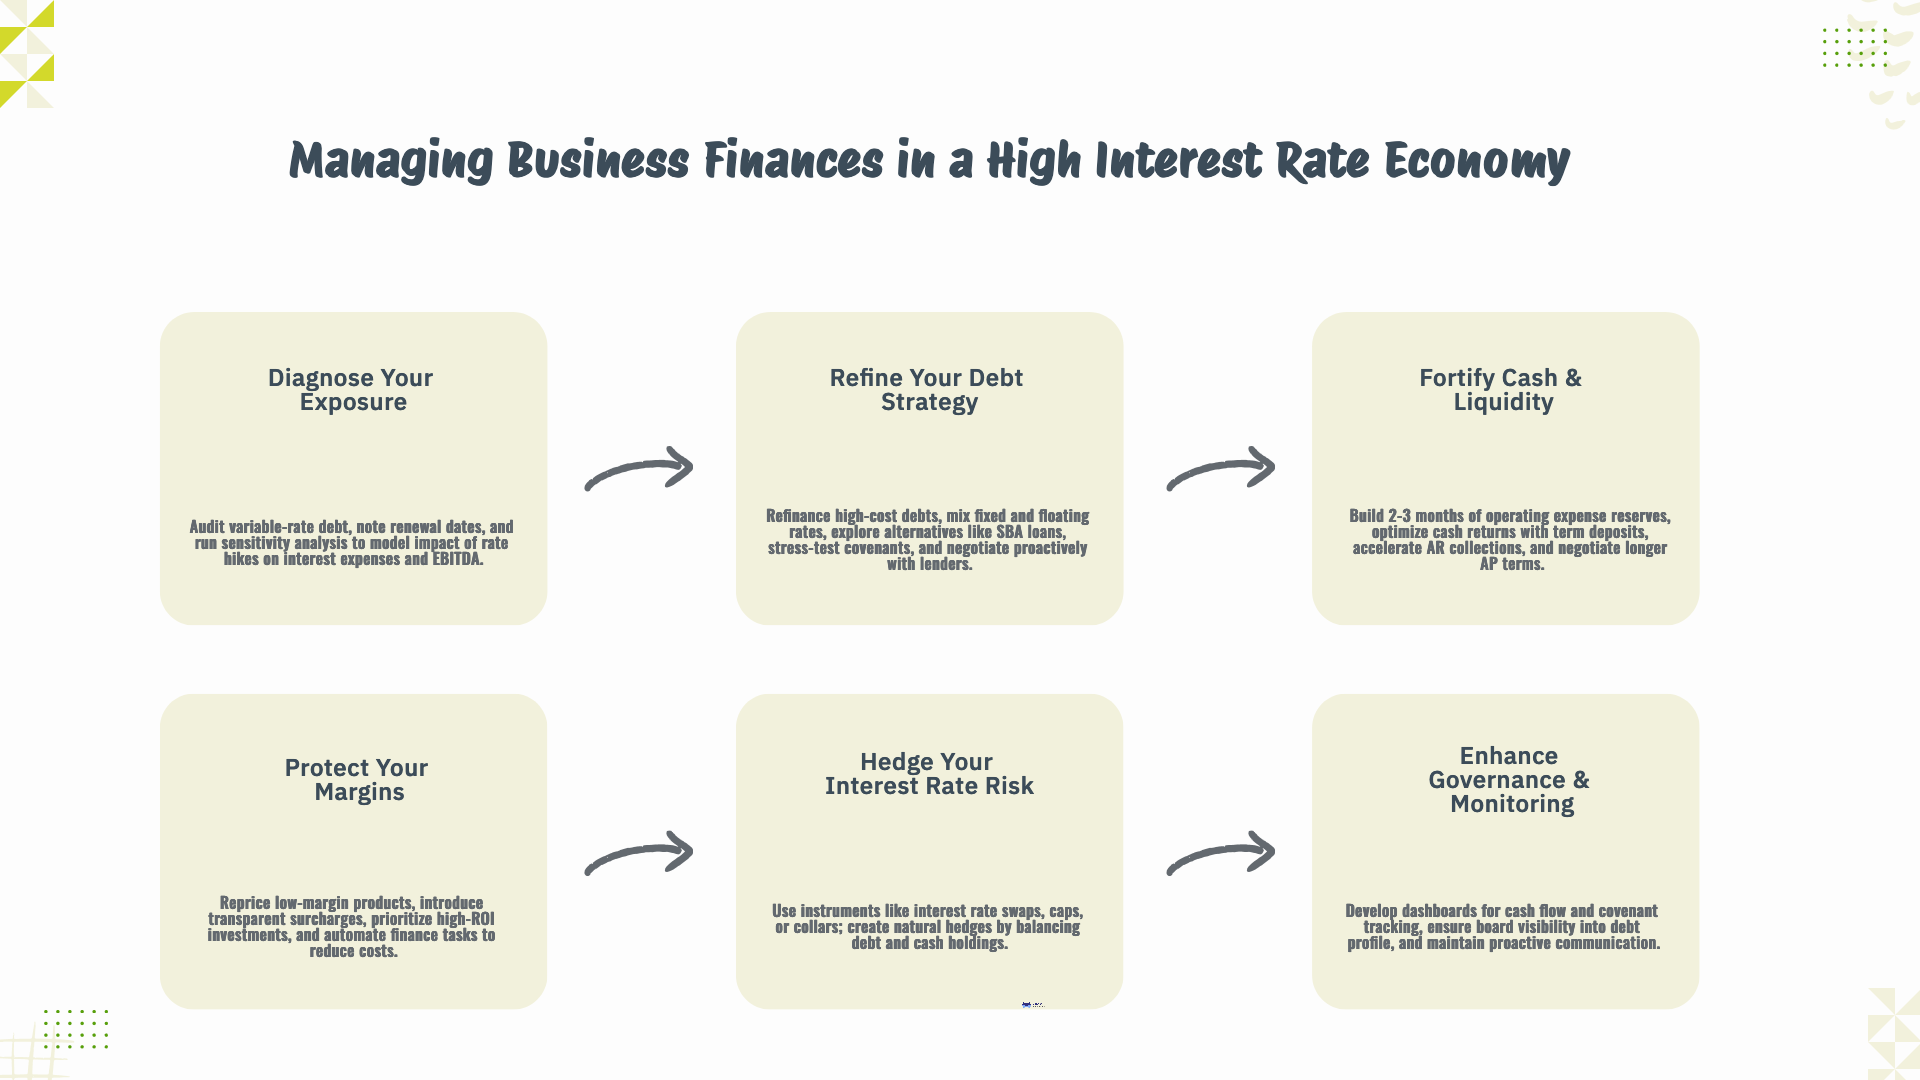

Managing business finances with high interest rates comes down to four jobs: know exactly what your debt costs and when it reprices, keep only the cash you need and put the rest to work against your most expensive borrowing, protect margins so interest does not eat operating profit, and claim every dollar of interest deduction the tax code now allows. As of late October 2026 (before the 27-28 October FOMC decision), the Federal Reserve's target range sits at 3.75% to 4.00% after a September increase, and the bank prime rate is 7.00%.
That rate level changes the math on revolving lines, equipment loans and idle cash balances. This guide covers how managing business finances with high interest rates works in practice for a US small or mid-sized company: where rates stand, how to measure your exposure, when refinancing pays, how to manage cash, and how the One Big Beautiful Bill Act (OBBBA) changed the business interest deduction for 2025 and later years.
On 16 September 2026, the Federal Open Market Committee raised the federal funds target range by a quarter point to 3-3/4 to 4 percent, noting that inflation "remains elevated." The committee meets on 27 and 28 October 2026 and announces its decision on the 28th, so check that statement for any change to the late October figures below.
Most small business credit does not price off the fed funds rate directly. It prices off the prime rate or a benchmark such as SOFR, plus a spread. The Federal Reserve's H.15 Selected Interest Rates release dated 26 October 2026 shows the following.
| Rate (H.15, 23 Oct 2026) | Level | Why it matters |
|---|---|---|
| Federal funds (effective) | 3.88% | Sets the floor for short-term borrowing and deposit yields |
| Bank prime loan rate | 7.00% | Base for most lines of credit and variable SBA loans |
| 3-month Treasury (constant maturity) | 4.22% | Benchmark for what idle cash can earn safely |
| 2-year Treasury (constant maturity) | 4.69% | Signal for fixed-rate pricing on 2 to 3 year loans |
As of late October 2026, prime at 7.00% sits exactly 3 points above the top of the Fed's target range. A line of credit priced at prime plus 1.5% therefore costs 8.50%, and any further Fed move flows through to that line within days.
Start with a debt schedule. List every loan, line and lease with its balance, rate, whether the rate is fixed or variable, the benchmark and spread, the maturity date, any prepayment penalty and every financial covenant. Pull the terms from the loan agreements themselves.
Then run a simple sensitivity test. Multiply each variable balance by 100 and 200 basis points to see what a further rate move adds to annual interest. Compare the result with operating cash flow and with your covenant headroom, such as the fixed charge coverage ratio or the maximum debt-to-EBITDA ratio your lender set. The financial ratio analysis your accountant prepares each quarter should include these covenant ratios recalculated under the higher-rate case.
Pay particular attention to maturity dates in the next 18 months. A term loan written at 4% that renews in 2027 could reprice several points higher.
With the exposure mapped, rank debts by after-tax cost and by how much a rate move would hurt. Three common moves apply.
Pay down the most expensive variable balance first. Revolving lines are usually the costliest debt a business carries and the most rate-sensitive. Paying them down with surplus cash gives a guaranteed return equal to the line's rate, and the business can usually redraw if it needs liquidity later.
Consider fixing part of the balance. Moving some variable debt into a fixed-rate term loan trades a slightly higher rate today for certainty. A business with thin covenant headroom often values the certainty more than the potential savings from future rate cuts.
Compare SBA 7(a) terms before signing a conventional renewal. The SBA caps 7(a) rates and leaves the actual rate to negotiation. According to the SBA's 7(a) terms and conditions, rates "are negotiated between the borrower and the lender, but are subject to SBA maximums, which are pegged to the prime rate or an optional peg rate." Most 7(a) loans have a maximum amount of $5 million. Terms are generally 10 years or less unless the loan finances real estate or equipment with a longer useful life, with a 25-year maximum.
| Variable 7(a) loan amount | SBA maximum rate | Ceiling at 7.00% prime (late October 2026) |
|---|---|---|
| $50,000 or less | Base rate plus 6.5% | 13.50% |
| $50,001 to $250,000 | Base rate plus 6.0% | 13.00% |
| $250,001 to $350,000 | Base rate plus 4.5% | 11.50% |
| Greater than $350,000 | Base rate plus 3.0% | 10.00% |
These are ceilings, and a strong borrower can negotiate lower. The SBA publishes fixed-rate maximums separately on its lender wiki. If you plan to apply, start with clean financials and a lender-ready package; our guide to business loan preparation and documentation lists what underwriters ask for.
Before refinancing, check for prepayment penalties, origination and guaranty fees, and legal costs. Divide total switching costs by annual interest saved to get a payback period. Many finance teams use 12 to 24 months as a rough cutoff; treat that as guidance and adjust for how long you expect to hold the debt.
At late October 2026 rates, a line of credit at prime plus 1.5% costs 8.50% and a 3-month Treasury yields 4.22%, so holding excess cash while carrying a revolver balance costs the business the difference. Cash management in a high-rate economy means setting a reserve target, then putting every dollar above it against expensive debt or into a safe, liquid yield.
Set the reserve from your own numbers. A common practitioner guideline is two to three months of fixed operating costs, adjusted for seasonality and customer concentration. A cash flow forecast built with the right tools tells you the low point in the coming quarter, which matters more than a rule of thumb. For businesses with lumpy revenue, cash flow scenario planning techniques show how the reserve holds up if sales drop or a large customer pays late.
Keep deposit insurance limits in mind. The FDIC insures deposits to at least $250,000 per depositor, per ownership category at each FDIC-insured bank, and Treasury bills held in a brokerage account are a separate product that the FDIC does not cover. Businesses holding several million in cash often spread balances across banks or hold part of the reserve in Treasury bills.
Every day a customer takes to pay is a day you may be funding with borrowed money. At 8.50% (prime plus 1.5% as of late October 2026), $1 million in receivables outstanding for an extra 30 days costs roughly $7,000 in line interest. Tighten invoicing, send statements on a fixed schedule, and follow up on past-due accounts weekly. If collections are a recurring weak point, accounts receivable services for small businesses can take over the follow-up work.
On the payables side, pay on the due date, take early payment discounts only when the annualized return beats your borrowing cost, and negotiate longer terms with suppliers where your purchase volume gives you bargaining power. A disciplined process for outsourcing accounts payable keeps payment timing consistent. Our broader guide to working capital management strategies for growing businesses covers inventory turns as well.
Interest expense comes out of operating profit, so margins have to carry it. Review pricing on low-margin products and customers, and check whether the cost of carrying inventory or extended payment terms is built into the price. A customer who takes 75 days to pay on thin margins may be unprofitable once financing cost is counted. Our article on profit margin improvement strategies explains how to find those accounts.
Capital projects deserve a fresh look too. A project that cleared an 8% hurdle when debt cost 5% may not clear a higher hurdle today. Rerun the return on any expansion financed with variable debt, and defer projects that only work if rates fall. Updating forecasts monthly through a rolling forecast keeps those decisions tied to current rates.
Higher rates mean more interest expense, and larger businesses face a cap on how much of it they can deduct each year. The OBBBA restored a more generous version of that cap.
The Instructions for Form 8990 explain that P.L. 119-21, the One Big Beautiful Bill Act, "amended section 163(j) to allow an add-back to taxable income for any deduction allowable for depreciation, amortization, or depletion to determine ATI for tax years beginning after 2024." In practice, adjusted taxable income (ATI) is once again computed on an EBITDA-like basis instead of an EBIT-like basis. The applicable percentage is still 30% of ATI.
Two other rules matter for planning:
For capital-intensive companies with significant depreciation, the add-back can turn a partially deductible interest bill into a fully deductible one. Our detailed guides to section 163(j) and the business interest expense limitation and to what changed in the business interest limitation for 2026 walk through the Form 8990 calculation line by line.
The following figures are illustrative. Harbor Supply Co. is a distributor with average annual gross receipts of $45 million, so it is above the $32 million threshold and subject to the interest limit. Its position in October 2026:
Current interest cost. The revolver costs $6,000,000 × 8.50% = $510,000 a year. The term loan costs $2,500,000 × 6.75% = $168,750. Total interest is $678,750. A further 100 basis point increase would add $60,000 on the revolver, and 200 basis points would add $120,000.
Cash decision. Harbor sets a reserve of two months of fixed costs, or $3,000,000. That leaves $1,800,000 of excess cash. Investing it at the 3-month Treasury yield of 4.22% (23 October 2026) would earn $75,960. Using it to pay down the revolver saves $1,800,000 × 8.50% = $153,000. Paying down the line comes out $77,040 ahead before tax, and Harbor can redraw if the forecast turns.
After the paydown, the revolver balance is $4,200,000 and costs $357,000. Total interest falls to $525,750. The exposure to a 100 basis point rise drops from $60,000 to $42,000.
Interest deduction. Without the depreciation add-back, which OBBBA reinstated, Harbor's limit would be 30% × $1,400,000 = $420,000, leaving $258,750 of its original $678,750 interest disallowed and carried forward. Under the OBBBA rule, ATI adds back the $900,000 of depreciation to reach $2,300,000. The limit becomes 30% × $2,300,000 = $690,000, so the full $678,750 is deductible. After the paydown, Harbor's $525,750 of interest leaves $164,250 of unused capacity under the limit, which can absorb any carryforward from earlier years.
| Item | Before paydown | After paydown |
|---|---|---|
| Revolver balance | $6,000,000 | $4,200,000 |
| Annual interest | $678,750 | $525,750 |
| Cost of a 100 bp rise | $60,000 | $42,000 |
| Interest limit under OBBBA | $690,000 | $690,000 |
| Unused limit | $11,250 | $164,250 |
The real ATI calculation includes further adjustments for items such as net operating losses and the section 199A deduction, so run the full Form 8990 computation before relying on these figures.
Rate risk needs an owner. Add a one-page debt and liquidity report to the monthly close package showing balances, rates, next repricing dates, covenant calculations, cash against the reserve target, and the 100 basis point sensitivity figure. Owners and boards should see refinancing windows at least two quarters ahead. If the business has real estate holdings, the separate issues covered in our guide to real estate investing with high interest rates apply as well.
Larger borrowers sometimes use interest rate swaps or caps through their lender. They carry their own costs and accounting. For most small businesses, paying down variable balances and fixing part of the remaining debt achieves a similar result with less complexity.
What is the first step in managing business finances with high interest rates? Build a complete debt schedule showing every balance, rate, benchmark, maturity and covenant, then calculate what a 100 and 200 basis point rise would add to annual interest.
Should a business pay down debt or invest surplus cash when rates are high? Compare the rate on your most expensive debt with what safe cash can earn. As of late October 2026, with prime at 7.00%, a line priced at prime plus 1.5% costs 8.50% while 3-month Treasuries yield about 4.22%, so paying down the line usually wins once a reserve is in place.
What are the SBA 7(a) maximum interest rates in 2026? For variable-rate 7(a) loans, the SBA caps rates at the base rate plus 6.5% for loans of $50,000 or less, plus 6.0% up to $250,000, plus 4.5% up to $350,000, and plus 3.0% above $350,000. With prime at 7.00% as of late October 2026, those ceilings are 13.50%, 13.00%, 11.50% and 10.00%.
How did the One Big Beautiful Bill Act change the business interest deduction? For tax years beginning after 2024, depreciation, amortization and depletion are added back when computing adjusted taxable income, which raises the 30% limit for most capital-intensive businesses. Businesses that meet the gross receipts test ($32 million for 2026) are exempt from the limit entirely.
When does refinancing a business loan make sense? Refinancing makes sense when the annual interest saved repays the switching costs, including prepayment penalties and fees, within the period you expect to hold the debt. A 12 to 24 month payback is a common practitioner guideline.
Madras Accountancy supports US businesses with bookkeeping, tax preparation, and CFO and advisory work, including debt schedules, cash forecasts, lender packages and Form 8990 calculations. To review your financing position, contact our team.

The section 4960 excise tax is 21% of nonprofit pay over $1M. From 2026 it covers all employees. See the medical carve-outs, Form 4720 and a worked example.

The paid family and medical leave tax credit is permanent from 2026. See the 12.5% to 25% rates, the premium option, the 6-month rule and how Form 8994 works.

Opportunity zones become permanent in 2027 under the One Big Beautiful Bill. See the new deferral, rural bonus, and the 2026 handoff.



